Google’s new earnings report will only be released after the market closes, so let’s first talk about what the market is expecting.
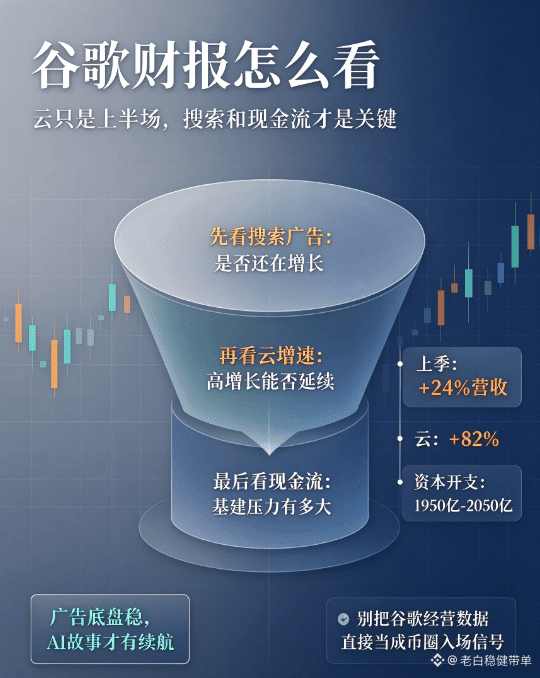
Last quarter, Google brought in $119.8 billion in revenue, up 24%. Search advertising held steady, while its cloud business surged 82%. The established business is still making money, and the newer one is growing at breakneck speed. But there’s a potential risk: Google is pouring huge amounts of money into buying chips and building data centers. Free cash flow turned negative last quarter, and its full-year capital expenditure forecast was raised again to nearly $200 billion. The money comes in, then goes straight into computing infrastructure.
The market expects revenue to grow another 25% this quarter, but earnings per share to rise only 5%–6%—a classic case of revenue growth without profit growth. The cloud business has now become profitable, with margins climbing above 35%, so it’s not just burning cash. Management has also said it is deliberately turning down some cloud orders to make room for AI research and development, and computing capacity will remain tight next year.
A lot of people are expecting cloud to keep doubling and surging, but here’s a reminder: even spectacular cloud results can’t make up for the huge cash drain from infrastructure spending. The connection to crypto is simple: as long as advertising holds steady and computing capacity remains in short supply, the AI narrative can keep going. But if search ad growth starts to slow, be careful.
When you look at the earnings report after the market closes, don’t focus only on cloud. Pay close attention to search advertising and cash flow.
I’ll be breaking down the earnings report live in the chat after the market closes and sharing related opportunities across the AI sector. Come join us if you want to follow along!
#谷歌财报能否守住基本盘
Last quarter, Google brought in $119.8 billion in revenue, up 24%. Search advertising held steady, while its cloud business surged 82%. The established business is still making money, and the newer one is growing at breakneck speed. But there’s a potential risk: Google is pouring huge amounts of money into buying chips and building data centers. Free cash flow turned negative last quarter, and its full-year capital expenditure forecast was raised again to nearly $200 billion. The money comes in, then goes straight into computing infrastructure.
The market expects revenue to grow another 25% this quarter, but earnings per share to rise only 5%–6%—a classic case of revenue growth without profit growth. The cloud business has now become profitable, with margins climbing above 35%, so it’s not just burning cash. Management has also said it is deliberately turning down some cloud orders to make room for AI research and development, and computing capacity will remain tight next year.
A lot of people are expecting cloud to keep doubling and surging, but here’s a reminder: even spectacular cloud results can’t make up for the huge cash drain from infrastructure spending. The connection to crypto is simple: as long as advertising holds steady and computing capacity remains in short supply, the AI narrative can keep going. But if search ad growth starts to slow, be careful.
When you look at the earnings report after the market closes, don’t focus only on cloud. Pay close attention to search advertising and cash flow.
I’ll be breaking down the earnings report live in the chat after the market closes and sharing related opportunities across the AI sector. Come join us if you want to follow along!
#谷歌财报能否守住基本盘