Microsoft earnings show AI investment entering the return-validation phase
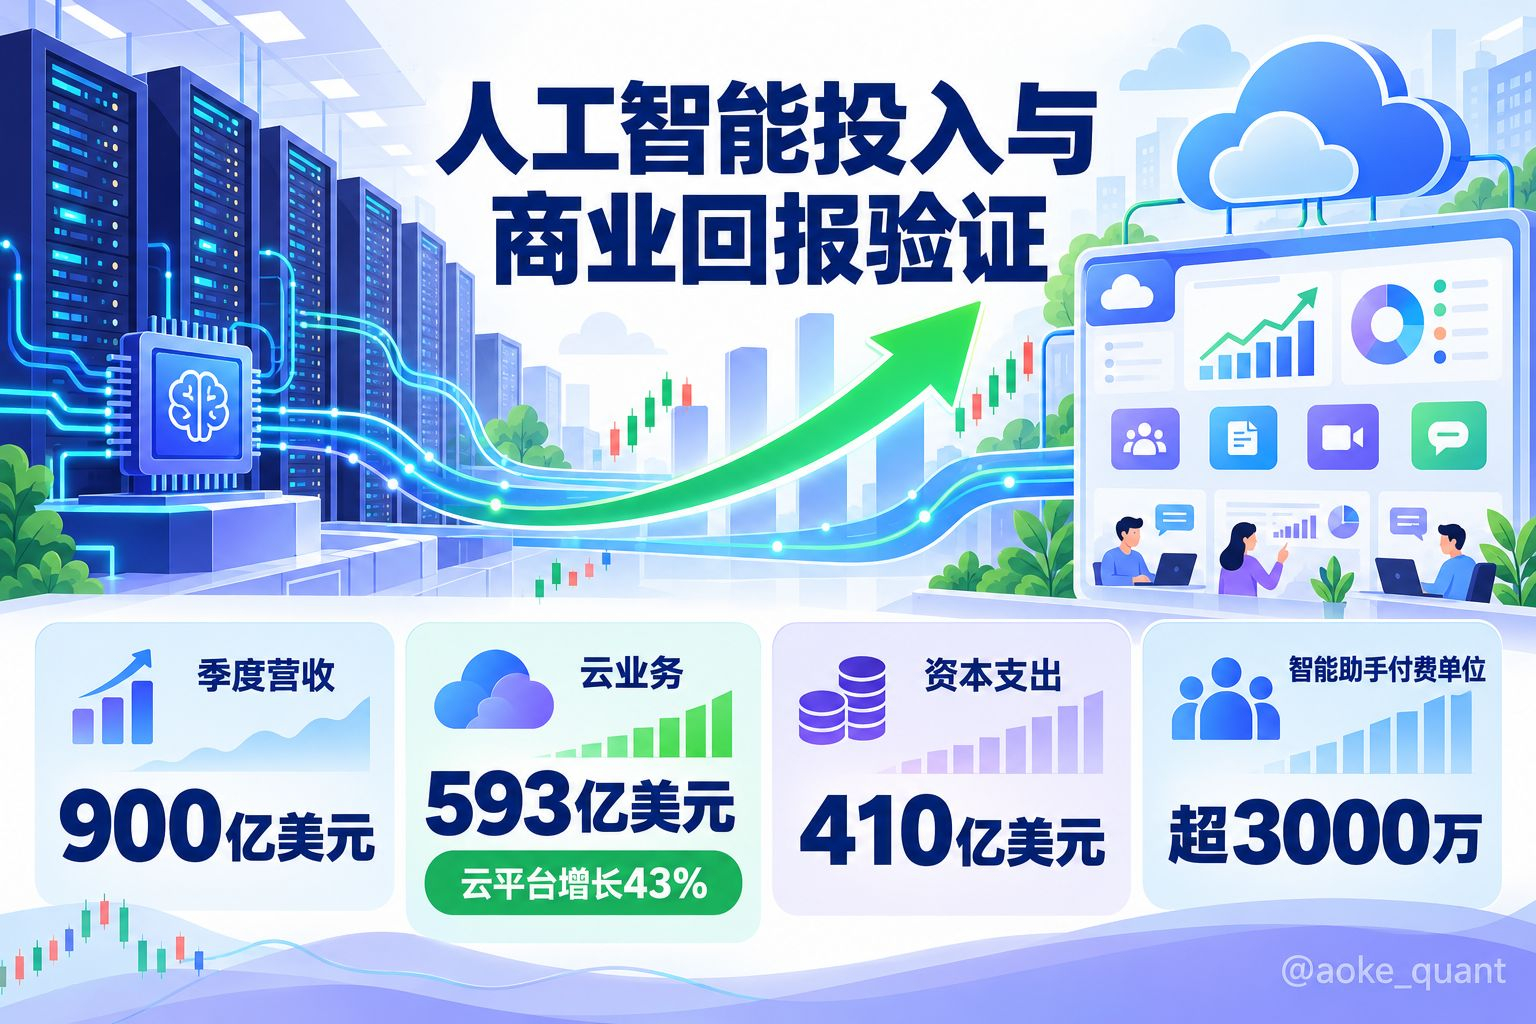
Microsoft’s quarterly results, announced on July 29, provide a concrete example for investors assessing whether AI investment can translate into revenue. According to the reported figures, Microsoft generated $90 billion in revenue in the April–June quarter, up 18% year over year. Revenue from its cloud business reached $59.3 billion, up 27%, while Azure revenue grew 43%. Amid continued expansion of investment in AI infrastructure, these cloud figures have become an important measure of the efficiency of its commercialization.
The key issue is not simply revenue growth, but whether revenue and investment can form a verifiable feedback loop. Microsoft’s capital expenditures reached $41 billion this quarter, indicating that data centers, computing capacity, and related infrastructure are still expanding rapidly. The market is not inherently opposed to high capital spending. Its real concern is whether genuine demand will absorb the additional capacity, and whether future revenue growth can cover depreciation, operating costs, and pressure on cash flow.
Microsoft’s strategy is relatively clear: enterprise customers buy cloud services, Azure handles training and inference workloads, and products such as Copilot are then integrated into office, development, and collaboration software. Publicly available information shows that Azure revenue surpassed $100 billion in Microsoft’s 2026 fiscal year, while paid Microsoft 365 Copilot seats exceeded 30 million. These metrics do not mean that AI investment is risk-free, but they show that productization and paid adoption have measurable indicators, rather than existing only as a technology narrative.
Across the sector, the market is drawing sharper distinctions between the quality of different companies’ AI spending. When AI investment corresponds to growth in cloud businesses, enterprise software subscriptions, or identifiable customer demand, capital spending is more readily seen as an upfront cost of expansion. When returns are difficult to isolate and cash-flow pressure arrives first, valuations may become more sensitive to spending guidance. Therefore, future assessments should not focus solely on quarterly revenue, but also consider cloud growth, paid-product adoption, the pace of capital spending, and free cash flow.
For crypto markets, these earnings reports will not directly change the supply and demand for on-chain assets, but they may affect related narratives through shifts in risk appetite. If demand for AI infrastructure is validated, interest may increase in sectors such as computing power, data centers, decentralized computing, and AI applications. Conversely, if massive investment fails to translate into revenue, valuations across growth assets may face lower tolerance. Any impact here would be transmitted through cross-market sentiment and capital preferences, not a deterministic price relationship.
The editorial view is that the AI theme is shifting from “whether to invest” to “how to recoup the investment.” The significance of Microsoft’s latest results lies in the evidence they provide of cloud growth and the expansion of paid products. However, whether AI revenue can sustainably outpace infrastructure costs will need to be tested over several more quarters. For readers following narratives at the intersection of crypto and technology, the focus should perhaps be on whether commercialization metrics continue to improve, rather than treating a single earnings report as a definitive verdict on the sector.
#微软财报能否兑现ai红利 #BTC #ETH #BNB