

This latest crypto market rally—from 60K to over 80K—has largely revolved around #RWA! 🧐
But honestly, after looking at a whole host of projects, most are still focused on tokenizing U.S. Treasuries, gold, stocks, and real estate.
Let's look at this from first principles: when stocks or U.S. Treasuries held by a traditional SPV structure are packaged and mapped onto the blockchain, what happens in essence is that a copy of the “asset rights” is made. Buyers are actually giving up direct legal ownership in exchange for little more than:
• The ability to buy fractional shares
• Easier transfers
• A bit more liquidity, or perhaps more anonymity
But for the real economy, the underlying logic hasn’t changed at all. Blockchain hasn’t fundamentally transformed the industry.
That’s why I’ve always felt that the next step for RWA can’t just be getting everyone to buy a few more tokenized U.S. stocks on-chain.
Just look at cross-border e-commerce to see how deep the pain points run 📊
Many Amazon sellers do great sales, but cash-flow constraints can leave them gasping for air:
• Platform payment terms range from 14 days to nearly a month. Add multiple layers of settlement for cross-border payments, and sellers can only watch orders pour in without having the money to restock.
• Get a bank loan? You need collateral and an audit report, and disbursement can take months.
• Go to a traditional financing provider? The process is cumbersome, and even the fastest option takes until T+1—plus intermediaries take a hefty cut.
That’s also why I believe RWA + PayFi is the direction with real Token Alpha.
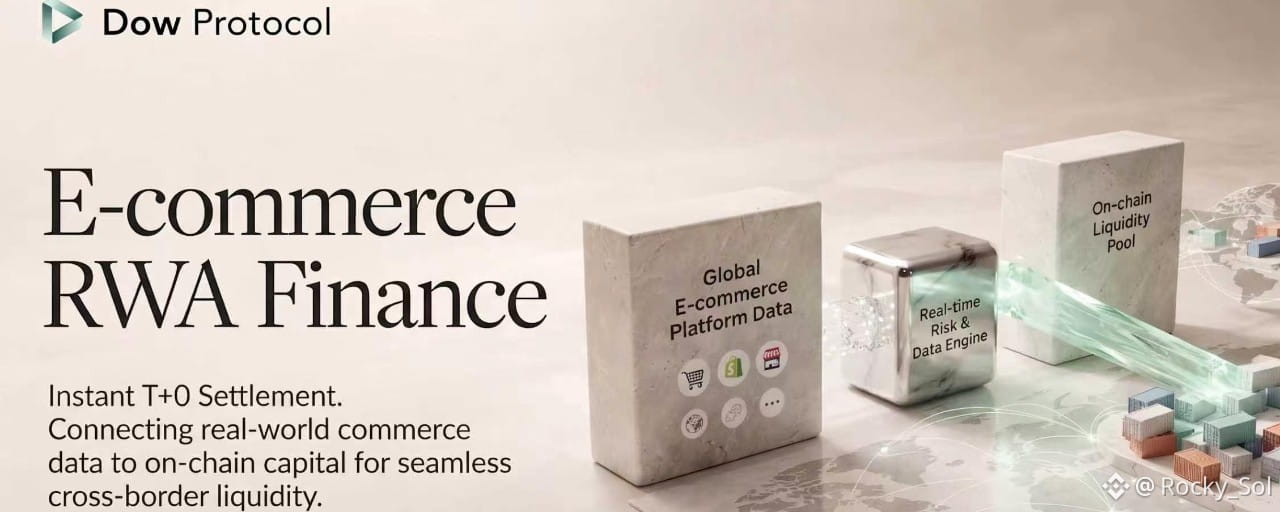
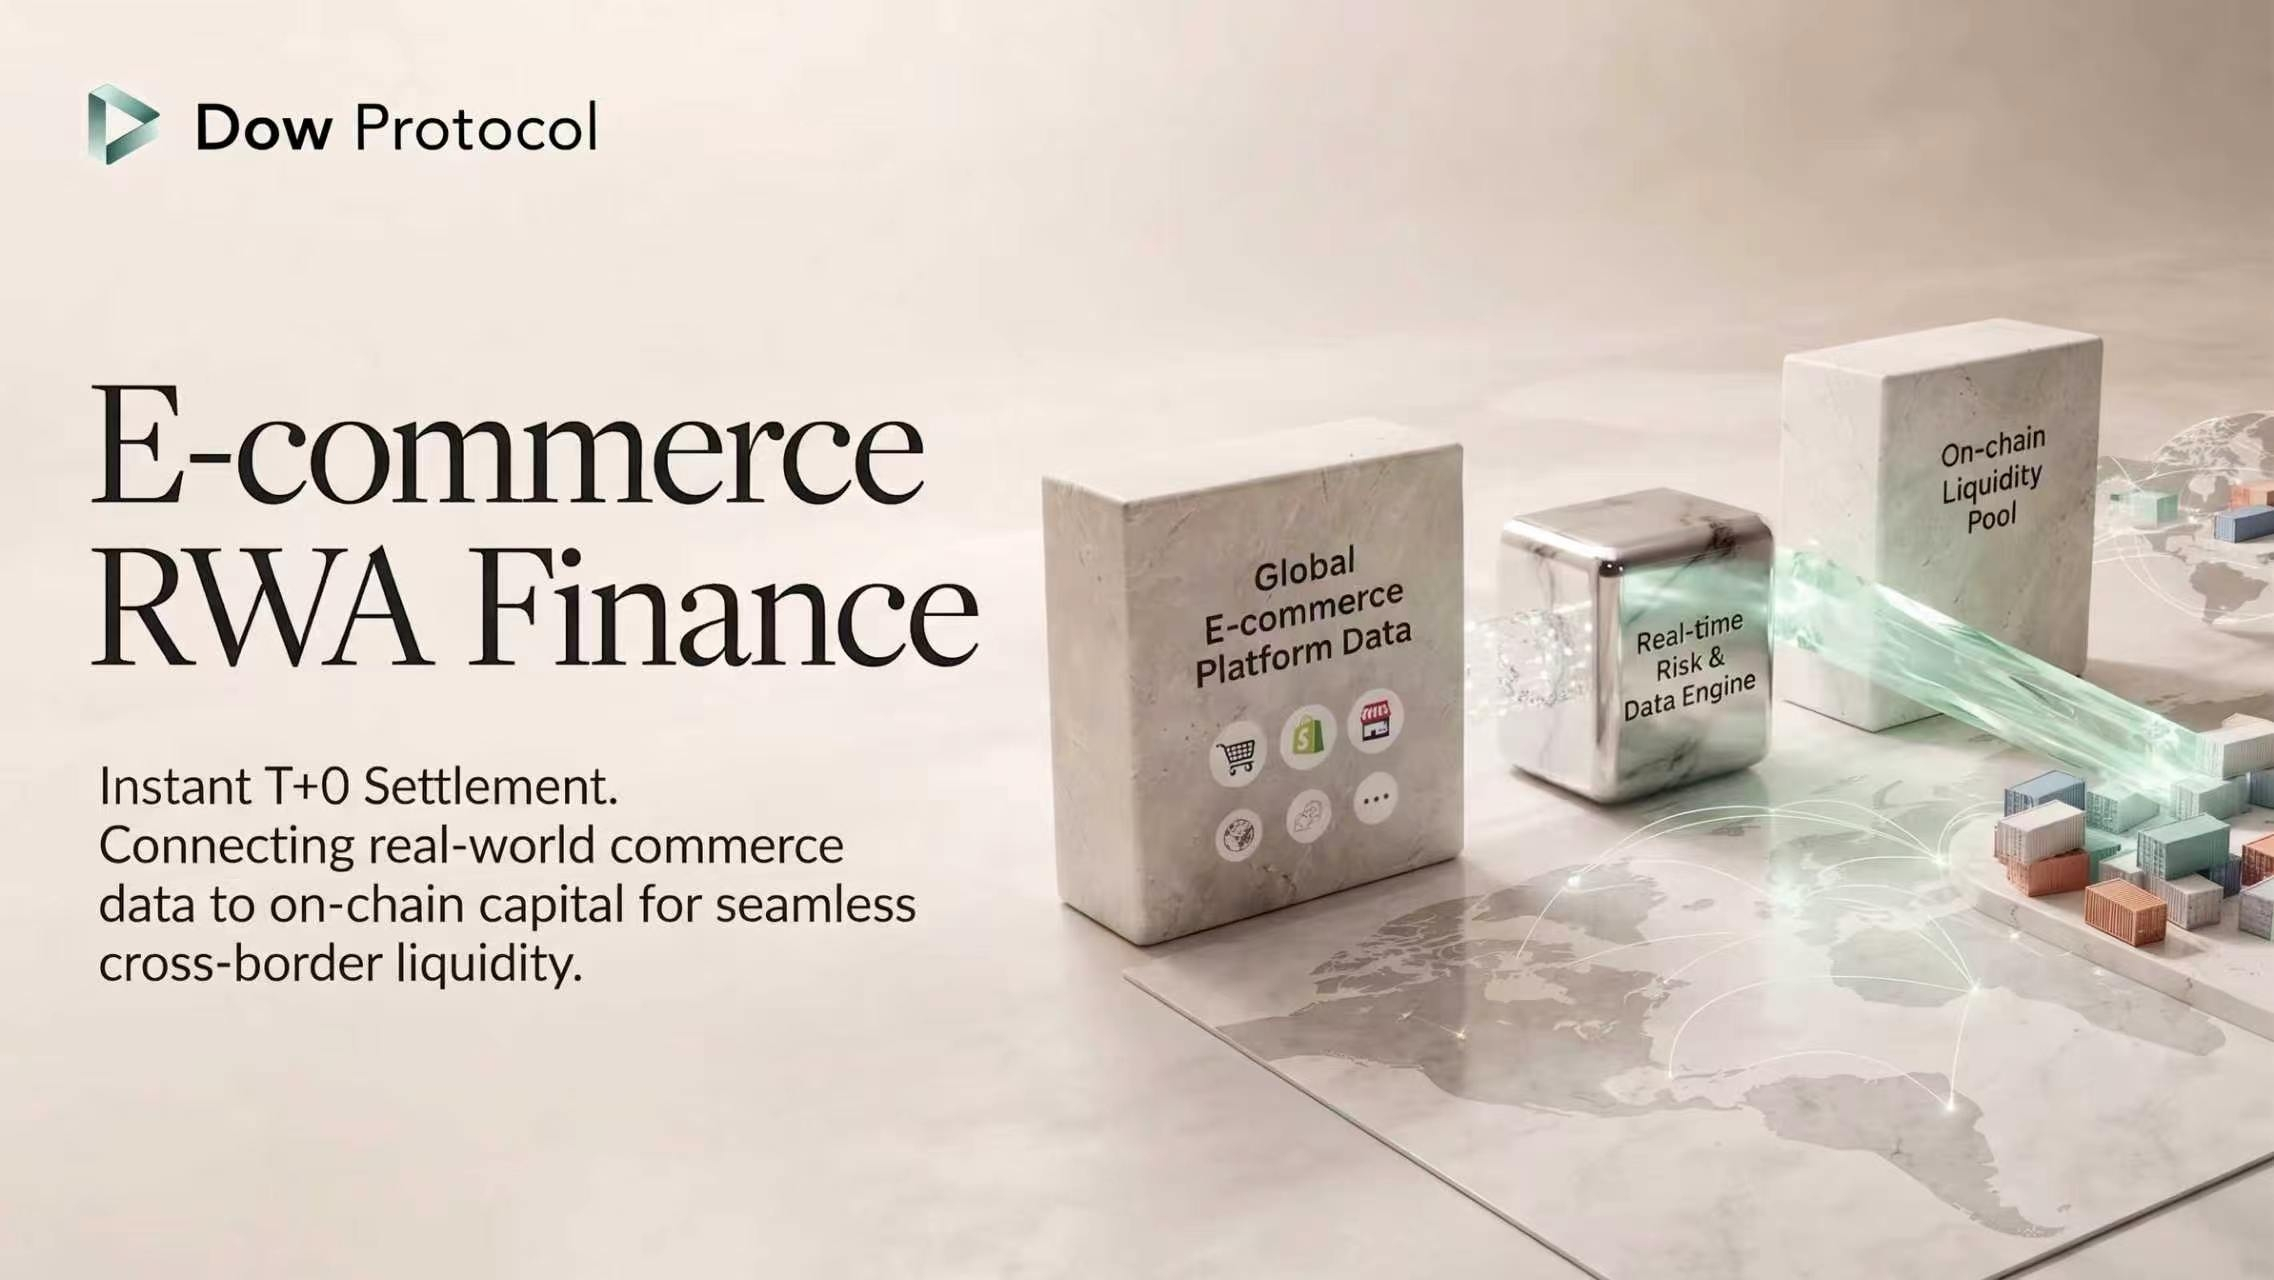
Take DowProtocol, for example. Instead of putting gold or stocks on-chain, it brings the receivables and real commercial cash flows that e-commerce sellers need most onto the blockchain.
Why are traditional institutions so slow? They rely on manual reviews for risk control and investigate only after something goes wrong.
Dow connects directly to native operational data from e-commerce platforms, giving real-time visibility into merchants’ business performance. Combined with risk-control models and near-instant cross-border settlement on-chain, it takes loan processing from days or months to T+0: apply today, get funded today.
The benefit for sellers is immediate: money tied up in payment cycles is suddenly put to work.
The benefit for on-chain capital is just as clear: returns don’t depend on storytelling or a narrative premium, but come from real lending interest generated by e-commerce in the real world.
Real cash flow + programmable settlement + commercial-grade risk control—that’s what blockchain should do as financial infrastructure.
Now, about the market. Last year, it was all about Meme and AI. People are tired of it now, and pure concepts with no actual revenue, driven solely by PvP, are becoming harder and harder to sustain.
With the space crowded with cookie-cutter RWAs, PayFi projects like Dow—which focus on real commercial needs and come with genuine cash flows—are better positioned to stand out as narratives rotate.
One more detail: Dow’s official account has been hinting at something big lately. They’ve never used this kind of tone before, so it feels like they’re building hype for an upcoming event.
Could it be related to an airdrop or farming? Hard to say. I’ll keep an eye on it 👀
Think about it a little more deeply: Why has the team suddenly started building hype? Could a major move be coming?
Let’s wait and see. This is for research and sharing purposes only, not advice. DYOR 🙏