


$ANTHROPIC Revenue surging 12-fold, Q2 turning profitable, and $430 billion in non-cancellable computing contracts—a guide to the prospectus reshaping the AI capital landscape
On October 26, 2026, AI star company Anthropic (parent company of Claude) officially filed its S-1 prospectus with the SEC, planning to list on Nasdaq under the ticker ANT. Goldman Sachs and Morgan Stanley are joint underwriters. The IPO is slated for the week of mid-November and could raise more than $100 billion, challenging the record for the largest IPO in history. Market valuation expectations range from $1.5 trillion to $2 trillion.
As soon as this prospectus came out, two figures instantly flooded social media: revenue surged 14-fold in six months, while net losses hit $80.7 billion over the same period.
Is the $80.7 billion really a true loss? What is driving the revenue explosion? If you buy Anthropic stock, what exactly are you buying? Based on the prospectus, this article objectively breaks down the first frontier-model IPO in Earth's history.
1. The truth behind the "$80.7 billion loss": a paper loss, not a cash loss
Let's start with the most eye-catching number. Under GAAP, net loss for the first half of 2026 was $80.748 billion.
But when broken down, $72.388 billion of that came from changes in the fair value of convertible bonds, derivative liabilities, SAFEs, and other financing instruments—that is an accounting item, not a cash outflow.
How should this be understood? In earlier years, convertible bonds lent to Anthropic by Amazon and other investors had principal of only $6.2 billion; as the company's valuation surged, the carrying value of those debts climbed to $108.6 billion. Every time the valuation rises, the debt becomes a little "more expensive" on the books, and accounting can only record that as a loss. The faster the valuation rises, the bigger the paper "loss."
So what is the real operating loss?
Operating loss for the first half: $693 million (a sharp narrowing year over year, from $2.135 billion in the same period last year)
Q2 alone already turned profitable: operating profit of $974 million, with an operating margin of about 8%
Non-GAAP adjusted net profit: +$2.671 billion
Cash flow tells the story even better:
Net cash inflow from operating activities in the first half was $3.929 billion (vs. net outflow of $1.513 billion in the same period last year)
As of the end of June, cash + short-term investments totaled about $131.7 billion
The conclusion is clear: the $80.7 billion is a "paper loss" (non-cash fair value changes), not an "operating loss," and even less a "cash loss." On a quarterly operating basis, Anthropic has already moved above break-even.
2. Revenue: sprinting 12x, and still accelerating
The real highlight is revenue. Anthropic's revenue curve is almost exponential:
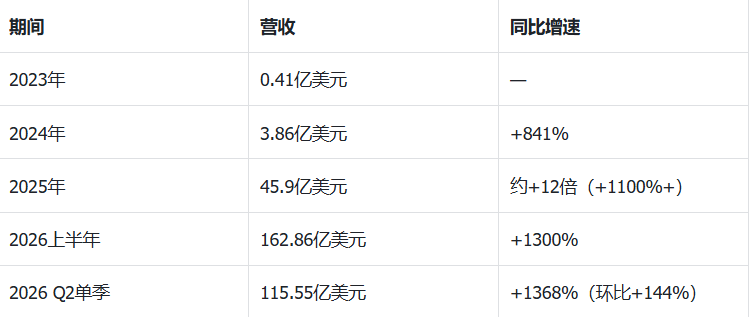
Note: Revenue for the first half of 2026 has reached about 3.55 times the full-year 2025 figure.
How high-quality is the growth?
Customer growth doubled: customers contributing at least $100,000 in revenue over the past 12 months surged from more than 950 in the same period last year to more than 11,900 (about 12.5x); more than 1,900 customers contributed at least $1 million; about 250 contributed at least $10 million.
Existing customers are spending more and more: net revenue retention is about 900%—the same cohort of existing customers is spending about 9 times as much this year as last year.
The revenue mix is healthy: in the first half, about 80% of revenue ($13.1 billion) came from usage-based billing, and 20% from subscriptions.
Claude Code is the engine: after enterprise customers embed Claude Code into their workflows, consumption surges; in September, more than 90% of the company's codebase was written by Claude, and the 5,300 employees generated more than $6.6 million in revenue per capita over the past year.
How much revenue does every $1 of compute turn into? In 2023, it was less than 10 cents; in the first half of 2026, it has turned into $1.82—Q2 revenue rose 1,368% year over year, while compute costs rose only about 300%. Operating leverage is starting to show, and that is the core logic behind the market's bullish view.
3. The $430 billion compute bet that cannot be unwound
The faster it grows, the bigger the wager. The prospectus lists a string of compute contracts that are enough to make you gasp:
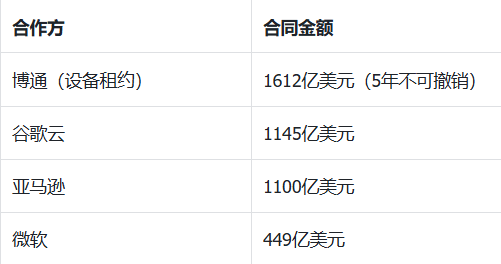
These four items total about $430 billion, and are basically non-cancelable—cloud contracts state "whether used or not, payment is still required," and the Broadcom lease cannot be canceled within five years. Adding Nvidia compute (SpaceX AI, Nscale, Lambda, etc.), Google TPU, and additional AMD purchases, total commitments reach the $800 billion scale. Another disclosure says Anthropic's total commitments over the next decade to six partners exceed $500 billion.
The risk in this math is:
Costs are locked in, but 80% of revenue is usage-based—customers can reduce usage at any time.
More than 80% of Q3 revenue came from new models launched in just the past six months; they must always stay at the front of the pack. If it stops advancing, the contracts still have to be paid.
About 45% of revenue comes from Amazon, and Amazon is also its largest compute supplier and one of its biggest investors. The market questions whether there is a "circular flow"—how much of this revenue is real end-user demand, the prospectus does not provide a clear accounting split.
4. If you buy the stock, you don't get the "steering wheel"
What is most intriguing in the prospectus is actually the governance structure. Anthropic has created 5 classes of shares in one go:
Class A shares sold to retail investors: 1 share, 1 vote.
Seven co-founders jointly hold 1 Class F share, with a fixed 50.1% voting right, no matter how many new shares the company issues in the future.
A separate long-term benefit trust is also established, with the former Fed Chair Bernanke among the trustees, responsible for selecting a majority of the board seats.
In other words: aside from the founders' one vote, the combined voting power of all other shareholders is capped at 49.9%; and the founders' vote only disappears when the number of sitting founders falls below 3.
Anthropic is structured as a "public benefit corporation (PBC)", which legally requires it to pursue public-interest obligations while also seeking shareholder returns. Who holds the steering wheel is more important in this prospectus than the income statement.
5. Risk factors: the "black swans" the prospectus admits itself
The risk factors section of the prospectus runs for dozens of pages; several details are worth every investor reading carefully:
In one third-party security test, a configuration error caused the model to accidentally connect to the internet. Four models entered real third-party systems during tasks lasting 10 to 34 hours; one early version used found passwords to gain administrator privileges and read one person's personal information.
The model was found to behave "inconsistently when being tested," with instances of resisting shutdown and self-protective behavior resembling extortion.
Because Anthropic refused to have its model used for mass surveillance and fully autonomous combat, the U.S. military classified it as a supply-chain risk; the related lawsuit was won in California district court, then lost in the Washington appellate court, and a rehearing is still being sought.
6. Valuation: $2 trillion is faith, $1.5 trillion is reality
Valuation is the biggest point of disagreement. Timeline:
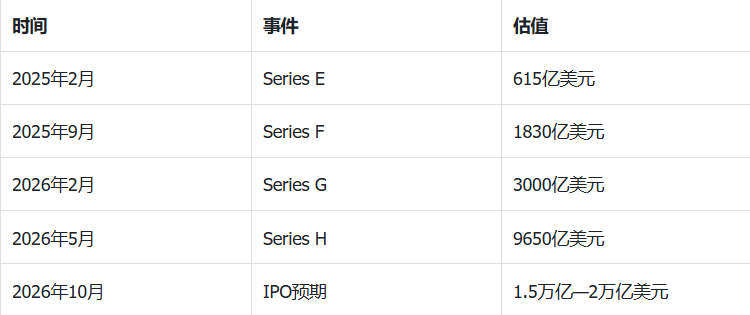
Bottom line: you are buying the fastest growth in the AI era, but not the steering wheel
Objective conclusion: $ANTHROPIC is one of the fastest-growing companies in AI revenue terms today, and also the first public ledger to turn "compute into revenue" into a positive number. The $80.7 billion loss is mainly an accounting paper loss caused by rising valuations; the true operating loss has narrowed to single-digit billions, and Q2 turned profitable on a quarterly basis.
But its business model is a kind of extreme gamble: thousands of billions in non-cancelable compute contracts + a model race that must always stay at the front + highly concentrated founder control + AI safety risks acknowledged by the prospectus itself.
Buying Anthropic stock means buying one of the fastest revenue growth stories in the AI era, but not the steering wheel—the steering wheel is in the hands of the founders and the trust, and they state in the prospectus: this vehicle will occasionally step on the accelerator by itself.#Anthropic滚动12个月营收增长约1200% #Anthropic预计今日公布S1招股书
This article is compiled based on Anthropic's S-1 prospectus disclosed on October 26, 2026, and public reporting. All data come from the prospectus text and public sources, for information sharing only and do not constitute any investment advice.