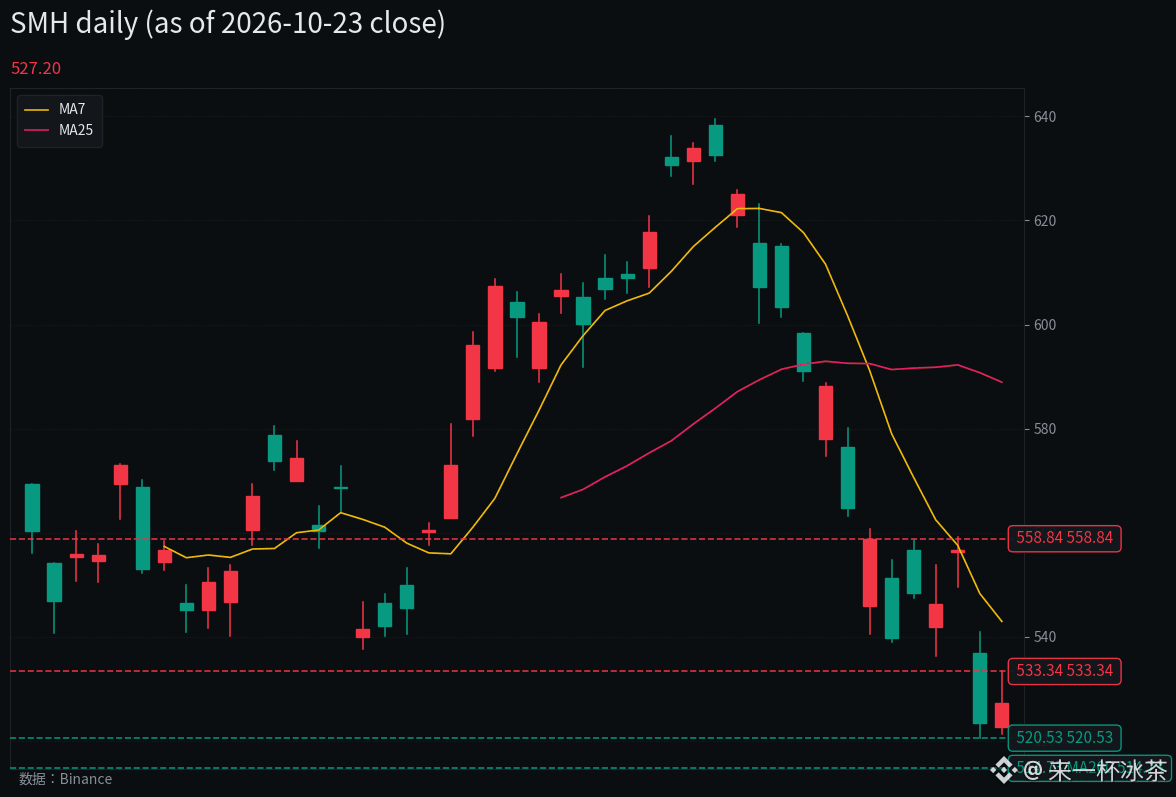
$SMH at $527, down 21% from its highs: This is the week storage stocks have to show their cards.
Last Friday’s close (U.S. Eastern time, Oct. 23): $SMH 527.20 USD (+0.74%), Micron $MU 877.55 USD (+2.46%), SanDisk $SNDK 1238.03 USD (-1.82%), Western Digital 343.67 USD (-2.97%). All three are bouncing in premarket tonight, but the real test is still ahead.
The SOX fell for eight straight days last week, its longest losing streak since 2008, and dropped more than 11% for the week. Morgan Stanley says the correction isn’t over, with support potentially another 10% to 15% lower, and expects it to last until mid-November. Bernstein sees it exactly the other way: shortages will continue through 2028.
As for where we are in the cycle, I think we’re in the middle of the uptrend in the pricing cycle. DDR5 contract prices have risen 83% since March, Micron has already committed over 75% of its 2027 capacity, and revenue was $54.23 billion in Q4 FY2026, with guidance of $61.5 billion for next quarter. The price increases and orders are real. There’s just one question left: Does the market still believe the math on AI capital spending?
Valuations need to be considered in context. Micron trades at 11.77x earnings (Finnhub, Oct. 26 data) and 9.33x EV/EBITDA (Oct. 15 data)—it looks cheap because the E in the denominator is at the peak of the pricing cycle. SanDisk is at 15.94x, and Western Digital’s forward multiple is 11.90x. Same logic: none of them look expensive when you use peak earnings.
Let’s go through them one by one. Micron has the strongest fundamentals, but its share price is below the 50-day moving average of $982.73 and above the 200-day moving average of $732.10. We’ll have to wait for earnings week to see which way it goes. SanDisk reports after the U.S. market close on Oct. 29. Its EPS guidance is $44 to $46, versus market expectations of $45.22 to $46.27. Support is at $1,208, with resistance at $1,313.78. Western Digital best captures the market mood: September-quarter revenue of $4.38 billion (+55%), EPS of $4.64, and December-quarter guidance of $5.1 billion all beat expectations, yet the stock is still down 56% from its June high. In Korean trading last Friday, Samsung closed at 215,500 won (+0.47%) and SK Hynix at 1.277 million won (+4.4%). Seagate reports Tuesday, SK Hynix Wednesday, and Samsung and SanDisk Thursday—one after another, they’ll have to show their cards.
The chart has four lines, and $SMH is right on top of the $520.53 and $514.73 moving averages.
Support: 520.53 / 514.73
Resistance: 533.34 / 558.84
Hold 514–520 → first look for 533.34, then the gap at 558.84
Break below 514 and fail to reclaim it within two days → don’t catch a falling knife; wait for the round-number level at 500
Move above 558.84 → only then will this selloff truly be over
I’m leaning bullish, but I’d scale in: the fundamentals haven’t changed, and the drop has been deep enough, but don’t go all in ahead of earnings week. I’ll admit I’m wrong if $SMH closes below $514 and can’t reclaim it for two days, or if SK Hynix’s guidance weakens on Wednesday, or if DDR5 contract prices turn down.
Are you “scaling in ahead of earnings week” or “waiting to see what SK Hynix and SanDisk report”? Pick a side in the comments.
⚠️Just my personal rambling, not investment advice.
#半导体 #美股盘前 #Storage