With a nearly $10 billion fine hanging over it, Meta delivered a quarterly report that silenced the shorts.
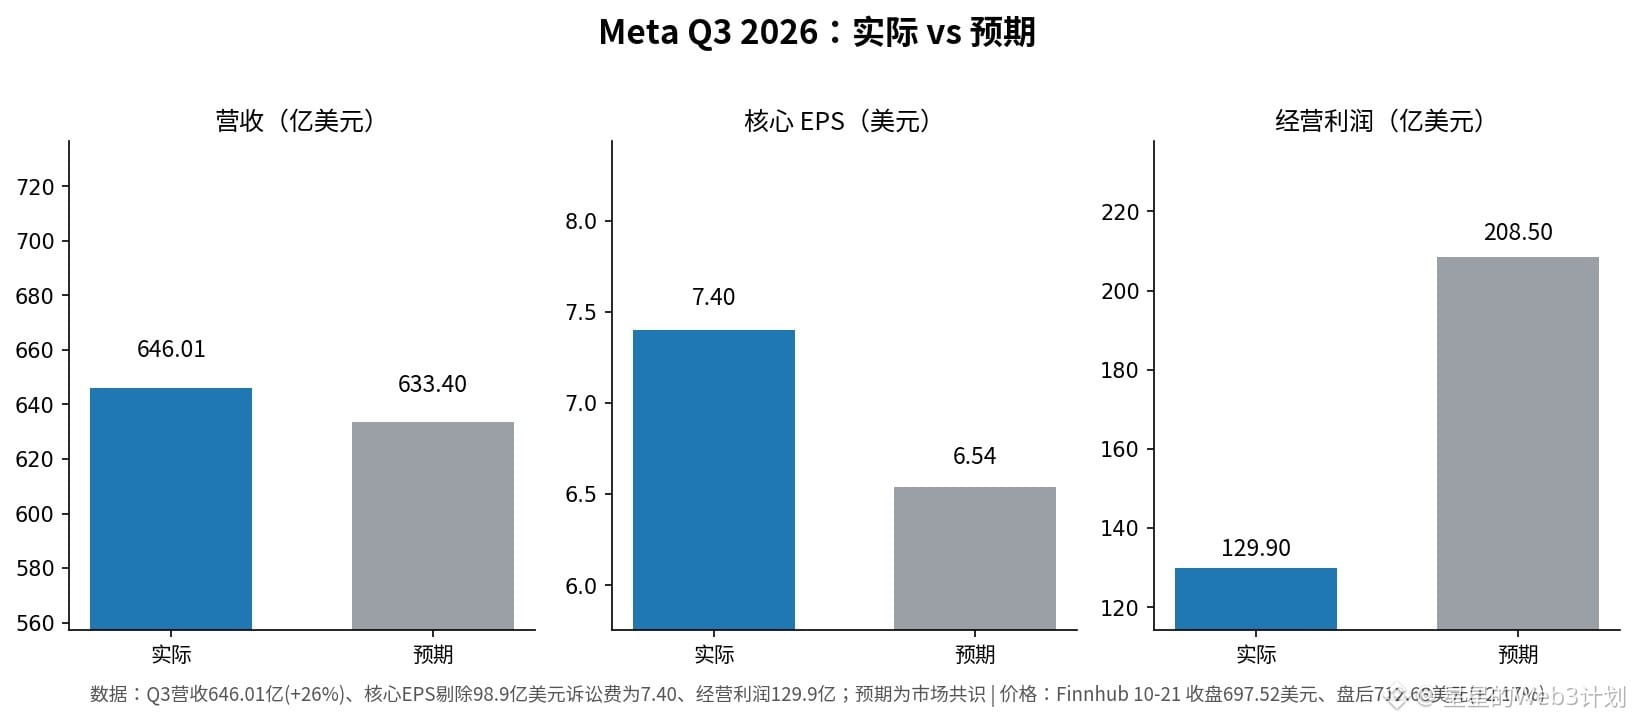
Q3 revenue was $64.601 billion, up 26% year over year and above expectations of $63.34 billion.
After absorbing a $9.89 billion settlement in the teen lawsuit, operating profit was left at just $12.99 billion, well below expectations of $20.85 billion.
Excluding the settlement, core EPS was $7.40, far exceeding expectations of $6.54.
Ad impressions rose 10%, and the average price per ad rose 14%—AI-powered precision targeting is really helping advertisers put their money to work.
Q4 revenue guidance is $73–76 billion, with the midpoint above expectations of $73.57 billion.
Zuckerberg also announced a 2-for-1 stock split effective January 2, 2027, and the issuance of non-voting Class C shares: the pie can be shared, but the voting power stays exactly where it is.
Shares briefly rose nearly 4% after hours, then pulled back to $712.68 (+2.17%) by 20:00 ET—a chance to catch its breath after five straight down days.
I’d view this rebound as a recovery for now and watch rather than chase. The invalidation points are clear: if Q4 ad growth falters, or the 2027 capital expenditure ceiling is raised again, this rebound will be a one-off.
Which narrative would you rather see continue: “core earnings + stock split,” or waiting until the 2027 spending cap is finalized before making a call?
$META $QQQ
#Meta财报 #AI Capital Expenditures
The above does not constitute investment advice. DYOR; trading involves risk.