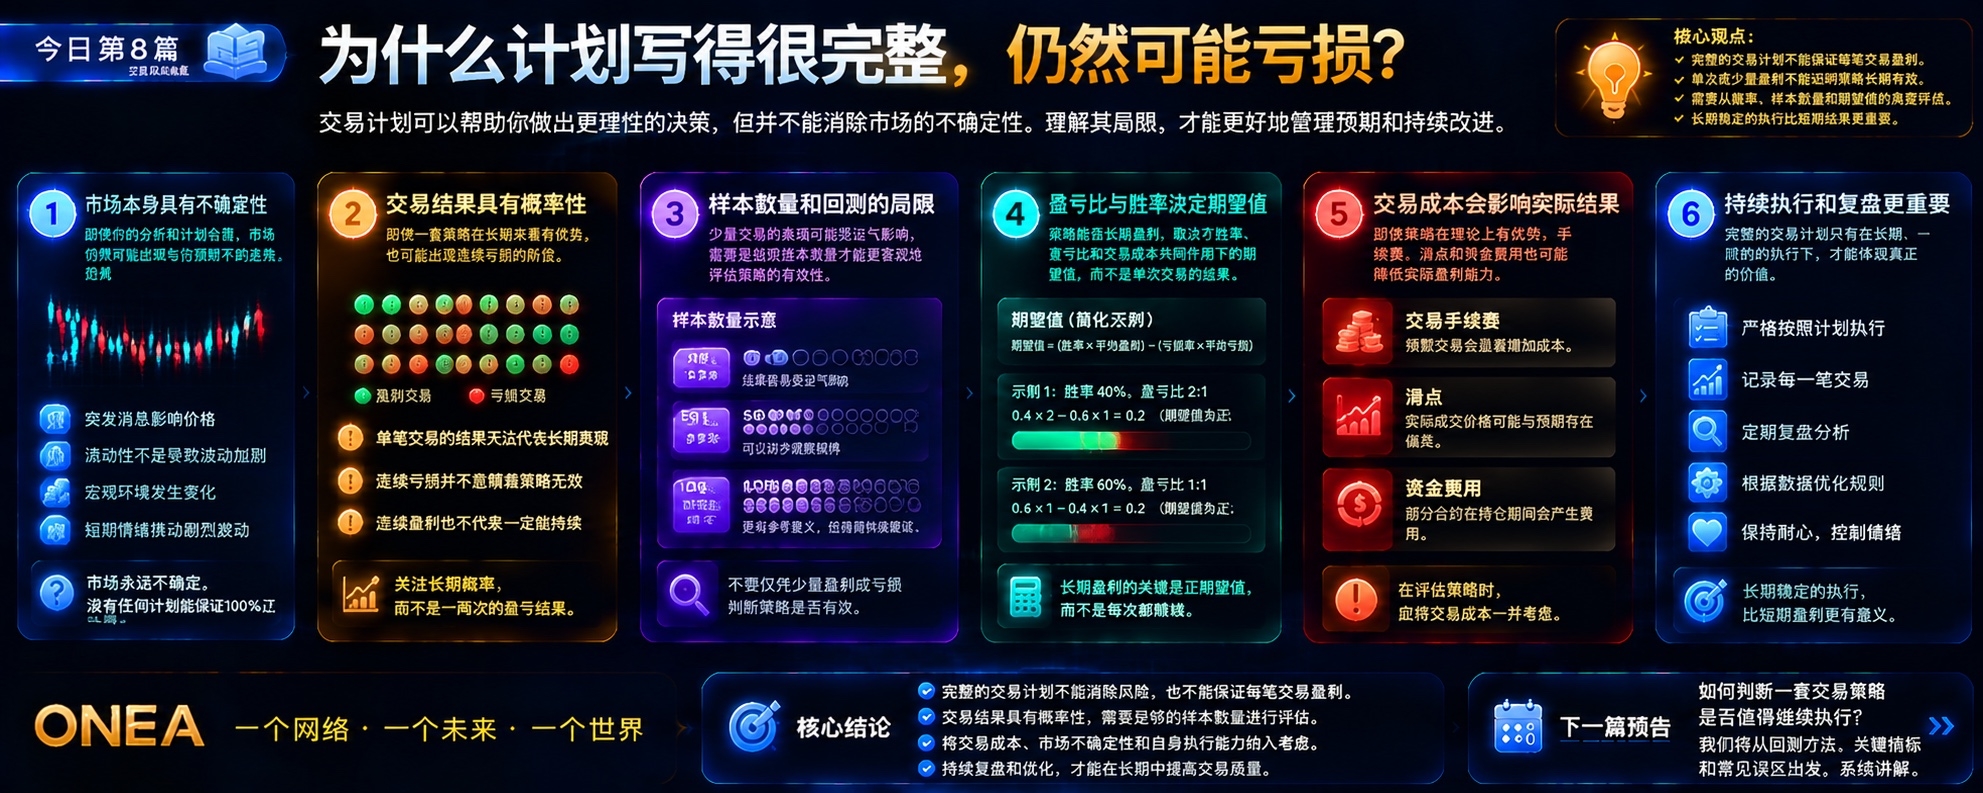
Why can a well-written plan still lead to losses? You can’t judge whether a trading strategy is effective based on just a few wins.
In the cryptocurrency market, there’s a situation that can easily lead traders to misjudge things:
A trading plan looks complete, with clear entry conditions, stop-loss levels, profit targets, and position-sizing rules. After several consecutive profitable trades, the trader begins to believe they have finally found a successful method.
But then the market changes, and trades that had been going smoothly start losing money.
At this point, some people immediately abandon their original strategy and look for a new indicator; some keep adjusting parameters in an attempt to make past market data look more perfect; and others believe that if they just stick with it for a few more trades, profits are bound to return.
So how should you determine whether a trading strategy is worth continuing to use?
This is the next question we must seriously address after creating a trading plan.
Whether a plan is complete and whether a strategy is effective are two different questions.
A plan can help you make decisions consistently, but it cannot eliminate market uncertainty. To determine whether a strategy is effective, you need to look at the performance of a series of trades, trading costs, market conditions, and execution quality—not just a few wins or losses.
I. Why Can a Complete Trading Plan Still Lose Money?
First, understand a basic fact: a trading plan is not a guarantee about the future.
Market prices are affected by many factors, including liquidity, unexpected news, macroeconomic conditions, and the behavior of market participants. Even if traders strictly follow their predefined rules, actual results may still differ from expectations.
Common reasons include the following.
1. Market conditions change
A strategy may perform well in a clearly trending market but behave differently in sideways, highly volatile, or low-liquidity conditions.
This does not mean the strategy has necessarily stopped working, nor does it mean it will inevitably return to profitability. It means you need to check whether current market conditions still match those for which the strategy was originally designed.
2. Individual trades are random
Even if a strategy has a positive expected value over the long term, that does not mean every trade should be profitable.
A few consecutive losses alone do not prove that a strategy has stopped working; likewise, a few consecutive wins do not prove that a strategy is effective.
3. Actual execution differs from the plan
The entry price in a backtest or plan may not be the actual fill price.
Slippage, fees, funding costs, unfilled orders, and temporary adjustments driven by emotions can all change the final result.
4. The original strategy logic may not have been sufficiently validated
Some trading methods may seem reasonable, but have not been tested against enough data.
If traders only select market conditions they are familiar with, or repeatedly adjust parameters until historical results improve, they can easily overestimate a strategy's actual performance.
So don't just ask, “Why did this trade lose?” Also ask: “Are the reasons behind my decision reliable? Under what conditions might these rules be effective?”
II. Don't Focus Only on Win Rate: Understand Expectancy First
Win rate is one of the most commonly watched metrics, but looking at it alone can easily lead to the wrong conclusions.
Suppose two strategies have the following characteristics:
The following is a hypothetical example for illustration only. It is not performance data for any real strategy and does not represent future results.
Metric
Strategy A
Strategy B
Win rate
40%
60%
Average profit
2R
1R
Average loss
1R
1R
Gross expectancy per trade
+0.2R
+0.2R
Here, R represents a predefined unit of risk. For example, if a trade is planned with a risk of 10 USDT, then in this simplified example, 1R represents 10 USDT.
The calculation for Strategy A is:
40% × 2R − 60% × 1R = +0.2R.
The calculation for Strategy B is:
60% × 1R − 40% × 1R = +0.2R.
As you can see, the win rates differ, but the simplified gross expectancy calculation is the same.
This shows that a higher win rate does not necessarily mean a strategy is more profitable, and a lower win rate does not necessarily mean a strategy has no value.
You also need to consider:
The ratio of average profit to average loss;
Fees, slippage, and other trading costs;
Whether actual execution matches the test conditions;
Whether the sample is sufficiently representative.
The example above is only intended to explain the mathematical relationship. It excludes trading costs and does not account for the distribution of returns, capital usage, or risk fluctuations.
III. Why Don't a Few Profitable Trades Prove a Strategy Is Effective?
Imagine that you make three trades in a row and all three are profitable.
That is certainly a satisfying experience, but what does it prove?
It only shows that those three specific trades were profitable.
It does not, by itself, prove that:
The strategy will continue to have an edge in the future;
The strategy is suitable for all market conditions;
The current parameters are better than other parameters;
The results were not due to random fluctuations;
Long-term performance will remain ideal after all costs are deducted.
When the sample size is insufficient, random factors can have a significant impact on the results.
However, note that there is no single sample-size threshold that applies to every strategy. Strategies differ in trading frequency, return distribution, market conditions, and independence of outcomes.
So don't mechanically assume that reaching a fixed number of trades will necessarily produce a reliable conclusion.
A more reasonable approach is to assess how conclusive the available evidence is, taking into account the strategy's characteristics, data quality, and statistical uncertainty.
IV. What Can Backtesting, Paper Trading, and Live Trading Each Tell You?
Determining whether a strategy is worth continuing to use cannot rely on just one type of test.
Stage 1: Historical backtesting.
Use historical data to simulate the strategy's performance according to predefined rules.
Backtesting can help you check whether the rules are clear, how frequently trades occur, what drawdowns the strategy may have experienced historically, and how it performed in different market phases.
But backtesting has limitations. For example, poor data quality, excessive parameter optimization, ignoring trading costs, or using information that was not available at the time can all make results overly optimistic.
Stage 2: Out-of-sample testing.
Set aside data that was not used to develop the strategy or adjust its parameters, and test whether the strategy maintains reasonable performance on different data.
If you repeatedly modify a strategy based on out-of-sample results and then use the same data to prove it works, that data gradually loses its value as independent validation.
Stage 3: Simulated or paper trading.
Without risking real funds, observe whether the rules can be followed within an actual trading workflow, and check the signals, order handling, and trade records.
A simulated environment may not fully reproduce liquidity, slippage, and psychological pressure in real markets, so simulated performance cannot be equated directly with live trading results.
Stage 4: Carefully evaluate live execution.
If you decide to use real funds after completing the previous stages of validation, you should still control your risk exposure and keep records of actual fills, trading costs, and execution deviations.
Good backtest performance does not mean you can conclude that live trading will produce the same results.
V. Why Can Trading Costs Change Your Conclusion About a Strategy?
Suppose a strategy has an average gross expectancy of +0.2R per trade in an idealized test.
If fees, slippage, and other costs add up to 0.25R per trade, then the simplified net expectancy is:
0.2R − 0.25R = −0.05R.
In other words, a positive gross expectancy does not guarantee a positive expectancy after costs.
This example is also a mathematical illustration only, not data from an actual strategy.
The actual costs can be affected by the instrument traded, exchange, order type, and market liquidity.
Therefore, when evaluating a strategy, pay attention to at least the following:
Fees for opening and closing positions;
The difference between actual fill prices and expected prices;
Funding costs in derivatives trading;
The impact of unfilled or partially filled orders;
The strategy's trading frequency and capital usage.
Strategies that trade at high frequency or frequently adjust positions should not ignore costs that may seem small but can recur often.
VI. What Else Should You Observe Besides Expectancy?
Expectancy is an important metric, but it cannot answer every question on its own.
Even a strategy with positive historical expectancy may involve large drawdowns, extended periods of losses, or requirements that do not suit a particular trader's financial circumstances.
It is advisable to consider the following aspects as well.
1. Maximum drawdown
Historically, how far did the account balance or strategy's net asset value fall from its peak?
Drawdowns help you understand the fluctuations in capital a strategy may experience, but the historical maximum drawdown does not guarantee an upper limit for future maximum drawdowns.
2. Consecutive losses
Check whether consecutive losses have occurred historically, and consider how they might affect your risk budget and discipline in following the strategy.
Don't conclude that a strategy has stopped working just because of consecutive losses, and don't casually change the rules out of fear of consecutive losses.
3. Performance in different market conditions
Check performance separately in trending markets, ranging markets, and other market conditions relevant to the strategy.
The goal is not to make the strategy work in every market condition, but to clarify which conditions are supported by evidence and where the evidence is insufficient.
4. Sensitivity to parameter changes
If even a small change in parameters causes a huge change in performance, the results may depend on specific historical data.
This calls for further investigation, not simply selecting the parameters with the best historical performance.
5. Execution quality
If there is a significant gap between backtest results and live trading, check factors such as fills, slippage, fees, signal handling, and discipline in following the strategy.
The strategy itself, trading execution, and money management are separate dimensions of analysis and should not be conflated.
VII. When Should You Keep Observing, and When Should You Reassess?
This may be the question traders care about most.
But the answer should be neither “stop after three losses” nor “you'll definitely make a profit if you just stick with it.”
You can establish a clear set of evaluation rules in advance.
Continue gathering evidence:
If the strategy's key conditions still hold, the available sample is not yet sufficient for a reliable conclusion, and execution has not significantly deviated from the plan, you can continue observing according to a predefined process while keeping risk under control.
Check for execution issues:
If the strategy's original rules have not changed but live trading often involves chasing prices, moving stop-losses on the fly, or excessively increasing position sizes, first distinguish execution problems from strategy problems.
Reassess the strategy logic:
If key assumptions have changed, or new data consistently shows that the strategy does not meet predefined standards, you should retest the original logic.
Pause its use:
If risk has exceeded the predefined budget, there are serious data-quality issues, or the strategy's performance clearly conflicts with its key assumptions, consider pausing rather than continuing to commit funds just to prove yourself right.
Most importantly, set evaluation criteria as far in advance as possible. Avoid lowering your standards on the fly after a loss or loosening the rules arbitrarily after a win.
VIII. Effective Strategy Validation Is an Ongoing Process
A strategy should not be checked only once during development.
A more reasonable process is:
State the strategy's assumptions → Define entry and exit rules → Historical backtesting → Out-of-sample testing → Simulation validation → Record actual execution → Review regularly → Reassess based on evidence.
Each step has its own limitations, but together they can help reduce decisions based on unvalidated assumptions.
You don't need to find a method that never loses, because no such guarantee exists.
What you really need to do is understand which conditions your method depends on, what risks it may involve, what evidence supports it, and when it should be reviewed.
Don't blindly trust a strategy after a few wins, and don't hastily dismiss all its rules after a few losses. Use data to assess it, follow rules to execute it, and protect yourself with risk management.
Three Questions for the ONEA Community
If a strategy wins five times in a row, would you consider it effective, or would you need more evidence?
Which do you usually focus on more: win rate, risk-reward ratio, maximum drawdown, or actual performance after trading costs?
If a strategy performs very well in historical backtesting but produces significantly different results in live trading, what do you think should be checked first: the strategy logic, trading costs, or the execution process?
Feel free to share your thoughts. We discuss these questions not to find a formula that guarantees profits, but to ensure that every decision is based on clearer reasoning.
Coming up next: How can you identify common pitfalls in trading strategies? We'll discuss overfitting, survivorship bias, cherry-picking success stories, and why a rule that looks perfect on a historical chart may work very differently in a real market.
Follow ONEA to keep learning about Web3, digital asset security, and risk management.
This article is for educational purposes only and does not constitute investment advice or a promise of returns. Trading digital assets involves significant risk. Please make decisions cautiously and according to your own circumstances.