

Summary: JPMorgan’s 2027 LTCMA forecasts a 10% 10-year compound return for Bitcoin, the highest of any asset, yet Bitcoin is absent from the sample portfolio allocations.
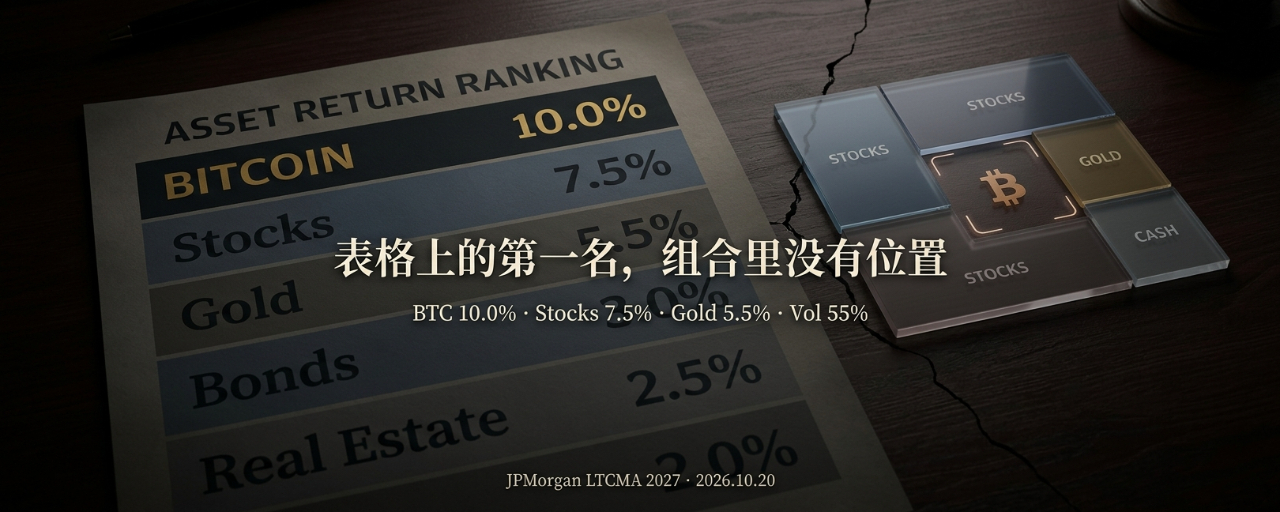
On October 19, JPMorgan Asset Management released the 31st edition of its Long-Term Capital Market Assumptions (2027 LTCMA), including Bitcoin in its long-term return forecasts for the first time. The figures are straightforward: Bitcoin’s baseline annualized compound return over the next 10 to 15 years is 10.0%, higher than the 7.5% for U.S. large-cap stocks, the 7.5% for global equities, the 5.5% for gold, and the 7.0% for a traditional 60/40 stock-bond portfolio.
In this long-term forecast covering more than 200 asset classes, Bitcoin ranks first in baseline returns.
But the details that follow make this “first place” less straightforward.
A 10% Base Case and a -11.2% Bear Case
JPMorgan didn’t give Bitcoin a single forecast figure; instead, it laid out three scenarios: a 10.0% base case, a 16.6% bull case, and a -11.2% bear case.
Bitcoin’s “first place” in base-case returns comes from its compound return. In the same matrix, Bitcoin has an arithmetic average annualized return of 20.9% and annualized volatility of 55.0%. For comparison, volatility is about 18% for U.S. large-cap stocks and 17.2% for gold. Bitcoin’s expected volatility is more than three times that of U.S. large-cap stocks.
That 10% compound return comes at the cost of 55% volatility. The same long-term upward trajectory has been far more volatile for Bitcoin than for stocks and gold.
The -11.2% bear-case figure is particularly noteworthy. This isn’t the personal view of some pessimistic analyst; it’s the downside scenario JPMorgan assigns to Bitcoin within its long-term capital market assumptions framework. Over a time horizon of more than 10 years, a negative annualized return means that, in an extreme scenario, Bitcoin would not only underperform cash but also suffer a substantial loss of purchasing power.
The Highest Return, Yet No Portfolio Allocation
What makes this report worth reading closely isn’t the 10% figure itself, but the restraint JPMorgan shows in handling it.
Bitcoin was not included in the main covariance matrix. The report explains that Bitcoin’s historical correlations with other assets are unstable and its volatility is extremely high, so it was handled in a simplified, separate version.
The covariance matrix is a core LTCMA tool, used to calculate the overall risk and return of different assets combined in a portfolio. Placing an asset in a separate matrix means its risk can’t be integrated with other assets under the standard framework. In other words, JPMorgan’s model can’t reliably answer the question, “How would adding Bitcoin to a 60/40 portfolio change its risk-return profile?”
The more important point comes next. Although Bitcoin appears in the return forecast table, it is not included in the report’s sample portfolio allocations. The report recommends that investors use a 30% allocation to alternative assets to raise the 60/40 portfolio’s return to 7.5% and improve its Sharpe ratio by 21%, but Bitcoin is not among those alternative assets.
Bitcoin received the highest expected return, but no allocation weight. That isn’t a contradiction. JPMorgan is saying that Bitcoin’s long-term return can be estimated, but its role in a portfolio can’t be priced using the existing framework.
This approach is more thought-provoking than simply being bullish or bearish. JPMorgan acknowledges that Bitcoin’s expected return is higher than that of all traditional assets, yet declines to place it within the standard asset allocation framework. Acknowledging its returns is one thing; recommending that investors hold it is another.
Long-Term Return Forecasts—and What They Can’t Measure
The LTCMA is a report designed to provide an anchor for strategic asset allocation. Its value lies not in making precise predictions, but in offering a framework for comparing long-term returns. Using the same methodology to estimate returns for Bitcoin, stocks, bonds, and gold is itself a statement: Bitcoin is no longer being treated as an outlier beyond the asset allocation system.
But the reliability of that 10% figure needs to be considered in light of Bitcoin’s history. Bitcoin has existed for less than twenty years, and it has experienced only a handful of full cycles. Using its limited price history to derive compound returns over a period of more than 10 years produces a statistical confidence interval far wider than those for stocks or bonds. JPMorgan’s -11.2% bear-case figure effectively acknowledges this uncertainty: under different assumptions, the same model can produce results pointing in completely opposite directions.
This is fundamentally different from long-term forecasts for traditional assets. The 7.5% forecast for U.S. large-cap stocks is based on more than a century of earnings, dividends, and valuation data, so the range of possible outcomes is relatively narrow. Bitcoin’s 10% forecast is based on a much shorter history with less stable correlations, and Bitcoin is placed in a separate, simplified matrix. The “10%” and “7.5%” figures do not have the same confidence level.
Traditional Institutions’ Approach to Valuation Has Changed
Beyond the figures themselves, this report sends a quieter but more important signal: Bitcoin’s inclusion in the LTCMA means that traditional asset managers have changed how they value Bitcoin.
Until now, traditional institutions have generally taken one of two approaches to Bitcoin: some have rejected it outright, viewing it as an asset class that can’t be analyzed; others have traded it tactically through instruments such as futures and ETFs, without including it in their long-term allocation frameworks. The LTCMA takes a third path: it estimates Bitcoin’s long-term returns using the same methodology as for stocks and bonds, while isolating it in a separate matrix rather than pretending its risks can be absorbed by existing models.
Bitwise Chief Investment Officer Matt Hougan commented that JPMorgan’s ranking of Bitcoin as the best-performing asset expected over the next decade marks a shift in traditional financial institutions’ attitudes toward cryptocurrency. But the direction of that shift isn’t “buy Bitcoin”; it’s “Bitcoin can no longer be ignored.”
What to Watch Next
Whether future versions change how the matrix is handled: If JPMorgan moves Bitcoin from a separate matrix into the main matrix in a future LTCMA, that would mean it considers Bitcoin’s correlation structure stable enough to be included in standard portfolio optimization.
Whether Bitcoin receives an allocation in sample portfolios: The gap between return forecasts and allocation recommendations is a more honest indicator of traditional institutions’ true position.
How other institutions respond: Whether BlackRock, Vanguard, Goldman Sachs, and others follow suit by including Bitcoin in their long-term assumptions reports will determine whether this is an isolated move by JPMorgan or an industry-wide shift.
Changes in volatility assumptions: If the 55% volatility assumption declines over time, Bitcoin will become more viable in portfolio optimization. If it remains high, Bitcoin’s place in the LTCMA will remain that of a “separate entry” rather than an “allocation option.”
Two Sides of the Same Table
JPMorgan’s 10% figure for Bitcoin is a formal valuation of Bitcoin using traditional financial methodology. But that valuation comes with a string of caveats: a separate matrix, exclusion from portfolios, 55% volatility, and a negative bear-case scenario.
These caveats matter just as much as the 10%. They show that traditional institutions are now willing to include Bitcoin in asset comparison tables, but aren’t yet ready to include it in client portfolios. The gap between coming first in a table and receiving a portfolio allocation isn’t a difference in returns—it’s a question of whether the risk framework can accommodate an asset.