


Wall Street banking giant JPMorgan is bringing its bank deposit token to the Ethereum mainnet!
Kinexys, JPMorgan’s blockchain division, announced on the 19th that its US dollar deposit token, JPM Coin (JPMD), has officially expanded to Ethereum Layer 1, allowing eligible institutional clients to transfer and settle funds directly on a public blockchain. JPMorgan said Ethereum’s deep on-chain liquidity and tokenized asset ecosystem were key reasons for choosing the Ethereum mainnet.
JPM Coin Expands from Base to Ethereum Mainnet—What Does JPMorgan See in It?
JPM Coin first officially launched on Base, the Ethereum Layer 2 network developed by Coinbase, in November 2025. B2C2, Coinbase, and Mastercard had already completed test transactions at the time. Now, JPMD is expanding to the Ethereum mainnet, meaning JPMorgan is no longer relying solely on Layer 2 networks and is bringing its institutional payment tool directly to Ethereum’s primary settlement layer.
“Tokenized financial infrastructure is no longer just a concept on paper; it is reshaping liquidity, settlement, and digital asset workflows,” said Emma Landriault, Global Head of Kinexys Labs. “Following the launch of JPM Coin on Base, we are now expanding it to Ethereum. This important step is intended to give our institutional clients a multichain option, enabling them to move large sums of money between Web3 and traditional financial ecosystems.”
According to the official statement, Ethereum was chosen primarily for its mature on-chain liquidity, tokenized assets, and the counterparty and settlement infrastructure already used by financial institutions.
For institutions holding tokenized funds or other real-world asset (RWA) tokens, completing both cash and asset settlement on the same chain could reduce the operational complexity of transfers and settlement across systems.
JPMD Is Not USDC! What’s the Difference Between a “Bank Deposit Token” and a “Stablecoin”?
Notably, JPMorgan Chase does not position JPMD as a traditional dollar stablecoin, but as a tokenized deposit. Both can represent dollar value on a blockchain, but they have different legal characteristics.
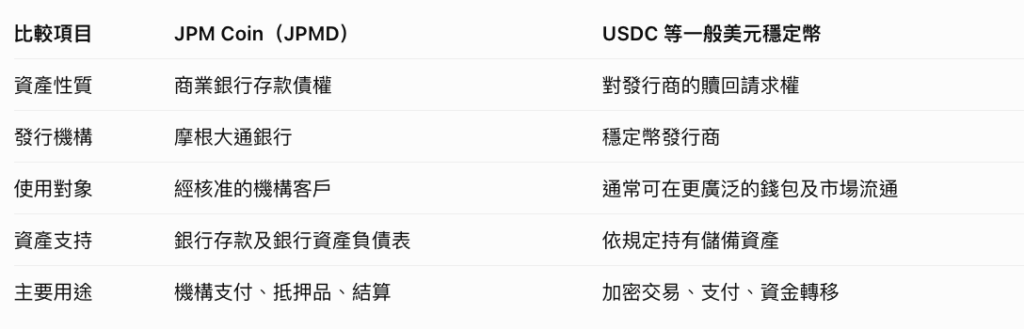
JPMorgan Chase says deposit tokens can extend the regulatory and credit framework of traditional bank deposits while combining it with the around-the-clock settlement capabilities of blockchain. Some eligible deposit tokens may also pay interest, but that does not mean all JPMD holders automatically earn interest or receive deposit insurance coverage.
Kinexys Surpasses $4 Trillion in Cumulative Transactions, Processing $7 Billion Daily
Another important figure in JPMorgan Chase’s announcement was the scale of its Kinexys blockchain platform. According to the company, Kinexys has processed more than $4 trillion in transactions since its launch and currently handles an average of about $7 billion in daily transaction volume.
This reflects the considerable scale of JPMorgan Chase’s blockchain financial infrastructure business.
As of publication, JPMorgan Chase had not disclosed the actual transaction volume, number of active institutions, or total circulating supply of JPMD on Ethereum mainnet. On the 19th, third parties tracked the deployment of the JPMD contract on Ethereum, but its total supply was still shown as zero at some points during the day. This means that the official announcement of a product launch does not necessarily mean that large amounts of bank funds have already been migrated.
JPMorgan Chase Has Long Been Building on Ethereum, with Tokenized Funds as a Key Piece of the Puzzle
JPMorgan Chase’s choice of Ethereum is not its first use of the public blockchain.
In May 2026, JPMorgan Chase’s asset management division launched its second tokenized money market fund, JLTXX, on Ethereum, committing $100 million of its own capital at launch to expand its institutional-grade on-chain asset management business. This is gradually bringing JPMorgan Chase’s on-chain strategy together into a more complete financial architecture: tokenized funds provide investable on-chain assets, while JPM Coin offers payment and settlement tools in the form of bank deposits.
In the future, institutions could use JPMD to pay for tokenized assets, transfer collateral, or even automate corporate treasury management workflows through smart contracts. However, whether these functions can achieve widespread adoption will depend on institutional participation, cross-chain operating costs, regulatory requirements, and actual market liquidity.
JPMorgan Chase’s choice of Ethereum is symbolically significant for its institutional financial ecosystem. Transactions on Ethereum mainnet require ETH to pay network fees, but actual demand will depend on JPMD’s transaction frequency, transaction size, and settlement methods. There is currently insufficient data to quantify how much additional demand JPMD will generate for ETH.
For Ethereum, the greatest significance of this partnership is that traditional financial institutions are beginning to view public blockchains as financial infrastructure where dollar funds and tokenized assets can be deployed in practice—not merely as platforms for cryptocurrency trading.
“JPMorgan Chase’s JPM Coin Officially Launches on Ethereum Mainnet! Kinexys Processes $7 Billion Daily—Why Did Wall Street Choose Ethereum?” was first published on Blockcast.