

Summary: BlackRock files for a third bitcoin ETF, linked to IBIT, that offers downside protection but caps gains; the level of protection is not fixed and principal is not guaranteed.
On October 19, BlackRock filed a registration statement with the U.S. Securities and Exchange Commission for the iShares Bitcoin Managed Protection ETF, with the proposed ticker PBIT. This would be BlackRock’s third bitcoin ETF. The first two were the spot ETF IBIT, launched in January 2024, and the options income ETF BITA, launched this June.
The filing describes the product cautiously: it seeks to capture upside returns from IBIT and similar bitcoin exposure while also seeking to provide some degree of downside protection. The key words are “some degree” and “seeks.”
A three-part structure: protection is purchased
PBIT’s strategy is built from three components.
The first component is buying Bitcoin options, typically executed in three tranches. The second is selling options, using the premiums received to offset the cost of the options purchased, at the expense of capping upside. The third is investing in fixed-income products, using interest income to offset option costs and provide an additional cushion to fund downside protection.
The structure itself is nothing new. Covered calls, protective puts, and collar strategies have been used in traditional options markets for decades. What is new about PBIT is packaging these tools into an ETF, allowing investors who do not want to trade options directly to buy Bitcoin exposure with a built-in partial hedge through a brokerage account.
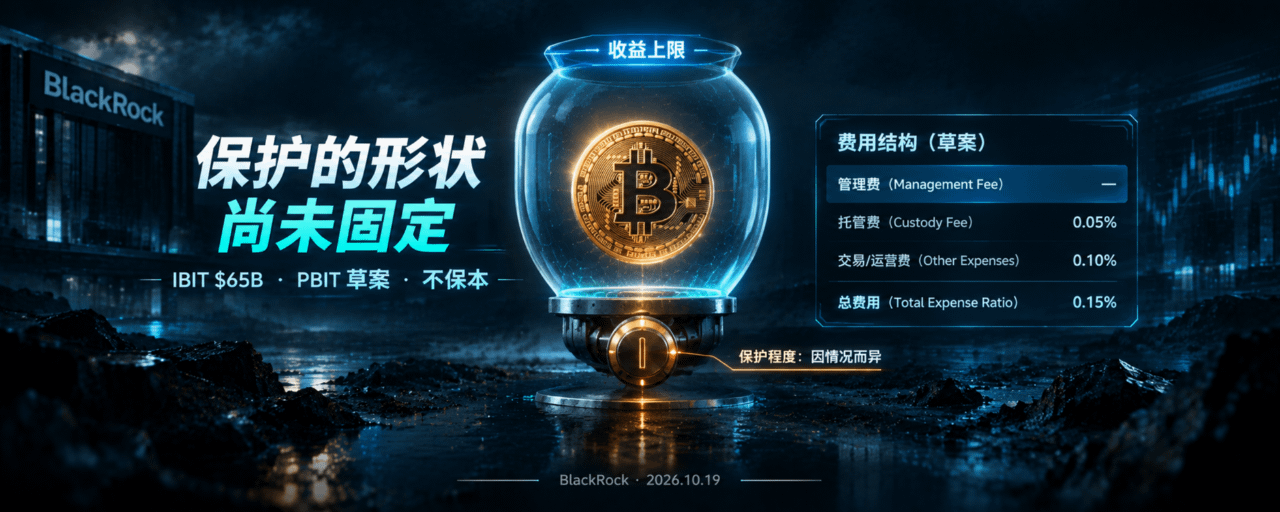
But one detail is worth noting: the filing leaves the management fee blank, describes the level of protection as “depending on the circumstances,” and explicitly states that the strategy does not guarantee protection against losses. This means the product’s final pricing and terms still depend on SEC review and BlackRock’s subsequent disclosures. What investors see now is a framework, not a complete contract.
How it differs from Calamos: certainty vs. flexibility
Bitcoin buffer ETF precedents already exist in the market, with Calamos’s Protected Bitcoin ETF series as the most direct comparison.
Calamos’s product lineup makes the trade-off between protection and upside caps very clear: CBOO, with 100% protection, has an upside cap of just 8.32%; CBXO, with 90% protection, has a cap of 20.55%; and CBTO, with 80% protection, has a cap of 36.22%. Investors know before buying how much upside they are giving up in exchange for downside protection.
PBIT does not specify such fixed ratios. The initial downside buffer for a single options tranche is designed to be about 10%, but the fund as a whole has no fixed loss limit and does not guarantee principal protection. Protection is “to a certain extent,” the cap is “approximately” defined, and the ultimate risk-return balance depends on how BlackRock executes in the options market.
Calamos sells insurance at a known price; BlackRock sells an adjustable mechanism. The former is transparent, the latter flexible. Institutions often need the latter—not a fixed protection ratio, but a tool that can adjust risk exposure in response to market conditions and client needs.
This flexibility appeals to wealth management firms. Financial advisors work with clients who have varying risk appetites, and a product with an adjustable protection level is easier to fit into different portfolios than one locked into 80% or 100% protection. For investors, however, flexibility also means greater uncertainty about the terms.
IBIT’s $65 billion base and BlackRock’s product lineup
PBIT is not a standalone product; it stands on the shoulders of IBIT.
IBIT has more than $65 billion in assets under management, making it the largest Bitcoin ETF. BITA, launched this June, generates monthly income by selling call options on IBIT, targeting an annualized yield of 15% to 25% at the cost of giving up some upside.
Together, the three products form a clear hierarchy in BlackRock’s Bitcoin ETF lineup: IBIT provides pure spot exposure for investors willing to accept full volatility in pursuit of the full upside; BITA offers capped upside plus option premium income for investors seeking cash flow in a choppy market; and PBIT offers capped upside plus partial downside protection for traditional investors who want Bitcoin exposure but are sensitive to drawdowns.
The logic of this lineup is not to make Bitcoin “safer,” but to make its risks divisible, priceable, and sellable. The same underlying asset is split into different risk-return slices and sold to investors with different risk appetites.
Bloomberg Intelligence analyst James Seyffart noted that this is BlackRock’s third Bitcoin ETF filing. Its product lineup currently covers only Bitcoin and Ethereum, with no ETF offerings for other crypto assets such as XRP and SOL. This restraint is noteworthy in itself: BlackRock is deepening its Bitcoin product lineup rather than broadening its crypto-asset coverage. It is betting on institutional demand for Bitcoin as an asset class, not speculative demand for a range of tokens.
The cost of protection isn’t on the fee schedule
PBIT’s filing does not specify a management fee, but the cost of protection has never been limited to fees.
One cost is capped upside. The options sold lock in a ceiling on returns. If Bitcoin posts gains like the 30%-plus surges seen in some historical weeks during the holding period, PBIT investors will receive only the portion below the cap. Protection is not a free lunch: it trades away some potential gains in exchange for a buffer against losses.
A second cost is uncertainty about the protection. Calamos investors know when they buy that they are getting 80% protection; PBIT investors can only know that they are getting protection “to a certain extent.” This wording gives BlackRock room to maneuver, but leaves investors with a variable they must assess for themselves: the amount of protection depends on option strike prices, the term structure, and market volatility.
A third cost is complexity. The three-part structure—long options, short options, and fixed income—means the product’s actual performance depends on the interaction of multiple variables, rather than simply tracking the price of Bitcoin. Investors accustomed to IBIT’s linear exposure will need to rethink how PBIT’s return profile works.
What to watch next
PBIT’s supplemental disclosures: the management fee, specific option strike ranges, and the method for calculating the protection level will be clarified in subsequent amended filings. These terms will determine the product’s actual value for money.
The SEC’s review timeline: the regulatory framework for crypto ETF options is still evolving. The SEC recently delayed some decisions on crypto ETF options until November 11, which may affect PBIT’s approval timeline.
Market reception for comparable products: Calamos’s buffer ETFs have been operating for some time. Changes in their assets under management and fund flows can offer a reference point for gauging potential demand for PBIT.
Liquidity in IBIT options: PBIT’s strategy depends on the depth and pricing efficiency of IBIT options. Open interest in IBIT options has exceeded $27.6 billion, so a liquidity base exists, but execution costs remain to be seen.
The shape of protection
BlackRock is not trying to eliminate Bitcoin’s volatility. It is slicing that volatility into pieces, assigning each a price, and putting them on the shelf. PBIT is the latest offering on that shelf, labeled “protection”—but the shape of that protection has yet to be defined.
For investors who want exposure to Bitcoin but fear drawdowns, this ETF offers an entry point. The cost of entry is partly written into a future fee schedule, but a larger part is hidden in capped upside and phrases like “to a certain extent,” “approximately,” and “depending on the circumstances.”