What to watch next week (Oct 19–25): Fed blackout, a macro data vacuum; markets take their cues from earnings and breaking news
【Scheduled events, Beijing time】
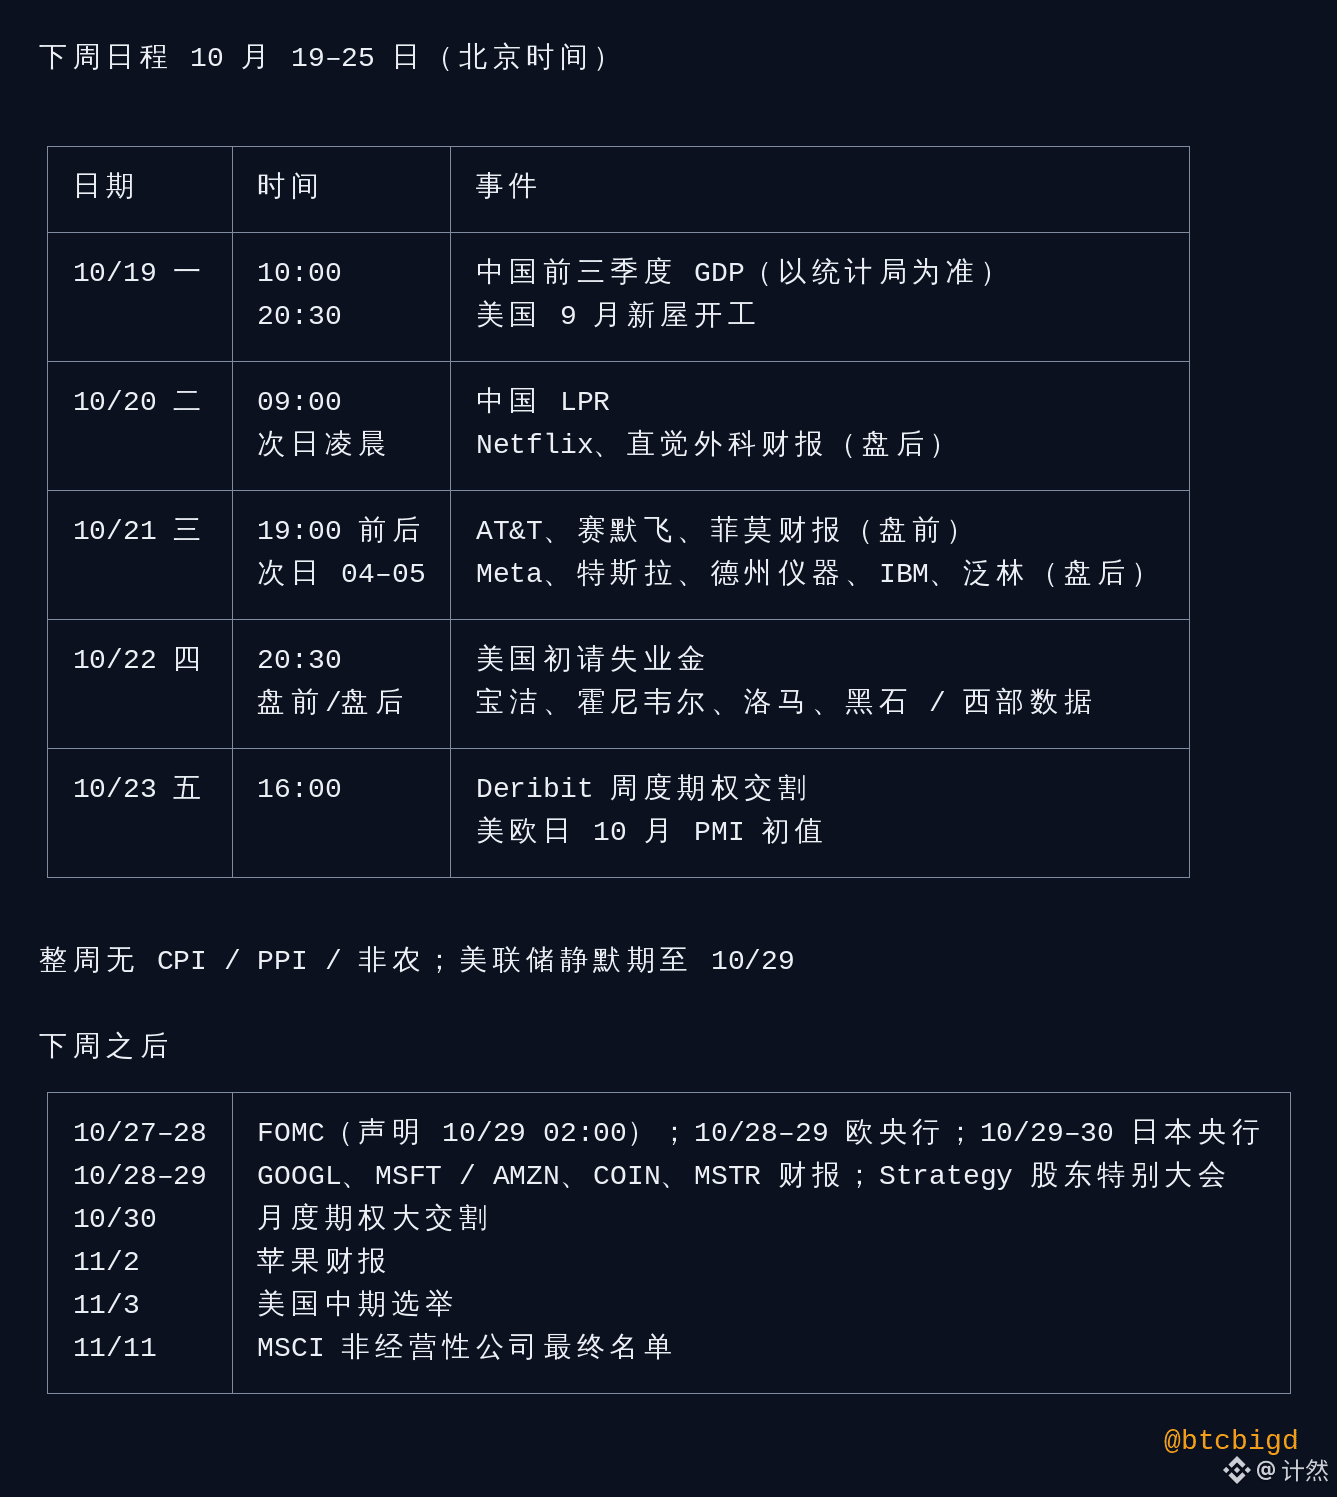
- Mon, 10/19, 10:00: China’s Q1–Q3 GDP (in past years, it has been released on the 19th or 20th; check the National Bureau of Statistics); 20:30: U.S. September housing starts
- Tue, 10/20, 09:00: China’s LPR; Netflix earnings after the close (early morning on the 21st in Beijing)
- Wed, 10/21: AT&T before the open; Meta, Tesla, Texas Instruments, IBM, and Lam Research (semiconductor equipment) after the close—all at 04:00–05:00 on the 22nd in Beijing. This is the biggest night of the week
- Thu, 10/22, 20:30: U.S. initial jobless claims; Procter & Gamble, Honeywell, Lockheed Martin, and Blackstone before the open; Western Digital (storage) after the close
- Fri, 10/23, 16:00: Deribit weekly options expiry; preliminary October PMIs for the U.S., euro area, and Japan
- No CPI, PPI, or payrolls-level data all week; the Fed enters its pre-meeting blackout period on 10/17, with no official remarks through 10/29
【Coming after next week】
- FOMC meeting, 10/27–28; statement at 02:00 on 10/29. ECB meeting, 10/28–29; Bank of Japan meeting, 10/29–30
- GOOGL and MSFT earnings on 10/28; AMZN, COIN, and MSTR on 10/29; Apple on 11/2
- Strategy special shareholder meeting on 10/28; monthly options mega-expiry on 10/30; MSCI’s final list of non-operating companies on 11/11
- U.S. midterm elections on 11/3
【Three things to watch in earnings】
- Meta’s capex guidance: the AI chain sold off this week on fears of “borrowing money to build capacity.” Whether the giants are willing to keep ramping up investment will provide the first answer
- What Lam Research and Western Digital say about storage demand: storage stocks were among the hardest hit this week. Earnings could either stop the bleeding or trigger another leg down
- Tesla will make headlines, but it won’t have much impact on AI-chain pricing
【Unscheduled powder kegs】
- Asian stocks at Monday’s open: U.S. AI stocks fell on Friday, and storage-stock and Korean-stock contracts on Binance plunged 7–9% early Saturday morning. The KOSPI, Samsung, and SK Hynix have yet to reflect this
- Strait of Hormuz: reports say a tanker hit a mine over the weekend, and Iran says the strait is closed. Brent is at 109.69; a move above 110 would bring the inflation narrative back
- AI credit: CoreWeave is down 51% from its high, and high-yield bond spreads widened 14 bp in three days. If another neocloud or storage company runs into financing trouble, this week’s sell-off could happen all over again
- U.S.–China: export controls and the ChangXin DRAM story could produce news at any time
【Crypto’s own position】
$BTC has closed below the bottom of its range at 82,563 for four straight days. The October 15 low of 79,732 has not been breached. Funding rates have been positive for seven consecutive periods, with longs paying to wait for a rebound. In a macro data vacuum week, keep an eye on Korean stocks during the day and Meta’s earnings that night.
Which one worries you most next week?