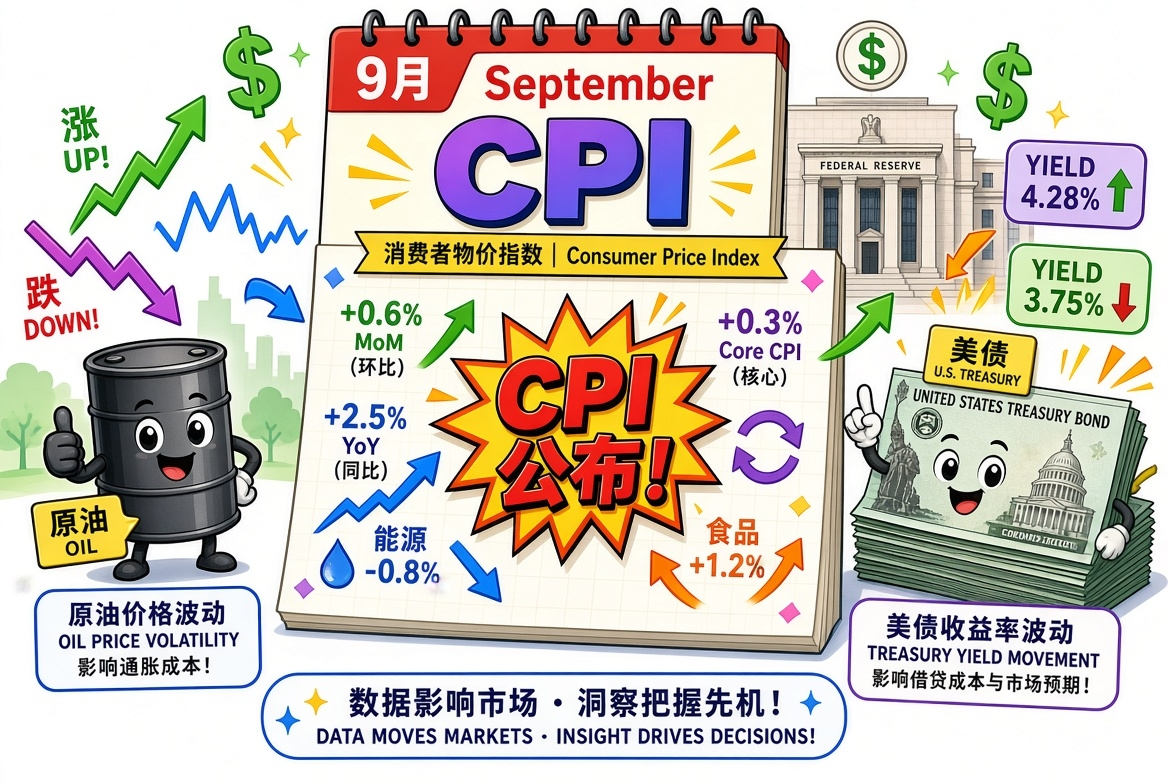

September CPI (due at 8:30 a.m. ET on October 14) is the last major inflation report before the Fed’s October 27–28 meeting. The market generally expects headline inflation to rise on a rebound in energy prices, while core inflation is expected to remain relatively moderate. The impact on crude oil and U.S. Treasuries will depend mainly on how the data compare with expectations, especially core CPI.
Market consensus expectations (compiled from multiple sources)
Headline CPI: approximately +0.5% to +0.6% month over month (previous: +0.4%), and approximately 3.6% to 3.7% year over year (previous: 3.4%).
Core CPI (excluding food and energy): approximately +0.2% month over month (previous: +0.3%), and approximately 2.4% to 2.5% year over year (previous: 2.4%).
Energy is the main driver. Gasoline prices rose sharply in September (some analyses point to a month-over-month increase of nearly +9% to +10%), making a significant contribution to the energy component. This was mainly due to higher oil prices amid the Middle East situation, risks around the Strait of Hormuz, and U.S.-Iran-related conflict. Core inflation is expected to ease, as rents and housing services have softened, while pressures from services and goods remain relatively contained. Some institutions (such as Goldman Sachs) have a slightly more hawkish view, with headline inflation at 3.7% year over year and core inflation month over month slightly above consensus.
Current backdrop: The Fed has raised rates once in September (target range now 3.75%–4.00%). Markets are pricing in a low probability of a rate hike in October (around 15%–20%), with more attention on December and beyond. The 10-year Treasury yield has recently been around 5.2% (approximately 5.21%–5.24% around October 13). WTI is around $94 a barrel and Brent around $105 (elevated, but somewhat off its highs).
Potential impact on crude oil price movements
Crude oil itself is a key driver of the energy component of CPI, not simply an “outcome.” After the data is released:
In line with or slightly above expectations (headline inflation runs hot, with a large energy contribution): This may reinforce the “sticky inflation” narrative in the short term, supporting oil prices at elevated levels or prompting a modest rebound, especially if markets interpret it as a sign that supply risks persist. However, if core inflation is moderate, oil prices are more likely to be driven by geopolitical developments (energy-related issues in the Middle East/Russia-Ukraine) and actual supply and demand, rather than CPI itself.
A much hotter-than-expected reading could stoke concerns about further tightening, indirectly weighing on oil by dampening demand expectations. Conversely, if core inflation is markedly softer, markets may focus more on the temporary nature of the energy shock, with oil price movements returning more to fundamentals.
Overall, the direction of oil prices after the CPI release will still depend heavily on geopolitical developments (such as diesel supply and ceasefire-related news), rather than on a single data point. Oil prices and Treasury yields have recently shown some positive correlation (through the inflation-concern channel).
Potential impact on U.S. Treasuries (yields)
Treasuries are more sensitive to core CPI; energy-related noise in headline CPI is relatively secondary:
Core inflation in line with expectations or softer (month over month ≤0.2%): This would reinforce expectations that there will be no rate hike in October, leaving room for short-term (2-year) yields to fall. Long-term yields (10- and 30-year) may also decline or consolidate at elevated levels, especially if oil prices remain stable. This would benefit the bond market (prices rise and yields fall).
Core inflation hotter than expected (month over month ≥0.3%): This could revive expectations of rate hikes or tighter policy, with a more pronounced rise in short-term yields. Long-term yields could also be pushed higher by inflation expectations and the term premium, prolonging pressure at elevated levels (they have recently approached multi-year highs).
Headline inflation hot but core inflation cool: A classic “scissors” scenario. The bond market reaction could be mixed—short-term yields may benefit from a more accommodative policy outlook, while long-term yields may remain resilient due to energy-inflation concerns. Markets have already partly priced in an energy-driven rise in headline inflation; the real surprise lies in the core components and subsequent pass-through.
Scenario summary:
Baseline (headline inflation rising due to energy, core inflation moderate): Crude oil fluctuates at elevated levels; short-term Treasury yields ease somewhat, while long-term yields fluctuate at elevated levels.
Hotter-than-expected surprise: Increased upward pressure as oil prices and yields rise in tandem.
Cooler-than-expected surprise: Oil prices may come under pressure, while Treasury yields fall significantly.
After the data is released, watch the details (gasoline, housing, services, and goods components) and subsequent comments from Fed officials. Market volatility could be significant, especially around the open. This analysis is based on current consensus; actual movements will be affected by real-time data, geopolitics, and risk appetite, and it is not investment advice.