

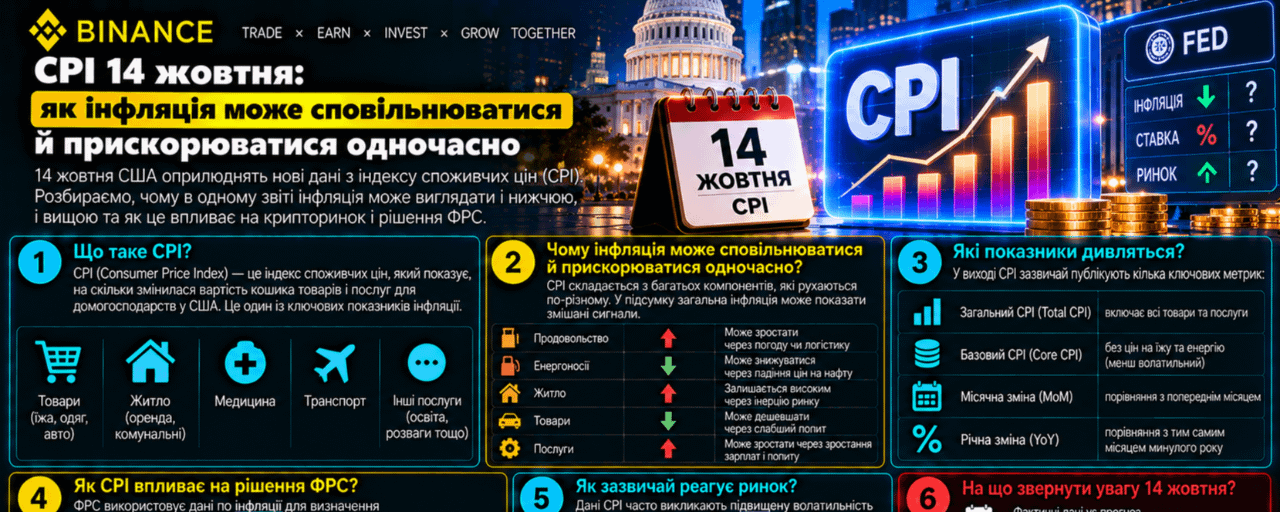
Imagine: A post appears in the feed: “Core inflation has declined.” A minute later, another author writes: “Price pressures have intensified.” Both could be correctly interpreting the same report. One is comparing prices with a year earlier, the other with the previous month. The mistake begins when either of these sentences is turned into a ready-made command to buy bitcoin.
This has already happened at the statistical level. In the BLS report for August 2026, core CPI, excluding food and energy, rose 2.4% year over year after 2.5% in July. At the same time, its seasonally adjusted monthly increase accelerated from 0.2% to 0.3%. Headline CPI added 0.4% over the month after 0.1%, while the annual rate remained 3.4%. The report was published on September 11; these figures describe August.
The next report, for September, is scheduled for October 14 at 08:30 U.S. Eastern Time. For Kyiv, that day it is 15:30, UTC+3. So today we can check the previous data and prepare a way to read the new release, but its result is still unknown.
Sources were checked on October 12, 2026 at 09:03 Kyiv time. This is an analysis of macroeconomic statistics for a crypto-market reader, without a BTC or ETH trading forecast. Current quotes and technical levels are not used: the conclusions concern CPI interpretation. All hypothetical indexes, expectations, and amounts in the examples below are hypothetical, not a forecast of September data.
My main thesis: before reacting to an inflation headline, you need to determine what exactly changed — the price level, the speed of its increase, or the gap between the result and expectations. These are three different quantities. They can move in different directions, and they matter together for a decision.
Let’s start with the level. Imagine a hypothetical basket of goods and services that cost $10,000, and a year later cost $10,340. Inflation is 3.4%. If over the next year the basket’s price rises by another 2.4%, it will cost $10,588.16: 10,340 × 1.024. Inflation slowed by one percentage point, but the basket became $248.16 more expensive.
A slowdown in the pace of price increases is called disinflation. A fall in the price level itself is deflation. For a holder of dollar balances, the difference matters: slower price growth still reduces the quantity of goods that can be bought with an unchanged amount. For a trader, something else matters: a headline about lower inflation does not by itself say that economic conditions have already returned to their previous state.
Now for the speed. The monthly figure compares the index with the previous month. The annual figure compares it with the same month last year. The formula is the same in both cases: divide the new value by the previous one, subtract one, and multiply by 100%. The denominator is what differs. BLS separately reminds readers that January and December of the same year give an eleven-month change, not a full twelve months.
It is the denominator that creates the base effect. The annual rate depends both on today’s price level and on what it was a year ago. When a high base from last year enters the comparison, annual growth can fall even after a noticeable new increase. An old strong month drops out of the twelve-month window, and a newer weaker one takes its place.
Here is a hypothetical example on one consistent index series, without mixing seasonally adjusted and unadjusted values. In August last year, the index was 100; in September, 100.6. In August this year, it is 103.4. Annual inflation in August is 3.4%: 103.4 / 100 − 1.
If the new September index adds 0.4%, it rises to 103.8136: 103.4 × 1.004. Annual inflation then becomes about 3.19%: (103.8136 / 100.6 − 1) × 100%. We have fresh 0.4% price growth and, at the same time, a decline in the annual pace by about 0.21 percentage points. There is no arithmetic contradiction.
The same mechanism works in reverse. Keep the current index at 103.8136, but suppose last September had been weaker: 100.1 instead of 100.6. The year-over-year increase is now about 3.71%. The new month in the two models is exactly the same. The difference between the headlines “inflation slowed” and “inflation accelerated” was created by last year’s base.
This is not a reconstruction of the actual U.S. September figure. I am deliberately using round hypothetical values to separate the mechanism from forecasting. The practical value of the example is learning to ask: what part of the change in the annual figure comes from new prices, and what part comes from old observations dropping out of the calculation?
For the same series, this can be written even more precisely: the new annual multiplier equals the previous annual multiplier multiplied by the new monthly multiplier and divided by last year’s monthly multiplier. In the first model we get 1.034 × 1.004 / 1.006 = 1.031944. After subtracting one, we get the same approximately 3.19%.
But there is a trap for the careful reader here. In BLS headlines, monthly changes are usually presented with seasonal adjustment, while annual changes are not. You cannot mechanically plug these different series into one formula and expect an exact match. For identity, comparable indexes are needed. Seasonal adjustment helps remove recurring calendar fluctuations and assess short-term dynamics.
The second trap is rounding. On screen you see 0.2% or 0.3%, even though the index contains more digits. Two months with the same rounded reading can have different actual increases. Multiplying rounded monthly rates gives an approximation, not a guaranteed reproduction of the published annual result. A more accurate calculation can be made from the index values themselves using the BLS formula.
The third trap appears when a monthly number is converted into an annual one. Hypothetical growth of 0.3% per month over twelve months gives about 3.66%: (1.003¹² − 1) × 100%. For 0.2% it is about 2.43%, for 0.4% about 4.91%. This shows why one-tenth of a percentage point in monthly dynamics attracts attention.
However, 3.66% in this example is the annualized equivalent of an unchanged monthly pace. It is not actual inflation over the last year and not a forecast for the next one. We only answered: what would happen if the same increase repeated twelve times? The model knows nothing about future energy, rent, transport, demand, or the dollar exchange rate.
To depend less on one month, you can look at three months. In a hypothetical sequence of +0.1%, +0.2%, and +0.3%, the cumulative increase is 0.6011%: (1.001 × 1.002 × 1.003 − 1) × 100%. Its annualized equivalent is about 2.43% if the three-month multiplier is raised to the fourth power. That is noticeably lower than the 3.66% obtained from the latest month alone.
Both results are correct, but they describe different horizons. The latest month reacts faster to a new change, while three months smooth out a one-off jump. It would be a mistake to choose only the convenient number and hide the other. For your own note, it is useful to record the horizon next to each percentage: one month, three months annualized, or the actual twelve months.
Next, it is worth looking inside the basket. In the August release, gasoline rose 3.9% month over month on a seasonally adjusted basis and accounted for more than a third of the monthly increase in headline CPI. The shelter component added 0.3%. These data help distinguish a strong move in one component from an equal increase across the whole basket.
The size of a component’s change and its contribution to overall inflation are also different things. Hypothetically, if a category has a weight of 4% and becomes 5% more expensive, its approximate contribution is 0.20 percentage points: 0.04 × 5%. A category with a weight of 40% that rises by only 0.5% gives the same approximate contribution. A small move in a large part of the budget can matter as much as a sharp jump in a small part.
This is a simplified illustration, not the exact CPI construction algorithm: official indexes have their own weights and aggregation rules. It is enough for a practical takeaway: the loudest percentage in the table does not necessarily explain most of the overall result. You need to look for contributions and the breadth of changes, not just the maximum in one column.
The core index excluding food and energy also needs to be read correctly. It does not mean those expenses are unimportant for a family. The Fed explains its use of core measures by wanting to see the trend better through the fluctuations of unstable components. At the same time, its long-run 2% target is defined through the PCE price index, not core CPI. Turning any CPI line into an exact measure of distance to the Fed’s target is incorrect.
Now back to crypto assets. My takeaway from this mechanism is that CPI is useful as information that can change the assessment of future financial conditions. Between the report itself and the BTC price there are several intermediate links: policy expectations, financing costs, willingness to hold risk assets, and already open positions. None of those links imposes an unchanging reaction to every new release.
The overall channel through rates is clear: they change the cost of borrowing and the incentives to save and spend. That is how the Fed describes it. But this does not imply a universal coefficient like “minus 0.1 CPI point equals plus 3% BTC.” No such coefficient is stated in the article, because the cited sources do not establish one.
Even more important is the difference between the result and expectations. Imagine two hypothetical worlds with the same actual monthly core CPI of +0.3%. In the first, a survey of economists before the release showed +0.2%; the result beat expectations by 0.1 percentage points. In the second, +0.4% was expected; the result came in 0.1 points lower. The statistics are the same, but the information surprise has the opposite sign.
These conditional expectations are not the current consensus as of October 14. No verified comparable survey was used in this material. If a reader takes a consensus from a calendar, the provider name, update time, and exact series should be kept alongside it. A forecast for headline CPI over the year cannot be compared with the actual core CPI for the month, even when both numbers are labeled inflation.
The survey median also does not tell us what expectations are embedded in each open position. So correctly identifying the surprise still does not guarantee correctly forecasting the first candle. For me, this is the limit of macro analysis: it explains how information changes, but it does not replace a separate check of the trading hypothesis, liquidity, and acceptable loss.
For October 14, I would prepare a short reading card with four numbers: headline CPI for the month and for the year, and core CPI for the month and for the year. I would add a note about seasonal adjustment to the monthly figures. Then: which components explain the result, whether the latest month is consistent with the broader horizon, and what exactly the deviation is from the verified forecast, if there is one.
It is useful, even before the data are released, to write down one condition that would force you to revise your own interpretation. For example: “I think the pressure is easing; I will give up that view if the acceleration spreads across several large components and is confirmed over a longer horizon.” This disciplines you better than trying to explain any result as confirmation of a position you already chose.
For the upcoming report and the next one or two releases, three conditional scenarios can be formulated. These are scenarios for the inflation environment, not price targets for crypto assets. They do not have assigned probabilities: without a model and verified current expectations, such numbers would create a false appearance of precision.
The base scenario is a mixed signal. Annual growth rates change, but monthly and shorter averaged measures do not show a consistent new direction; part of the move is explained by individual components and the comparison base. The condition for realization is a contradictory data structure. The condition for cancellation is a clear and broad acceleration or slowdown that no longer depends on one line of the table. Practical conclusion: one headline is not enough to change a long-term assumption.
A bullish scenario for risk assets is that inflation pressure weakens more broadly than just in the year-over-year comparison, and the result comes in below previously verified expectations. An additional condition is that market participants truly revise their assessment of financial conditions toward easing. The scenario is canceled if the improvement is mainly explained by the base effect or by a single unstable component, or if there is no repricing of conditions. Even if it happens, it does not guarantee growth in a specific token.
A bearish scenario is that the new price increase spreads across several important components, the short-term pace strengthens, and the result exceeds verified expectations. For a negative conclusion about financial conditions, the market must also actually reprice them. The scenario is canceled if the jump proves narrow and temporary, or if subsequent data do not confirm a sustained acceleration. A higher annual number by itself does not yet meet those conditions.
There are also time limits. Seasonally adjusted series can be revised: BLS updates the factors every year and revises the previous five years of relevant data. So a very precise interpretation of the difference in the last decimal place may turn out to be fragile. That is not a reason to ignore the statistics; it is a reason to match the strength of the conclusion to the quality and horizon of measurement.
A separate risk is applying the American consumer basket to your own expenses in Ukraine. Even the correct U.S. CPI reading does not measure the reader’s personal inflation, currency risk, or the change in the value of a specific portfolio. Other data are needed for those questions. One indicator can matter for global financial conditions and still be insufficient for a personal financial decision.
Before the October 14 release, the most useful preparation is to separate three questions. What happened to prices? How different is it from expectations? Does the new information change my own hypothesis? The answer to the first is in the statistics, the second requires a comparable forecast, and the third requires predefined conditions. If you skip any step, it is easy to take a familiar word for new evidence.
My conclusion: a decline in annual inflation should be checked against the denominator and the new monthly move. The August data already showed how different horizons give different signals. The September report may change the picture, but until it is released there is no result. Good decision-making begins with the ability to read a number together with its period, composition, and limits of use.
This material is for informational purposes only and is not individual investment advice.
#BinanceSquare #Інфляція #Макроекономіка #Крипторинок #ФінансоваГрамотність