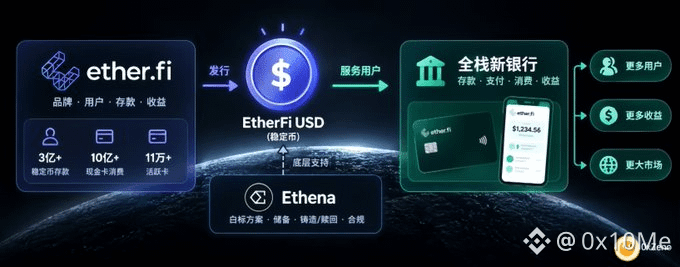
⚡️ Folks, EtherFi is launching its own stablecoin, called EtherFi USD, built directly on Ethena’s white-label solution. Ethena will handle all the heavy lifting—reserves, minting and redemption, and compliance—while EtherFi keeps the brand, customer relationships, and deposit yield.
The platform already has over $300 million in stablecoin deposits, its cash card has processed nearly $1 billion in cumulative spending, and it has more than 110,000 active cards.
The money and users are already there, and the cards and accounts are ready-made distribution channels. Until now, that money sat in other people’s stablecoins, leaving EtherFi with limited upside. Now it can be converted into its own coin, allowing EtherFi to retain more of the yield generated by the underlying strategies. For a project moving toward becoming a full-stack neobank, this is a pretty natural step.
Ethena’s white-label model makes sense: it doesn’t compete for its partners’ users, but standardizes the messy, labor-intensive parts of running a stablecoin. Partners keep the frontend and brand; Ethena handles the backend. MegaETH’s USDm and Jupiter’s jupUSD have already launched this way, but both remain small, and white-label coins still make up a very small share of USDe’s supply. EtherFi is bringing significantly more scale this time. And unlike a chain or DEX, a neobank already has deposits—it doesn’t need to build use cases first and then find the money.
If this works, it will likely become a template for Ethena to partner with more neobanks. The two are, in some ways, competitors. Ethena is also moving toward the neobank space, while EtherFi is one of the more execution-focused players among self-custodial neobanks. But this partnership shows that both are more interested in reaching a much larger market beyond crypto-native users than in fighting over the existing market.
The result is an increasingly common model: applications keep the brand and users, while the backend is concentrated in the hands of a small number of infrastructure providers. More stablecoin issuers don’t necessarily mean more decentralized reserves; the underlying minting, redemption, and compliance could actually become more concentrated.
For Ethena, the upside is that more applications are plugging into its infrastructure, driving up the use cases and demand for USDe. If EtherFi can shift some of its existing stablecoin balances over, the added volume could be substantial. The specific fees and revenue-sharing arrangements haven’t been fully disclosed yet, so that’s worth keeping an eye on.
The direction is already pretty clear: Ethena is positioning itself as the backend layer for stablecoin issuance, and neobanks like EtherFi are currently among its most natural customers.