

The cryptocurrency market can sometimes look like a casino: money keeps flowing, good news keeps coming, prices soar, and then they may fall again.
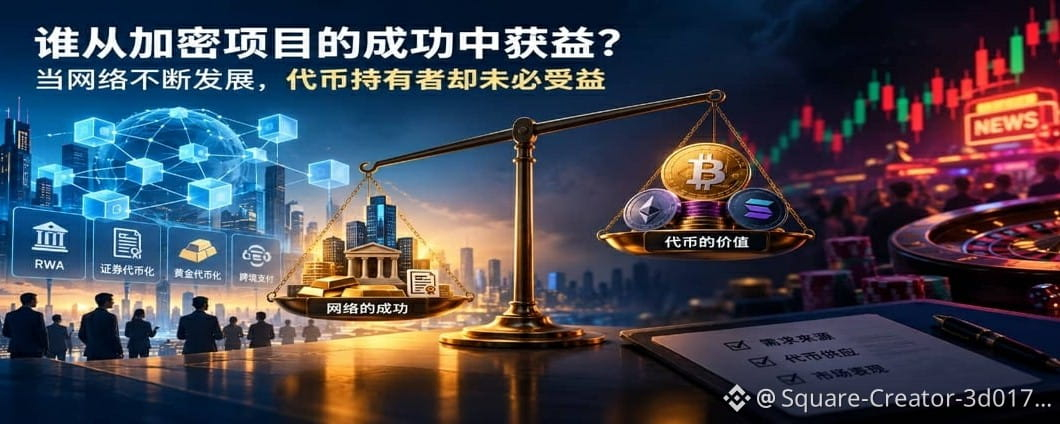
But there is an important distinction between the two: the crypto industry does have genuine technological innovation and projects that are building financial infrastructure. However, a project's success does not necessarily mean that investors who hold its tokens will earn the returns they expect.
The question is not whether the network can succeed, but how the value it creates is actually passed on to the tokens we buy.
I. News May Push Prices Up Before Real-World Use Grows
When a network announces an institutional partnership or expands its tokenization of real-world assets (RWAs), market expectations may rise, potentially increasing buying demand for the associated token.
But prices are also affected by liquidity, speculation, overall market conditions, and whether positive news has already been priced in.
Traders may buy after positive news is announced, or sell to take profits after the price rises. When market enthusiasm fades, a token's price may fall even while the project continues to develop.
So there is an important principle to keep in mind:
Markets trade not only on facts, but also on expectations about the future. Prices may move ahead of real-world use or diverge from the project's actual progress.
II. As the Network Grows, Where Does the Value Go?
When users rely on a network to process payments or trade tokenized bonds or stocks, they are using the infrastructure that the network provides.
However, the value of assets deployed on a network does not automatically translate into value for the network's native token.
If transaction fees are low enough, a network may support substantial economic activity without generating an equally large demand for its native token. Some networks also allow fees to be paid through other mechanisms, so users don't always need to hold large amounts of the native token.
So we need to distinguish between three different metrics:
Network success: Usage increases, partnerships expand, and applications and businesses continue to grow.
Token success: The market develops sustained economic demand for the token itself.
Investor returns: Gains from selling at a higher price than the purchase price, after transaction fees and taking risk into account.
These three metrics may improve at the same time, but they are not the same thing.
III. Potential Conflicts of Interest
Development teams need funding to pay employees, maintain infrastructure, conduct research, and expand their projects. Depending on a project's specific arrangements, some of this funding may come from tokens held by a foundation, the team, or the project treasury.
This can create a complex economic relationship: when the token price rises, the treasury may sell some tokens to raise more funds for project development. Meanwhile, institutional clients using the network want transaction fees to remain low and operating costs to be stable and predictable.
This difference in interests does not in itself prove that either party has acted improperly. It is normal for different participants to have different economic needs.
But it does raise a question worth considering as an investor:
Does the project's tokenomics allow token holders to share in the value created by the network's success? Or might the main beneficiaries be the network's developers and users?
The answer depends on the project and requires an analysis of its transaction fee mechanisms, token distribution, team and treasury holdings, and the actual rights enjoyed by token holders.
IV. Will the Development Team Sell Tokens When Positive News Is Released?
This is a question worth paying attention to, but we shouldn't assume the answer without evidence.
The development team or project treasury may sell some tokens to cover operating costs; early investors and other traders may also sell to take profits after the price rises.
If a large transfer or sale happens to occur around the time positive news is released, that timing alone does not prove that the seller was the development team, let alone that the news was released to facilitate a sell-off.
Investors can focus on the following information:
Token unlock schedules and plans for future increases in supply.
Project treasury reports, team token allocations, and disclosed token sale records.
Large transfers involving known wallets, bearing in mind that a transfer to an exchange does not mean a sale has been completed.
Trading volume, market liquidity, and price movements before and after positive news is released.
This information cannot provide absolute certainty, but it can help investors distinguish between the growth of network usage, increases in token supply, and potential selling pressure.
V. Why Aren't Crypto Tokens the Same as Stocks?
When buying stock, investors may, by law, acquire part ownership of a company or, if certain conditions are met, be entitled to dividends, depending on the type of stock and its legal arrangements.
But holding a crypto token usually does not automatically give you an ownership stake in the project, a right to share in its profits, or a claim to the transaction fees generated by the network.
Different tokens have different rights structures, so not all crypto tokens can be treated as securities, nor can we assume that token holders enjoy the same rights as shareholders. Their legal classification may also vary by jurisdiction and by the specific characteristics of the asset.
This means that a project may succeed technologically and commercially, and economic activity on its network may grow, without token holders necessarily receiving direct economic benefits commensurate with that success.
Summary: Understand a Token's Economic Model Before Investing
A project having innovative technology, announcing a partnership with a major institution, or seeing the value of tokenized assets on its network grow is not enough, on its own, to prove that its native token has the potential to rise in price.
The key questions are: What mechanisms make these activities create sustained demand for the token? And how are returns and risks shared between developers, network users, and token holders?
Before buying any token, it's worth focusing on three areas:
1. Sources of demand: Do users actually have to use the token, or can they use the network without holding large amounts of it?
2. Supply: Does the project have team or treasury holdings, token unlocks, or other arrangements that could increase selling pressure in the market?
3. Market performance: How much of the price increase comes from the growth of real-world use, and how much is driven by news, market expectations, and speculative capital?
Positive news may create trading opportunities, but it may also attract investors who buy after the price has already risen. A project can achieve genuine success and still fail to deliver returns to its token holders.
The market won't reward you just because your investment thesis is right. Your ultimate returns depend on the asset you buy, the price you pay, the real demand supporting that asset, and the risks you take.
#Crypto #Tokenomics #RWA #RiskManagement