



On October 7, BTC fell below $83,000, with $550 million in leveraged positions liquidated over 24 hours. On October 9, it hit a low of $80,427. Spot Bitcoin ETFs saw $484.9 million in outflows over the week.
That same day, Brent crude climbed above $104 a barrel. The 30-year U.S. Treasury yield hit 5.731%—its highest level since 2002.
Three things, on the same day.
This is no coincidence. It’s a complete chain of transmission.
The first link in the chain: Hormuz.
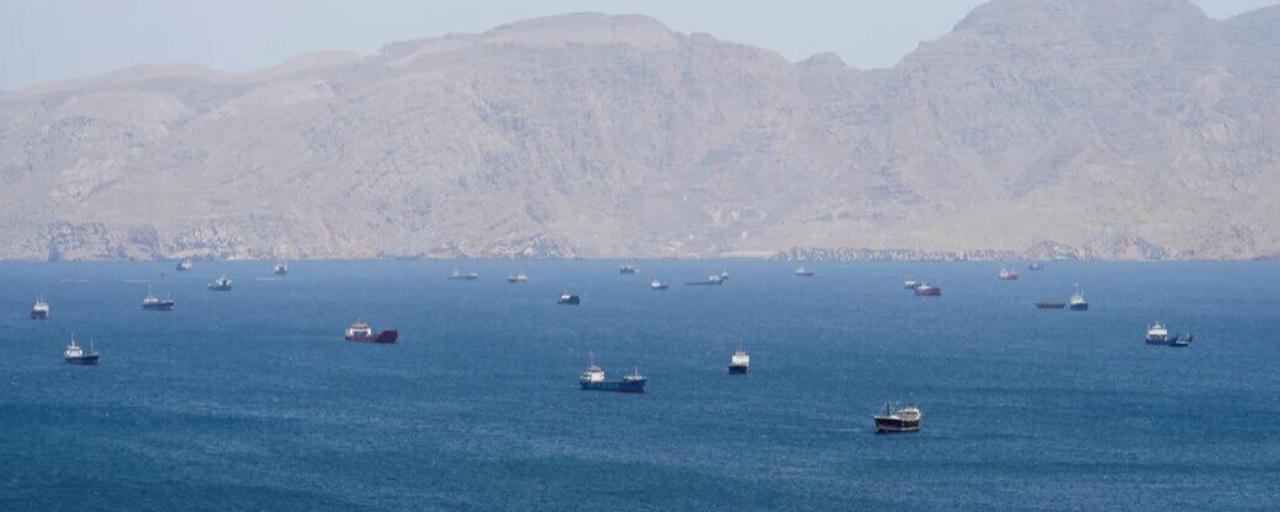
Kpler data shows that crude oil transit through the Strait of Hormuz fell 27% from its wartime peak to at least 10.1 million barrels per day, just 74% of prewar levels. On October 6, only seven merchant ships passed through the strait, the lowest number in two months.
The chokepoint for one-fifth of the world’s oil trade is being squeezed shut.
Oil prices above $104 aren’t about supply and demand. They’re about the risk premium.
The second link in the chain: diesel—the most brutal one.
When crude prices rise, people watch the news. When diesel prices rise, truck drivers refuse to work.
Diesel is directly tied to road freight and logistics costs. Moody’s chief economist Mark Zandi estimates that a sustained $1-per-gallon increase in diesel adds 0.1 percentage points to overall inflation. Prices are currently up about $2.50, which is expected to add roughly 0.25 percentage points to PCE inflation.
Barclays puts it more bluntly: diesel prices are up about 80% this year, potentially adding 0.15 to 0.23 percentage points to core inflation.
Crude oil makes the news; diesel shows up on the bill. The G7 is rushing to release diesel reserves not out of charity, but to cool the CPI data.
The third link in the chain: the Fed, delivering the final blow.
The September meeting minutes released on October 7 spell it out: Most officials thought another rate hike this year “would likely be appropriate,” and energy prices were listed as one of the “biggest challenges” to inflation.
Officials have stated explicitly that rate hikes can help prevent energy market shocks from driving up prices.
In plain English: If oil prices don’t fall, I’ll hike rates. If diesel prices don’t come down, I’ll hike rates.
The fourth link in the chain: Treasury yields, draining liquidity directly.
The 30-year yield is at 5.731%. It’s a level not seen since 2002.
Every basis-point rise in the risk-free rate reprices the opportunity cost of holding BTC. With Treasuries yielding 5.7% annually, holding BTC—which generates no cash flow—means competing with government bonds for your money.
A stronger dollar is weighing on risk assets across the board. BTC wasn’t sold off by crypto traders—it was dragged down by Treasury yields.
The only variable now: those 500,000 tonnes of Russian diesel.
On October 10, Russia officially partially lifted its ban on diesel exports, allowing 500,000 tonnes to enter the international market. This was agreed between Trump and Putin, and the U.S. Treasury also issued a temporary license.
If these 500,000 tonnes, together with the reserves released by the G7, can truly bring down diesel crack spreads, expectations for energy inflation could ease → Treasury yields could fall → BTC could get a window to catch its breath.
But if the Strait of Hormuz risk persists and transportation costs eat up the increase in supply, BTC will keep getting pulled back and forth in the “inflation-rate hikes” gravity field. The battle to defend $80,000 has only just begun.