

Over the past 24 hours, global capital markets have seen a modest recovery in risk appetite.
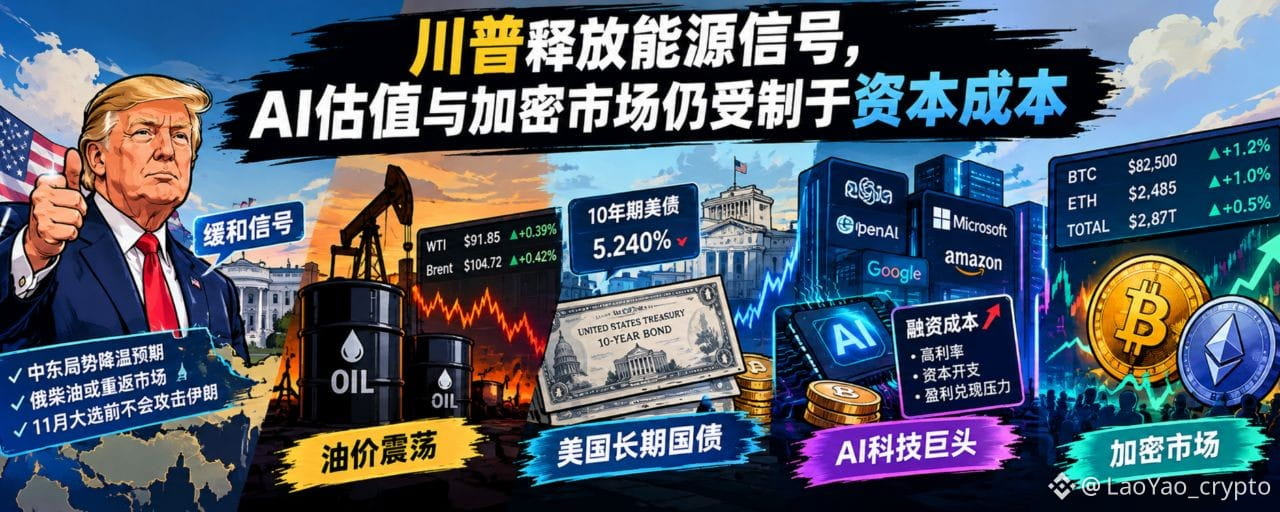
Signals from Trump on Middle East policy, along with arrangements that could allow Russian diesel to re-enter the global market, have temporarily eased some concerns about energy supplies.
Major U.S. stock indexes closed higher across the board, gold and silver rebounded, and crypto markets also recovered.
But markets have not truly escaped risk:
-Oil prices remain elevated
-Long-term U.S. Treasury yields remain under pressure
-The earnings and financial transparency of AI giants are being questioned
-Pressure in European bond markets has also yet to subside.
In the short term, markets are trading on marginal shifts in geopolitical risk; over the longer term, however, they still face the hard constraints of the cost of capital.
Next week's U.S. CPI data will become a new pricing node, and the market needs to reassess the inflation path and the Fed's rate-cut expectations.
🧱 Geopolitical competition:
Middle East risks remain unresolved, and the timing of the midterm elections is part of the game
Middle East energy risks continue to intertwine with U.S. domestic politics.
Renewed security risks in the Middle East: Houthi forces attacked Riyadh airport, causing 3 deaths, and there remains the possibility of further spillover in the regional security situation.
Energy supply release signal:
Trump said Putin agreed to release millions of tons of diesel into the global market; the U.S. Treasury plans to issue a temporary license to push Russian diesel supply into the market. If implemented, the arrangement is expected to ease some pressure on refined-product supply.
The midterm elections define the policy window:
Trump made it clear that he will not attack Iran before the November 3 midterm elections. But that does not mean U.S.-Iran relations have already improved.
The Strait of Hormuz remains the core variable:
The blockade of Iranian ports remains in effect. Trump said Iran is in a "very bad" situation and claimed that about 22 million barrels of oil passed through the Strait of Hormuz the previous night, with not a single barrel coming from or going to Iran.
The focus is on the mutual constraints among energy supply, military action, and the election cycle.
Trump's policy choices affect not only the geopolitical risk premium, but also domestic U.S. energy prices and inflation expectations.
If energy supply is replenished, upward pressure on oil prices may ease; if shipping risks continue to accumulate, the market may still reprice in a supply disruption premium.
💹 Capital mapping: risk appetite recovery
The performance of major global assets improved somewhat: the three major U.S. stock indices closed higher across the board; Japanese stocks were basically flat; crude oil rose slightly, and the geopolitical risk premium remained, reflecting that the market is trading a tug-of-war between two forces:
On the one hand, geopolitical risks have not worsened further for now, allowing some risk assets to recover;
On the other hand, the high-rate environment is still limiting funds' risk tolerance for high-valuation assets.
A rebound in risk appetite does not mean the liquidity environment has already loosened;
An asset rebound does not mean the earlier valuation pressure has disappeared.
📊 Bond market: long-term rates remain high
10-year U.S. Treasury: 5.240%, edging lower;
30-year U.S. Treasury: 5.599%;
2-year U.S. Treasury: 4.795%
Japan 10-year bond: 3.05%, maintaining high-level volatility;
The core contradiction facing the market is that short-term monetary policy expectations may adjust as economic data change, but long-term capital costs may not fall in sync.
High oil prices may push up inflation expectations, and fiscal financing needs and term premiums may continue to support long-term yields. Even if rate-cut expectations rise in the future, as long as the risk premium required by long-term capital remains relatively high, tech stocks, the AI industry, and crypto assets will struggle to fully escape valuation constraints.
The significance of the long end of U.S. Treasuries is not to explain all market volatility, but to measure the discount rate for future cash flows and the opportunity cost of capital.
📈 U.S. stocks: broad market steadies and rebounds
Nasdaq: +0.64%
S&P 500: +0.59%
Dow Jones: +0.83%
Major indices closed higher across the board, with real estate, consumer, and other sectors leading the way, indicating a recovery in market risk appetite.
But a single-day gain is not enough to confirm a new trend. Going forward, the market still needs to face three questions:
-Can oil prices find a new balance between geopolitical risk and additional supply;
-Do U.S. inflation data support rate-cut expectations;
-Can revenue growth at AI giants gradually translate into sustainable operating profits and free cash flow.
If rate pressure persists, the market may further distinguish between companies with genuine profitability and those whose valuations are supported by expectations of future growth.
🛢️ Crude oil: geopolitical risk premium is rising again
WTI: $91.85 / barrel, +0.39%;
Brent: $104.72 / barrel, +0.42%;
A slight rise in oil prices shows that expectations for new supply are still not enough to eliminate the geopolitical risk premium.
News that Russian diesel may enter the global market could potentially buffer refined-product supply, but diesel and crude oil are not exactly the same market. The actual impact also depends on licensing arrangements, logistics capacity, supply scale, and the refining system.
Shipping risks in the Strait of Hormuz still exist.
As long as the market cannot rule out the possibility of supply disruptions, energy prices may continue to include an additional risk premium.
🥇 Precious metals / FX:
Gold: $4,220.30 / ounce, +1.52%;
Silver: $60.78 / ounce, +2.74%;
The dollar index edged higher, dollar longs took profits, the yen was weaker, and the euro and pound retreated slightly;
Precious metals rebounded strongly, with silver showing much greater elasticity than gold.
High oil prices + U.S. Treasury yields staying elevated support the dollar.
🤖 The revenue accounting dispute among AI giants exposes financial transparency issues
The market rumor that "OpenAI has about $70 billion in revenue" is not the company's own figure, but an estimate made by investors who converted net revenue back to gross revenue for an "apples to apples" comparison with Anthropic.
Anthropic (gross method): revenue sold through cloud partners such as AWS and Google Cloud is fully counted as revenue, while the cloud partners' share is recorded as cost. ARR was reported at about $65 billion in July 2026
OpenAI (net method): only counts its actual share received (for example, Microsoft takes about 20%). As of the end of September, annualized revenue was close to $50 billion
Both companies remain private, with limited disclosure:
OpenAI previously had a financing valuation of about $852 billion, and reports say it is seeking a new round of financing on the scale of about $1.4 trillion
Anthropic 2025 revenue was nearly $4.6 billion (about 12x YoY), with a net loss of about $42 billion (of which about $34 billion was non-cash accounting expense related to convertible bonds), operating loss of over $8 billion, and future cloud and compute commitments of about $518 billion. The target IPO valuation could exceed $2 trillion, with timing possibly after the midterm elections
Common challenges: reliance on cloud partners for distribution (revenue-sharing erodes net income), high compute costs, concentrated revenue, sustained huge capital expenditures, and a distant path to profitability.
Summary:
This was not a sudden evaporation of sales, but rather an amplification of differences in accounting methods and extrapolation techniques, exposing the lack of financial transparency in frontier AI labs. Publicly traded AI-related stocks relying on this narrative therefore came under short-term pressure.
💸 Web3 overview: leverage washed out, the market re-tests risk tolerance
Over the past 24 hours, the crypto market followed U.S. stocks with a modest recovery, showing an overall pattern of falling first and then stabilizing. However, weak trading activity and ETF outflows suggest that funds remain cautious.
Total crypto market capitalization: about $2.87 trillion, up 0.52% in 24 hours;
$BTC : about $82,500, up about 1% in 24 hours;
$ETH : about $2,485, up about 0.5% in 24 hours, underperforming Bitcoin.
In relative terms, Bitcoin's recovery was stronger than Ethereum's, reflecting that current market funds still tend to allocate to relatively core crypto assets.
For investors, what is worth watching is not only the magnitude of the coin price rebound, but also whether spot funds continue to flow back, whether ETF fund flows can improve, and whether the rise is accompanied by a healthier trading structure.
🧘 Crypto market mindset:
The market variables of the past 24 hours show the following transmission path:
Geopolitical competition → energy supply and oil prices → inflation expectations → U.S. Treasury yields and term premiums → AI valuation and capital expenditures → global liquidity and crypto asset risk appetite.
This is the mutual inference of economic growth, fiscal policy, central bank expectations, corporate earnings, and market positioning.
This is LaoYao's analytical framework for observing the market:
—Starting from the surface market action, look for the underlying variables that truly affect capital pricing.
At present, it is especially necessary to distinguish three layers:
First, industry trends determine where value grows.
AI and blockchain continue to drive changes in production methods, business models, and financial infrastructure. Short-term market volatility is not enough to deny the long-term industry direction.
Second, earnings realization determines whether value can truly materialize.
Revenue growth, user scale, and technological breakthroughs are only part of the process. In the end, companies still need to prove that their business models can generate sustainable profits and cash flow.
Third, the cost of capital determines how much the market is willing to pay for the future.
Even if the industry direction is correct, if long-term rates, financing costs, and risk premiums remain high, the present value of future cash flows may still be suppressed.
Long-end U.S. Treasury yields deserve continued attention: they are an important yardstick for observing the global cost of capital and pressure on forward valuations.
At the same time, Trump's policy choices before the midterm elections provide a new time coordinate for the short-term evolution of geopolitical risks.
What the market needs to judge is not just whether the conflict escalates, but also how energy supply, the inflation path, and capital costs will interact.
Geopolitics in the short term, inflation in the medium term, and capital costs in the long term;
When it comes to asset pricing, the final answer still comes back to earnings and cash flow.
⚠️ The above is only my personal opinion and is for market observation and communication purposes only.
Geopolitical conditions are changing rapidly, please pay attention to position and leverage risks. This does not constitute investment advice.
📌 LaoYao (@LaoYao_crypto )
View capital through the lens of the mind, and distinguish trends through cycles;
Find certainty in uncertainty, anchor value in volatility.