

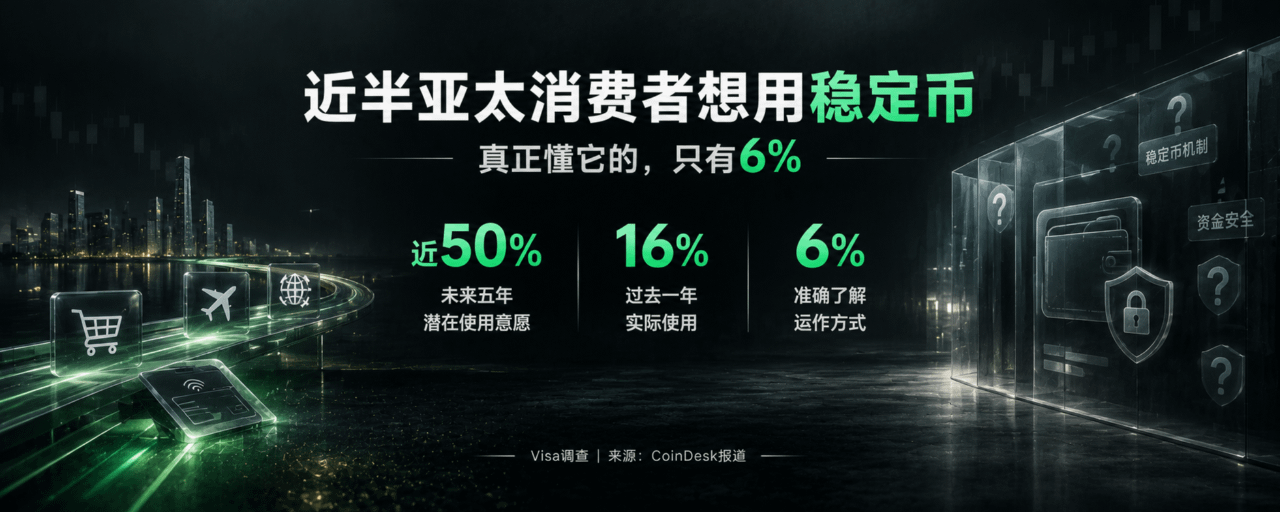

Summary: A Visa survey shows that nearly half of Asia-Pacific consumers may use stablecoins in the next five years, but a lack of awareness and concerns about fraud remain barriers to adoption.
Nearly half of Asia-Pacific consumers say they may use stablecoins in the next five years, but only 16% of respondents have actually used them in the past year.
A survey by payments technology company Visa also found that only 6% of respondents accurately understand how stablecoins work. According to CoinDesk, everyday spending, travel payments and cross-border transfers are emerging as use cases that interest consumers, while concerns about fraud and scams remain the biggest barrier to stablecoin adoption.
These figures reveal a tension as stablecoins move toward the mainstream: potential demand is growing, but users’ understanding of and trust in the products have not kept pace.
The biggest hurdle to bringing stablecoins into everyday life may no longer be whether they can be transferred, but whether consumers feel comfortable entrusting them with their money.
Willingness to use them is rising, and stablecoins are no longer confined to trading markets
In the past, the most common use for stablecoins was crypto trading.
Traders use stablecoins such as USDT and USDC to price trades, convert assets, and move funds. For people familiar with crypto markets, stablecoins are a practical tool for managing money; for ordinary consumers, however, they may still be an unfamiliar concept.
The interest reflected in Visa’s survey points to broader payment needs: everyday purchases, travel payments, and cross-border transfers.
These scenarios have one thing in common: users may not care how the blockchain works. They care more about whether payments are convenient, funds arrive on time, fees are reasonable, and problems with their money can be resolved.
This means stablecoins are now facing a different kind of competition from crypto trading.
In trading markets, users may proactively learn about wallets, networks, and transfer rules to trade more efficiently. For everyday payments, consumers often just expect to open an app they know, make a payment, and move on.
If using stablecoins means first having to understand a whole set of unfamiliar steps, they are unlikely to become an everyday payment habit for ordinary people.
What lies between 16% and nearly 50%?
Actual usage over the past year was 16%, while potential willingness to use stablecoins in the next five years is close to half. These figures measure different things and cannot simply be treated as a conversion funnel for the same group of people. Still, they show the gap between potential interest and actual use.
This gap is shaped by at least three factors.
First, is the payment process simple enough?
If users have to first buy stablecoins, choose a blockchain network, confirm a wallet address, and then learn how to make a transfer, these barriers will limit adoption. To reach more users, stablecoins need to become part of familiar payment experiences.
Second, are merchants and service channels widely available enough?
Holding stablecoins does not mean you can spend them directly. Merchant acceptance, fiat conversion channels, local regulatory requirements, and the reach of payment services all affect whether users can use them in real-world situations.
Third, do consumers trust that their funds are safe?
This is a particularly noteworthy finding from the survey. Concerns about fraud and scams were cited as the leading barrier to stablecoin adoption, showing that payment convenience is not consumers’ only consideration.
If a payment method can move funds quickly but does not clearly explain the risks or recourse available to users, its speed may not be enough to convince more people to adopt it.
Only 6% understand how they work, making risk awareness a weak point
The name “stablecoin” can create an intuitive impression: if its price is relatively stable, then the funds must be safe, too.
But price stability and fund security are two different things.
Stablecoins can differ significantly in their reserve assets, redemption arrangements, issuance mechanisms, and risk management. Even if a product aims to be pegged to the U.S. dollar, that does not make it identical to a bank deposit, nor does it mean all issuers have the same ability to meet their obligations or offer the same protections.
Stablecoin use may also involve risks such as wallet security, phishing links, impersonation platforms, and irreversible transfers.
For ordinary consumers, what they really need to know is not necessarily every technical detail, but a few more practical things:
Who issues the stablecoin, and how are its reserve assets managed?
If it needs to be converted to fiat currency, can it be redeemed as expected?
If a transfer goes to the wrong address or you fall victim to a scam, is there any way to recover your funds?
What security protections do the wallet and payment platform you use actually provide?
The fact that only 6% of respondents accurately understand how stablecoins work does not, by itself, prove that a lack of awareness is the sole reason for low adoption. But it does highlight a real issue: if users cannot understand the product they are using, it will be difficult to build consistent, lasting usage habits.
Trust in a payment tool comes not only from how conveniently it works when everything goes smoothly, but also from users knowing what options they have when something goes wrong.
Cross-border transfers may be where stablecoins’ value is easier to demonstrate
Everyday purchases, travel payments, and cross-border transfers could all become use cases for stablecoins, but the challenges of making them work in practice vary.
Everyday purchases require broad merchant acceptance and a sufficiently seamless payment experience. Travel payments need to work across payment networks in different regions while also addressing conversion and access to funds.
Cross-border transfers offer another possibility.
Traditional cross-border remittances may involve multiple intermediaries, processing times at different banks, and foreign exchange costs. In some situations, stablecoins can offer an alternative way to transfer funds and reduce certain intermediary steps.
However, this does not mean stablecoin transfers are necessarily cheaper or faster. The actual cost still depends on blockchain network fees, fiat on- and off-ramps, conversion spreads, compliance requirements, and whether the recipient can use the funds without difficulty.
What really matters is whether stablecoins can demonstrate a verifiable efficiency advantage in specific cross-border payment corridors.
If funds can be transferred more conveniently, conversion channels are reliable, and compliance and security issues are properly addressed, stablecoins could expand beyond infrastructure for crypto trading into broader payment networks.
The next stage is about more than just how many people say they are interested
Visa’s survey reflects consumers’ willingness to use stablecoins, their understanding of them, and their concerns. It cannot directly predict actual adoption over the next five years.
To assess whether stablecoins are truly moving into the mainstream, there are three signals to watch.
First, is real-world payment use growing?
Beyond stablecoin trading and fund transfers on exchanges, it is also important to look at how stablecoins are used for real-world purchases, travel payments, and cross-border remittances.
Second, is the payment experience becoming more seamless?
The barriers to adoption may fall if users can pay with stablecoins through familiar wallets, payment apps, or merchant systems without having to handle complex on-chain operations themselves.
Third, are trust mechanisms keeping pace?
Reserve disclosures, redemption arrangements, anti-fraud measures, compliance frameworks, and dispute-resolution capabilities will all affect whether consumers are willing to use stablecoins over the long term rather than just trying them once.
These indicators are closer to actual market progress than stated willingness to use stablecoins alone.
Stablecoins need to earn the trust of ordinary consumers
Nearly half of consumers in Asia Pacific say they may use stablecoins in the next five years, showing that this payment method has attracted broader attention. But the actual usage rate over the past year was 16%, and only 6% of respondents accurately understood how stablecoins work. These figures are a reminder to the market: interest does not equal adoption, and price stability does not mean risks disappear.
Future growth in stablecoins will depend not only on whether blockchain technology can make transfers more efficient, but also on whether issuers, payment platforms, and service providers can turn complex financial and technical mechanisms into an experience that ordinary users can understand.
For consumers, what may matter most is not which blockchain a stablecoin runs on, but whether the payment goes through, whether the funds can be converted, and whether there is a clear way to resolve problems.
Stablecoins will truly be closer to the mainstream when people no longer need to become proficient in crypto technology just to make an ordinary payment.
#Stablecoins #Visa #AsiaPacific #CrossBorderPayments #DigitalPayments #CryptoFinance