



On October 8 Beijing time, the Federal Reserve released the minutes of the September 15–16 Federal Open Market Committee (FOMC) monetary policy meeting.
The minutes brought the Fed back to a “get inflation down first” framework: the rate hike has been delivered, and another hike before year-end remains the majority’s baseline expectation. The minutes showed that all participants supported the decision to raise rates by 25 basis points in September. Most participants felt that further rate hikes this year might be appropriate, though action in October was not a necessity.
After the minutes were released, risk assets led the decline. BTC briefly fell to $82,300 this morning before recovering to $83,000. Most other altcoins were down more than 3%.
The data show that spot ETFs continued to see net subscriptions after the rate hike was delivered. BTC spot ETFs recorded $2.6 billion in net inflows in September, the second-highest monthly total this year, behind only August’s approximately $3.52 billion. This indicates that institutional demand has not withdrawn, and the outlook remains worth watching.
What did the minutes say?
At its September 15–16 meeting, the FOMC voted unanimously, 12–0, to raise the federal funds target range by 25 basis points to 3.75%–4.00%, its first rate hike since July 2023. The minutes further noted that all 19 meeting participants supported the decision. Most judged that another increase in the target range before year-end might be appropriate, while emphasizing that every meeting remained open and that future decisions would depend on the data and what they implied for the outlook and balance of risks.
Inflation is at the heart of this shift. Staff estimated that headline PCE inflation was about 3.8% in August and core PCE about 3.4%; progress on disinflation in recent months had been insufficient, and risks were seen as almost uniformly tilted to the upside. Contributing factors included energy prices driven by geopolitical developments, tariffs, and investment, input costs, and prices of technology-related goods associated with AI infrastructure buildout. Economic activity continued to expand at a solid pace, consumer spending was resilient, unemployment was about 4.1%, and the labor market was close to full employment. A few participants even judged that the policy rate before the hike was “not restrictive or only slightly restrictive.” Some viewed a higher rate path as insurance against persistent inflation, while others saw it as necessary under the baseline outlook.
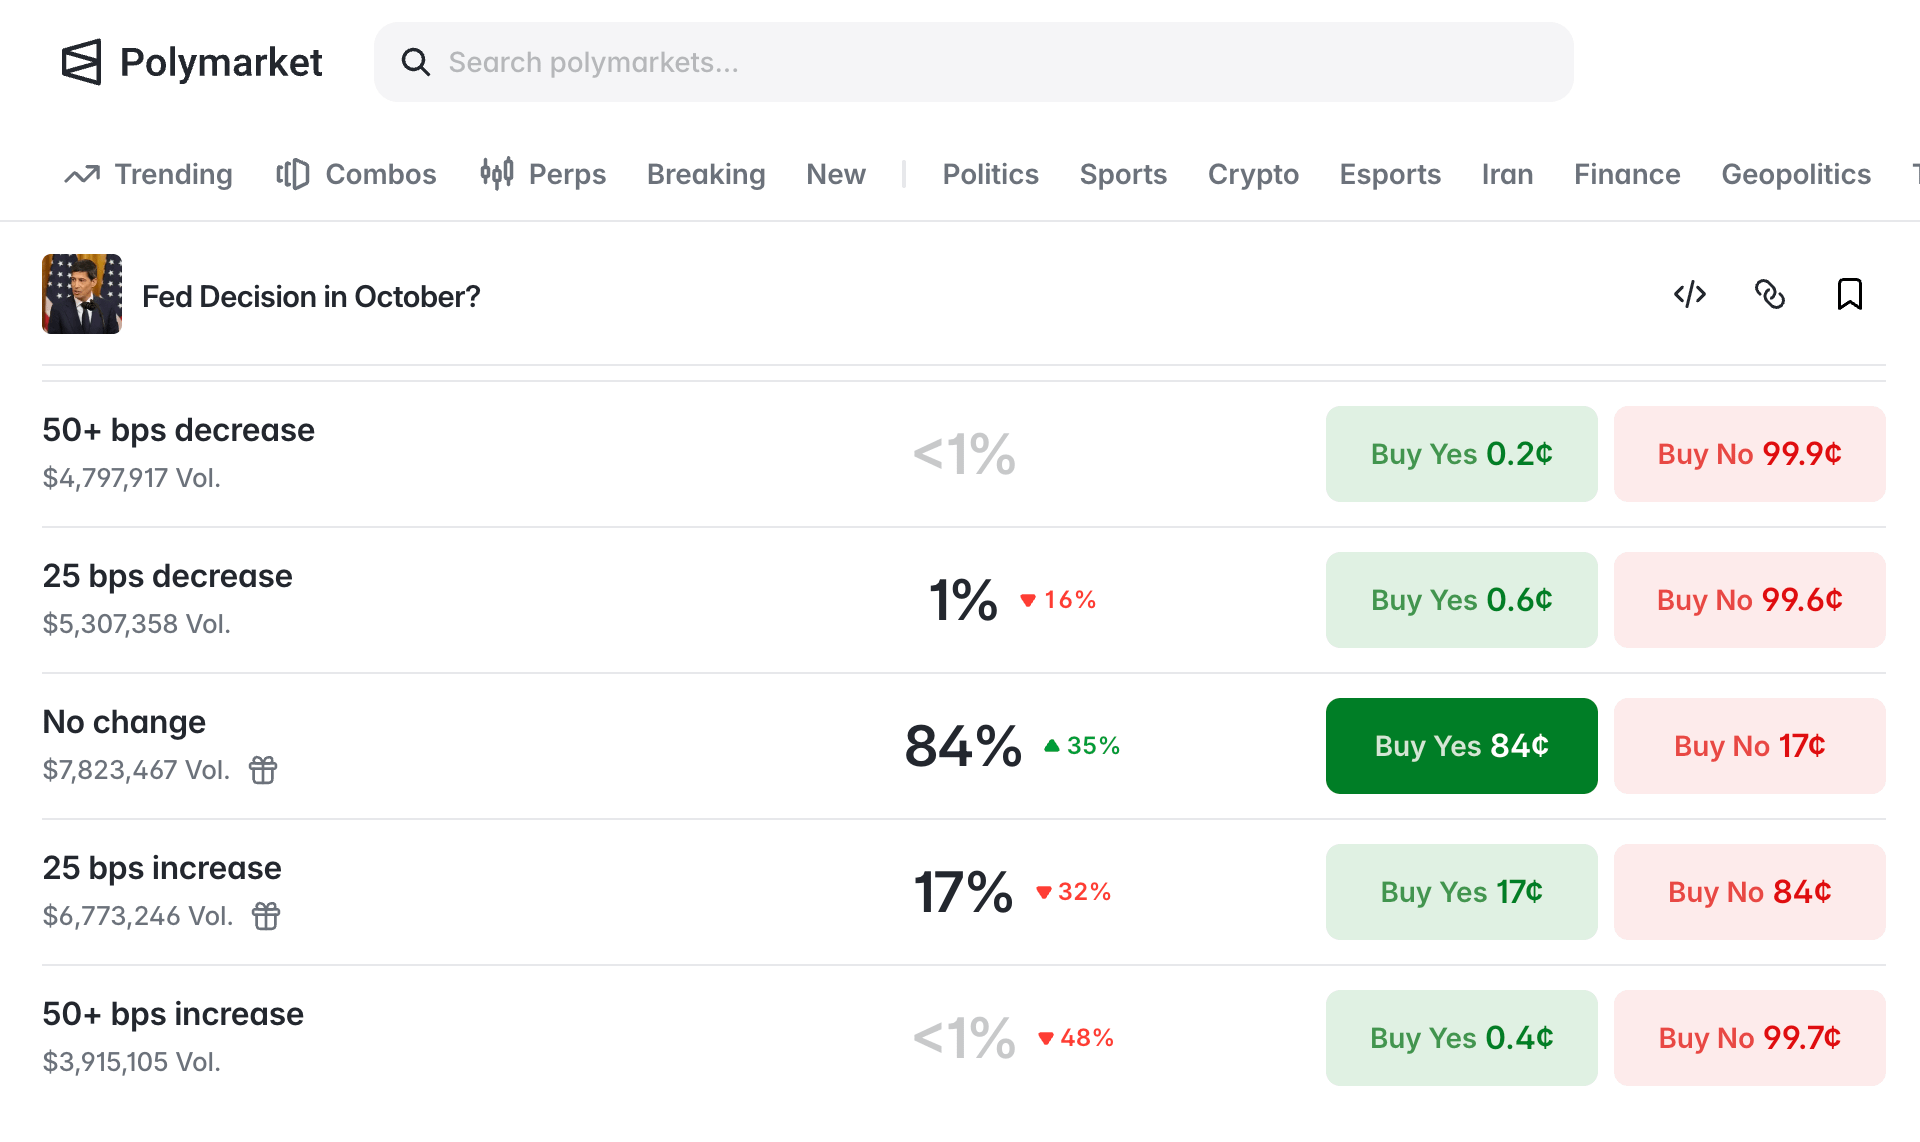
Polymarket data show that after the minutes were released, the probability of rates remaining unchanged in October reached 84%, up 35% over the past week; the probability of another rate hike before year-end remains above 70%. In other words, the minutes confirmed a “bias toward tightening this year,” not that “another hike in October is inevitable.”
For risk assets, the pressure comes not just from rate hikes themselves, but from rates staying higher for longer. If expectations of further hikes keep nominal and real rates elevated, long-duration assets, high-valuation growth stocks, and crypto assets will all face pressure on their theoretical valuations. During the period between meetings, 2-year to 10-year Treasury yields rose by a cumulative 35 basis points. Financial conditions have not tightened across the board—stocks remain high and credit spreads narrow—but the minutes explicitly treated “financial conditions remaining supportive of growth” as part of the inflation risk, not as background that can be ignored.
The minutes did not describe a recession; they described strong investment, steady employment, and elevated inflation. In this mix, risk assets are not being bought on a “recession trade” or on expectations of “unlimited easing.” The market is pricing in an economy that can withstand higher rates and a policy stance that will go a step further to achieve the 2% target. For high-beta assets, volatility will come from the data, not from an unexpected policy reversal.
After the rate hike, crypto ETFs are buying instead
Interestingly, institutional demand in the crypto market does not seem to have weakened because of the rate hike.
According to SoSoValue data, U.S. spot Bitcoin ETFs saw net inflows of about $2.65 billion in September, almost all of which came after the September 16 rate hike: the two days before the hike saw combined outflows of about $750 million, while net inflows from September 17 through month-end totaled about $2.9 billion. Inflows for the week ending September 25 were about $2.4 billion, the largest weekly total since October 2025, with nearly $1 billion coming in on September 21 alone. BlackRock’s IBIT was the main driver. Spot Ethereum ETFs also recorded net inflows of about $690 million over the same period. Bitcoin rose from around $78,500 to approximately $83,000 during the month, then fluctuated around the $84,000 level.
The longer-term picture also shows that rate hikes have not derailed allocations. In mid-July, cumulative net outflows from spot Bitcoin ETFs in 2026 briefly reached about $5.8 billion; a week after the September hike, net flows for the year turned positive again. By early October, cumulative net inflows since the products launched were about $57.8 billion, with net assets of around $110 billion. Daily flows turned mixed in October—there were still net inflows of about $120 million on October 6, and some trackers showed about $3.5 billion in net inflows over a 30-day window—but September’s direction was already clear: a fully priced-in 25-basis-point hike was not, by itself, a trigger for institutions to exit.
This runs counter to the conventional intuition that “rate hikes mean selling risk assets.” The reason is that the probability of a hike was already above 90% before the decision, and outflows were concentrated in the days before it. Once the hike was delivered, uncertainty declined, prompting both short covering and a return of allocation flows. The buying took place through regulated spot ETFs, representing actual Bitcoin purchases rather than leveraged futures. Such flows are less sensitive to a single 25-basis-point move than to the stability of regulated investment channels and whether portfolios need an uncorrelated asset.
Not an easing trade, but a “rate hikes are bearable” trade
The minutes show that most officials still considered another hike appropriate, and some felt that policy rates were not yet restrictive enough. If the October 14 CPI report or subsequent employment data again reinforce the persistence of inflation, December rate-hike pricing will quickly rise, while real yields and the dollar will weigh on high-beta assets. In this scenario, crypto typically trades first on liquidity expectations, then on its own supply and demand. ETFs can cushion the impact, but they cannot hedge a surge in risk-free rates.
The probability of rates remaining unchanged in October is now clearly higher than it was in the first few days after the meeting, giving risk assets a data-free window. More importantly, September’s ETF flows show that when growth has not stalled, rate hikes are already priced in, and access to spot products remains open, institutions can treat Bitcoin as an allocatable asset rather than merely a hedge against monetary easing. Spot products for Ethereum, Solana, and others also recorded net inflows during the same week, suggesting this was not just short-term covering in a single asset.
Going forward, the key is whether three sets of data move in the same direction: whether PCE/CPI inflation stays above 3%, locking in a December rate hike; whether rising Treasury yields actually tighten financial conditions; and whether spot ETFs continue to see net inflows even as Bitcoin approaches holders’ cost basis.
If only one of the three signals points in the right direction—rates rise while flows turn negative—the “rate hikes are bearable” narrative for risk assets will fade. If inflation moderates at the margin, an October pause is confirmed, and monthly ETF flows remain positive, crypto is more likely to trade on allocation demand amid lower volatility than on expectations of a new round of aggressive easing.