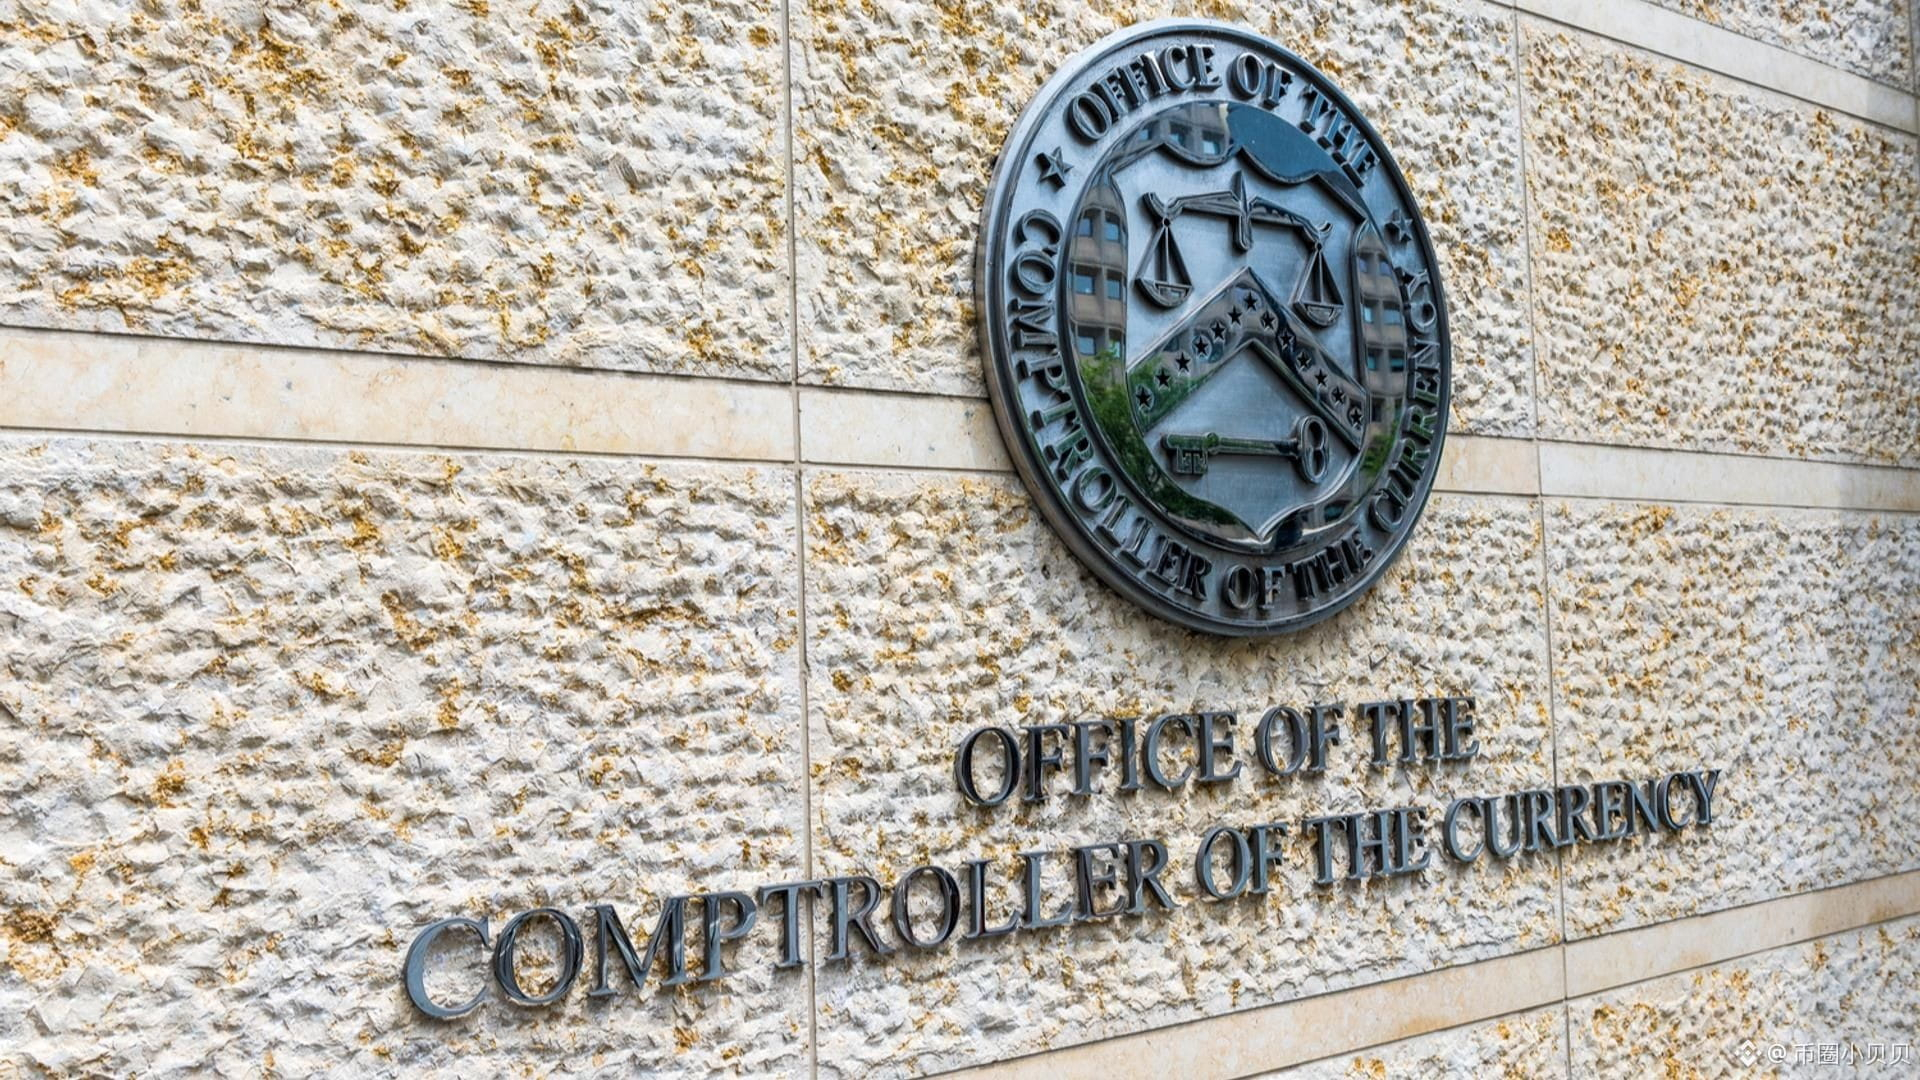
A banking charter application filed by a crypto company might seem, at a glance, like just another compliance story. But what’s really worth paying attention to this time isn’t whether it gets approved—it’s what kind of bank it’s applying to become.
💥 进群蹲一手消息
Stablecoin payments company Rain has filed an application with the U.S. Office of the Comptroller of the Currency to establish a national trust bank in New York. The bank would not take deposits, make loans, open consumer accounts, or have federal deposit insurance. It would do just three things: custody digital assets and dollars for institutions, manage reserves for compliant stablecoin issuers, and issue and redeem stablecoins for institutional clients. Rain says customers’ assets would be accounted for separately from the bank’s own assets.
Most people see this as yet another crypto company moving closer to regulators. But look at it another way: what it really wants is to cut out the middle layer. Today, a stablecoin company that wants to issue and redeem stablecoins has to rely on a third-party bank to hold its reserves. Clearing and moving money in and out are also in someone else’s hands—and that means someone else gets the fees and interest spread. With its own charter, that layer becomes its own business.
This isn’t an isolated case. Last December, a group of companies including Circle, Ripple, BitGo, and Fidelity received preliminary approval. At the end of July this year, Circle received final approval in New York. Rain is the twelfth company in line. The race has shifted from issuing tokens to securing charters, and the valuation story is moving downstream too—to custody, reserves, and clearing and settlement.
But traditional community banks are pushing back against this path. Last week, the Independent Community Bankers of America sued the OCC, arguing that it has no authority to grant national trust charters to crypto companies that don’t conduct traditional banking business. That would give these companies the privileges of banks without the obligations. The real legal battle on this path is over who counts as a bank.
So the real thing to watch isn’t whether Rain’s application gets approved. It’s the outcome of that lawsuit. If the court sides with community banks, this whole batch of applications could get stalled. If the OCC wins, it would effectively open a permanent channel for crypto companies. A charter is just the ticket in; what determines who gets to stay at the table has always been who controls that channel.