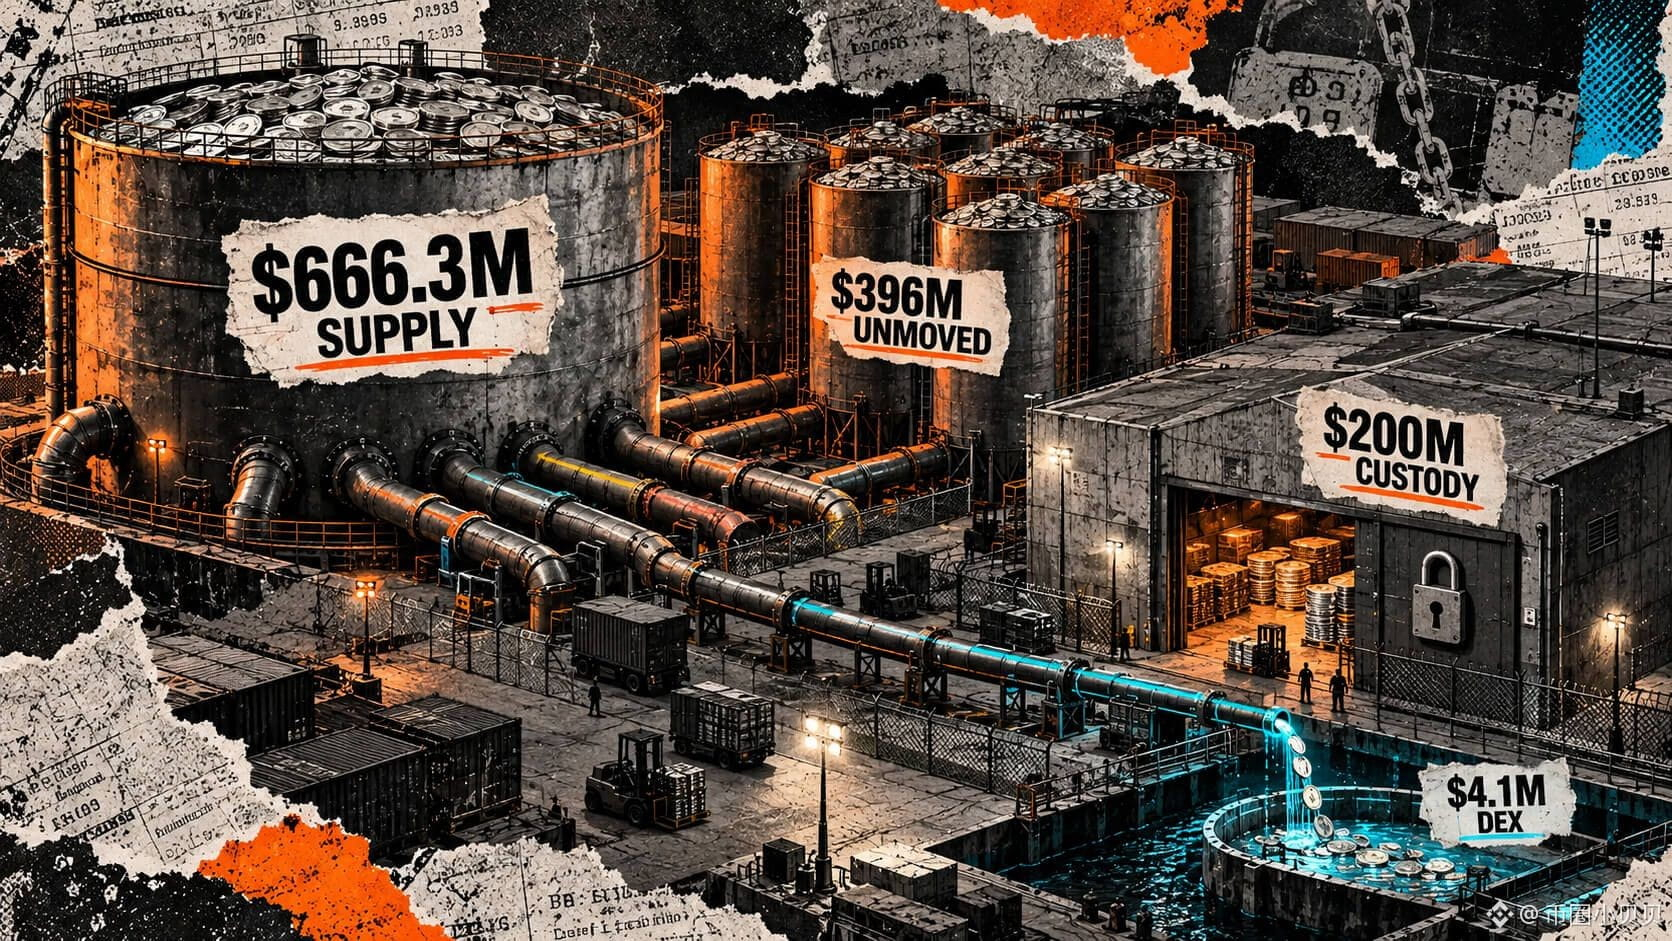
A stablecoin that launched just a week ago has already reached an issuance of over $600 million, with several payment giants behind it. For most people, that kind of debut sounds like another major player has entered the stablecoin market. But break down the on-chain data, and nearly $400 million of that total has never moved.
📢 今日盘面群里聊
The figures come from a wallet study published by Crystal Intelligence on October 6, based on data as of the early hours of October 5. Open USD is issued by Open Standard, whose members include several payment and e-commerce companies. The project launched simultaneously on four chains on September 30: Base, Ethereum, Solana, and one called Tempo.
The key question is where the money is sitting. The study found that nearly $400 million is parked in eight Tempo wallets, sent there directly by the issuer and never moved since. Another $200 million was transferred on October 1 to the custody account of a major exchange, and has also stayed put. Ten wallets hold more than 70% of the entire supply, and Tempo alone accounts for 70%.
So what issuance measures here is really stockpiling, not circulation. The amount actually in use is much smaller. In the first week, total trading volume on decentralized exchanges across the four chains was just over $4 million: $3.4 million on Solana, $700,000 on Base, and only $17,000 on Tempo, which holds most of the supply. The number of transfers tells an even clearer story: of more than 11,000 transfers, over 70% were classified as network fee payments, totaling just over $3.
This is a more telling clue than the issuance figure itself. Over the past two years, the stablecoin race has been boiled down to a contest of scale: whoever has the biggest reserves wins. But if even a newly issued stablecoin has to be seeded into wallets first, that suggests the battleground has shifted. Whether the money can actually be put to use depends on payment rails, merchant access, and settlement use cases—not the supply figure in a white paper.
Of course, the first week’s data is no proof of failure. Issuers routinely seed the market before scaling up. The two signals worth watching are when those wallets start sending funds out, and whether new tokens are minted by anyone besides the founders and their partners. Once those wallets move, the story changes. If they never do, the market is left with little more than a very impressive figure on paper: over $600 million.