

Musk has crossed back above the “trillionaire” threshold, but I think
$SPCX
what’s really worth watching this time isn’t how much Musk’s wealth has increased, but that the market is finally starting to revalue SpaceX’s “second layer” of business.
On Monday, $SPCX surged 7.6%, closing at $171.09, its highest level since July.
Since its August low, SpaceX has rebounded nearly 60%.
The rally wasn’t driven by any single piece of news.
Rather, several catalysts have suddenly started appearing at the same time:
Starship has reached a new technical milestone.
The AI business is starting to be incorporated into valuation models.
Chip manufacturing is becoming a new area of potential.
Neocloud computing-power contracts may continue to increase.
The importance of the defense business is also growing steadily.
That’s also why Morgan Stanley’s Adam Jonas recently again described SpaceX as:
“Cheap and Getting Cheaper” — the higher it rises, the cheaper it may actually become. Yahoo Finance
That sounds like an exaggeration.
Because by traditional valuation methods, SPCX is not cheap at all.
Morgan Stanley estimates that SpaceX is currently trading at around 30 times 2028 EV/EBIT, while the median for other large AI beneficiaries is only around 16 times.
But Jonas believes this comparison is flawed in itself.
Because SpaceX’s earnings are expected to grow much faster over the next few years than those of many large tech companies.
If we also factor growth into the valuation model, SpaceX is currently at around 0.3x EV/EBIT/Growth, compared with a median of around 0.5x for large tech companies.
In other words:
After adjusting for growth, #SpaceX is actually about 40% cheaper than many large-cap tech stocks. Yahoo Finance
That’s also why Morgan Stanley continues to maintain its:
$300 price target.
At around $171, that still implies roughly 75% potential upside.
But what really makes me think this report is worth reading isn’t the $300 price target itself.
but what Jonas believes is that:
The market currently understands only the two easiest parts of SpaceX’s business.
Starlink.
Rocket launches.
As for the other business ecosystem SpaceX is gradually building, the market may not have fully priced it in yet.
The most important of these is:
AI.
In the past, we typically broke down SpaceX’s valuation into:
How much is Starlink worth?
How much is Starship worth?
How much is the launch business worth?
How much are government contracts worth?
But Morgan Stanley is now formally including AI in its SpaceX valuation model.
And it’s not just a symbolic figure.
In Jonas’s valuation framework, the AI business has already become an important part of determining SpaceX’s long-term valuation. MarketWatch
This actually aligns perfectly with what Musk has been doing over the past few months.
xAI merges into SpaceX.
SpaceXAI is renamed SpaceXSI.
Colossus continues to expand.
SpaceX begins offering AI computing power to external customers.
Terafab begins discussing chip manufacturing.
Starlink provides global communications infrastructure.
Tesla has Robotaxi and Optimus.
If all these pieces eventually connect, SpaceX may not be a “space company” at all in the future.
but a company that controls all of these at once:
Communications.
Computing power.
Chips.
Data centers.
AI models.
Robotics.
Satellites.
Rockets.
That’s why I increasingly feel that the market’s traditional aerospace-company framework for understanding
SPCX
may become increasingly distorted in the future.
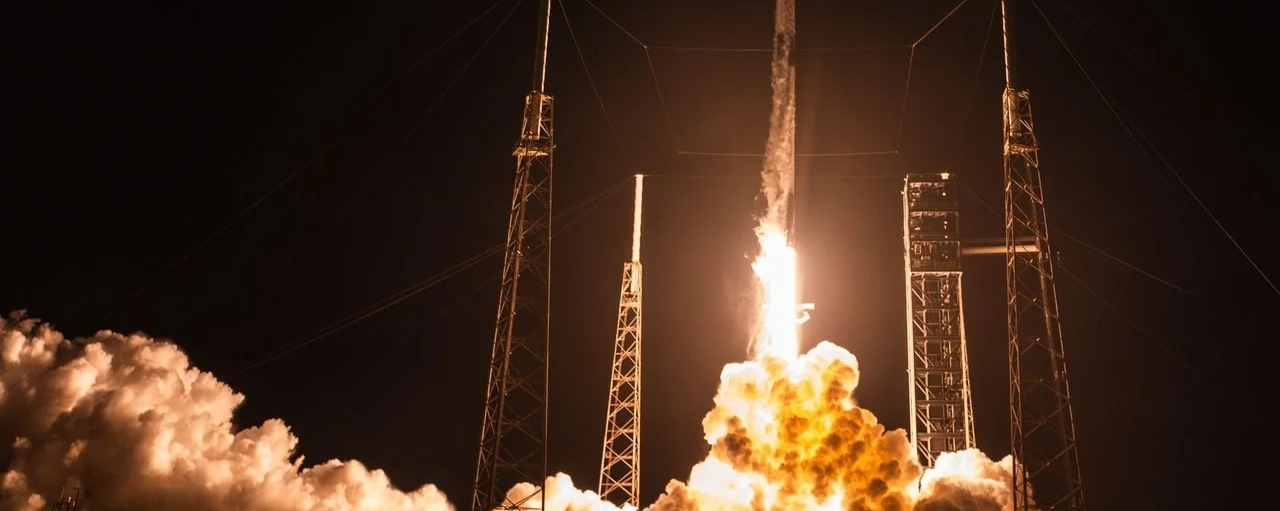
And the first catalyst that is now genuinely close to materializing is Starship.
Morgan Stanley believes the upcoming Flight 15 could be one of the most important technical catalysts since SpaceX went public.
The reason is simple:
The next thing to prove is whether Starship’s upper stage can become reusable.
People have already seen the Super Heavy booster recovered.
But what will really determine the ceiling of Starship’s entire business model is:
Both the upper and lower stages are reusable.
If Starship’s upper stage can also be reliably recovered in the future, SpaceX’s launch economics could undergo another major shift.
Today, Falcon 9 has already used reusability to push launch costs down to levels that traditional aerospace companies struggle to compete with.
And Starship’s goal is even more ambitious:
Larger payloads.
Higher launch frequency.
Lower unit costs.
Fully reusable.
If successful, Starship would affect more than just the rocket business.
It will directly affect:
The pace of Starlink satellite deployment.
Space-based data centers.
Lunar missions.
Mars missions.
Defense transportation.
Deep-space infrastructure.
and even the possibility of AI computing power moving into orbit in the future.
That’s also why Jonas explicitly said that the weeks leading up to Flight 15 could be an important window for the market to reassess SpaceX’s value.
But I think there’s another area that may be more undervalued than Starship right now:
SpaceX is gradually moving from being a buyer of AI computing power to becoming an AI infrastructure provider.
Morgan Stanley specifically noted:
Future AI product launches.
More Neocloud contracts.
Chip manufacturing.
And AI computing-power pricing.
All of these could become catalysts for further valuation increases over the next few months.
Especially the Neocloud segment.
Jonas noted that if SpaceX continues to sign computing-power contracts and can maintain prices in the range of around $30–50 per watt, that could further demonstrate the profitability of SpaceX’s AI business. Yahoo Finance
This figure is well worth noting.
Because the unit of competition in the AI industry may increasingly be not:
How many GPUs there are.
but:
How many gigawatts of power you control, and how much revenue you can generate per watt.
That’s exactly why recently we’ve seen
$CRWV
The valuation logic for $IREN and $NBIS is also beginning to shift away from GPU counts and toward:
MW.
GW.
Access to power.
Data center capacity.
If SpaceX really scales its AI business sufficiently, its advantages could be even more formidable than those of a typical Neocloud provider.
Because ordinary Neocloud providers have to buy from others:
Land.
Power.
Chips.
Networks.
And Musk is trying to bring all of this in-house.
The recent developments around Terafab are especially worth noting.
Musk has confirmed that SpaceX is working with
$TSM TSMC discusses a partnership.
At the same time,
had also previously entered discussions related to Terafab.
If it really does come together in the end:
Intel + TSMC + SpaceX capital
with this kind of structure, Terafab takes on a completely different significance.
It’s not that SpaceX has suddenly decided to compete with TSMC.
Instead, Musk may be trying to secure control of:
The chip manufacturing capacity that will be scarcest in the future superintelligence era.
Because if SpaceXSI, Tesla, Optimus, Robotaxi, and Starlink all need increasingly more AI chips in the future, the biggest risk isn’t that chips are expensive.
but:
Even if you have the money, you can’t get it.
So what Musk is doing now increasingly looks like he is removing all the key bottlenecks in advance.
Lack rockets?
Build it themselves.
Lack satellite networks?
Build Starlink themselves.
Lack AI models?
Build xAI.
Lack computing power?
Build Colossus.
Lack chip manufacturing capacity?
Build Terafab.
Lack communications?
Starlink has global coverage.
If chip manufacturing also starts to be integrated in-house, SpaceX’s business model will have gone far beyond that of a traditional aerospace company.
There’s another area the market has clearly not fully priced in yet:
Defense.
SpaceX has become an increasingly important aerospace and communications supplier to the U.S. government.
Musk was also recently appointed to participate in the Pentagon’s Project Meridian, joining tech figures such as Palmer Luckey to study the technologies and capabilities needed for future warfare. Axios
What’s really worth paying attention to here isn’t a committee title.
but that future warfare is increasingly dependent on:
Satellite communications.
Low Earth orbit satellites.
Autonomous systems.
AI.
Drones.
Real-time data.
Space-based sensing.
Global networks.
Almost all of these fields overlap with SpaceX’s existing capabilities.
Starlink has already shown that, in modern warfare, satellite internet is not an ordinary communications product.
it can become strategic infrastructure in its own right.
And if Starship can provide large-scale, low-cost, rapid access to orbit in the future, SpaceX’s position in the U.S. defense system may strengthen further.
So SpaceX’s revenue mix may gradually shift from:
Consumer Starlink
Commercial launches
becomes:
Starlink
Starship
AI computing power
Chips
Government and defense
Cloud services
Space infrastructure
That’s why I think what’s really worth examining behind the $300 price target isn’t “the stock can still rise 75%.”
but:
For the first time, the market is trying to value all of SpaceX’s businesses at once.
There’s another very interesting detail.
When Adam Jonas recently gave a presentation to a group of about 40 institutional clients, he asked the room:
“Who owns SpaceX?”
Almost no one raised their hand.
When he has done similar presentations in the past, sometimes only one or two people raised their hands.
This means something very interesting:
Although SpaceX is already one of the world’s most closely watched companies, institutional ownership may still be far below that of traditional mega-cap tech companies.
That’s why this rally may be particularly worth watching.
If SpaceX is just a popular retail-investor story, marginal buyers will gradually disappear once the stock reaches a certain level.
But if the AI business, Starship, government contracts, and profitability continue to deliver in the future, and institutions start rebuilding their positions, the pool of potential buyers will change.
This is what Morgan Stanley is truly bullish on.
It’s not that the market already fully believes in SpaceX.
Quite the opposite.
Instead, many large institutions may not actually own it yet.
Of course, SPCX is absolutely not without risks.
Starship remains a high-technical-risk project.
AI infrastructure requires extremely high capital expenditure.
Chip manufacturing is one of the most complex industrial systems in the world.
SpaceX’s simultaneous expansion into so many fields also means its future capital needs will be enormous.
So what matters most for this company’s future isn’t “how many stories it has.”
but whether each story can ultimately translate into:
Revenue.
Profits.
Cash flow.
But if, over the next few quarters, we start seeing:
Successful recovery of Starship’s upper stage.
New AI computing-power contracts.
Terafab partnership officially takes shape.
SpaceXSI revenue is growing rapidly.
Starlink continues to expand.
Defense orders continue to increase.
then the market may begin to realize:
Right now,
SPCX
isn’t just a “rocket company + satellite internet company.”
but a company simultaneously vying for:
Space infrastructure + global communications + AI computing power + chips + defense technology
A company operating in five major growth sectors.
That’s also why Morgan Stanley still believes SpaceX may be undervalued even after its share price reached $171.
The real question has never been:
Is SpaceX worth $171?
but:
If Starship, Starlink, SpaceXSI, and Terafab all take off at the same time in the future,
What company valuation framework should we use today to value a company like this?