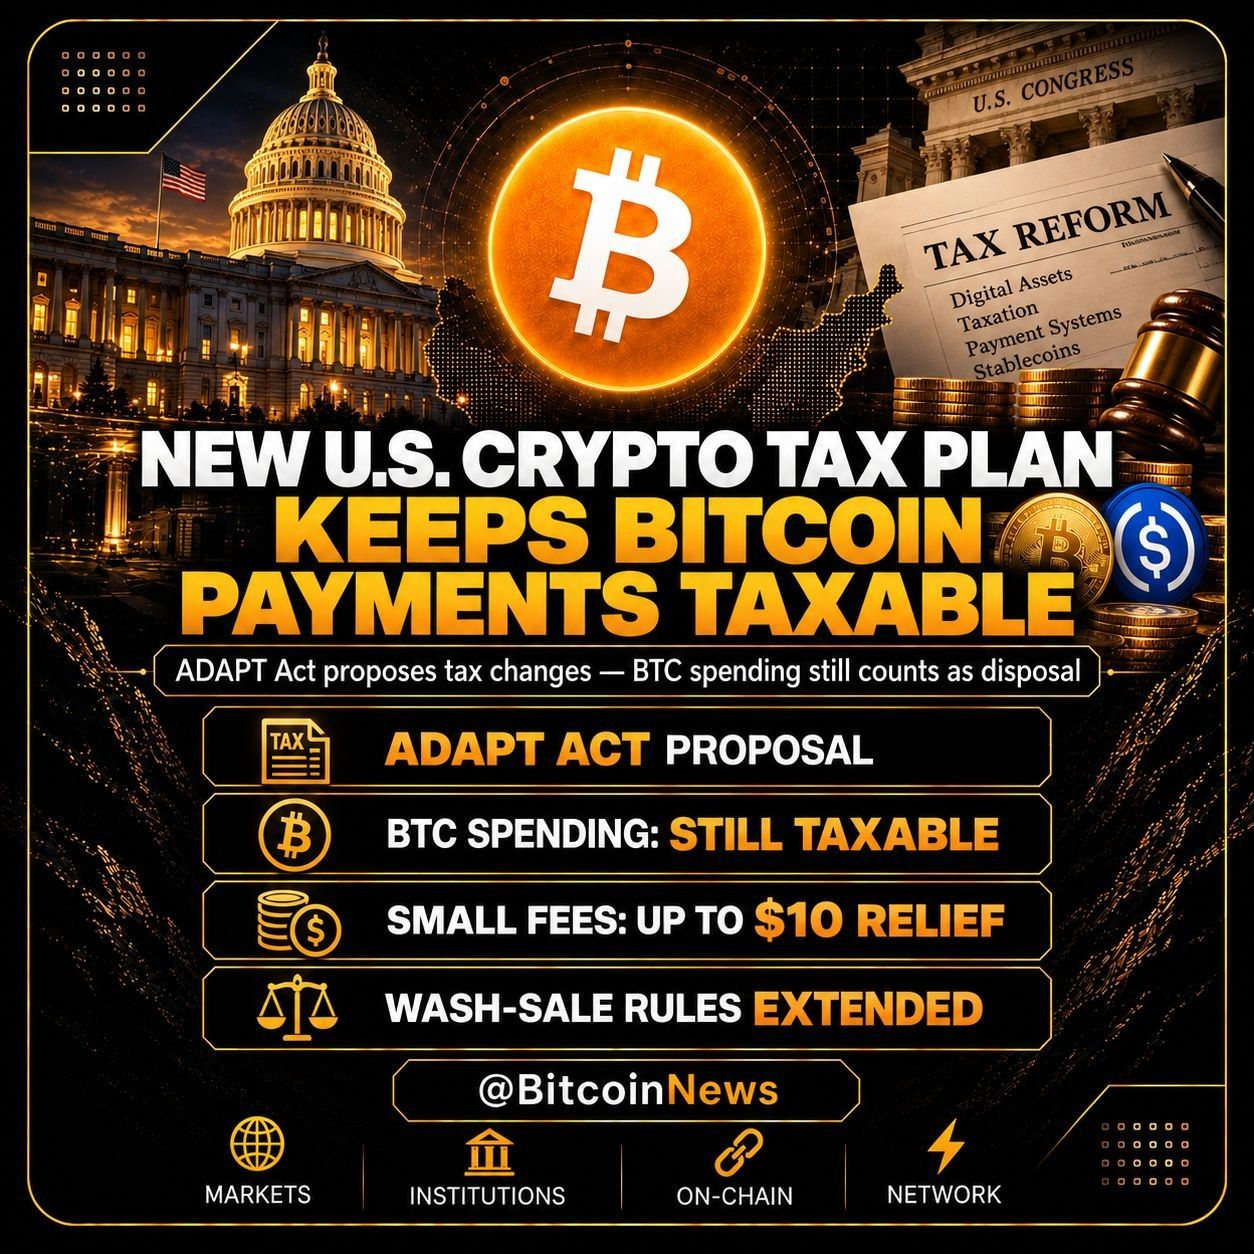
A new proposal from the U.S. Senate could change how digital assets are taxed. The ADAPT Act (Aligning Digital Assets with Principles of Taxation Act), introduced by Senator Steve Daines, includes new rules related to:
• Stablecoin payments
• Network transaction fees
• Wash sales
• Trading
• Staking
• Lending
• Digital asset investment products
One notable point for Bitcoin users is that spending BTC would still be considered a taxable transaction. This means using Bitcoin to buy goods or services could still require calculating capital gains or losses. Meanwhile, qualifying dollar-denominated stablecoin payments would receive more favorable tax treatment.
The proposal also includes a Bitcoin-related exemption: Crypto network fees of up to $10 may avoid triggering the recognition of gains or losses under certain conditions. In addition, traditional wash-sale rules would also apply to digital assets.
It’s important to note that this is only a proposed bill and is not current U.S. tax law. However, the distinction is worth watching as Washington tries to make crypto taxation easier. Still, spending Bitcoin would not receive the broad exemption available to qualifying stablecoin payments, which remains a major obstacle to using Bitcoin as an everyday currency.