



Original | Odaily Planet Daily (@OdailyChina)
Author|jk
Local U.S. time on October 2, “Crypto Mom” Hester Peirce left the U.S. SEC and officially stepped down from her commissioner post. Next, she will head to Regent University School of Law to teach, while behind her the SEC is left with only Chairman Paul Atkins and Commissioner Mark Uyeda—both Republicans. The SEC has officially entered the “two-person era.”
Looking back on these eight years, rather than saying it was a term of office, it was a long, drawn-out debate: starting from a minority position, Peirce became a lone supporter of the encryption industry, gradually turning his own arguments into the early framework of the rules of today’s crypto industry.
Before 2022: One person’s dissent
Peirce was sworn in on January 11, 2018. Previously, she served as a senior legal advisor on the Senate Committee on Banking, and she was also a senior fellow at the Mercatus Center at George Mason University.
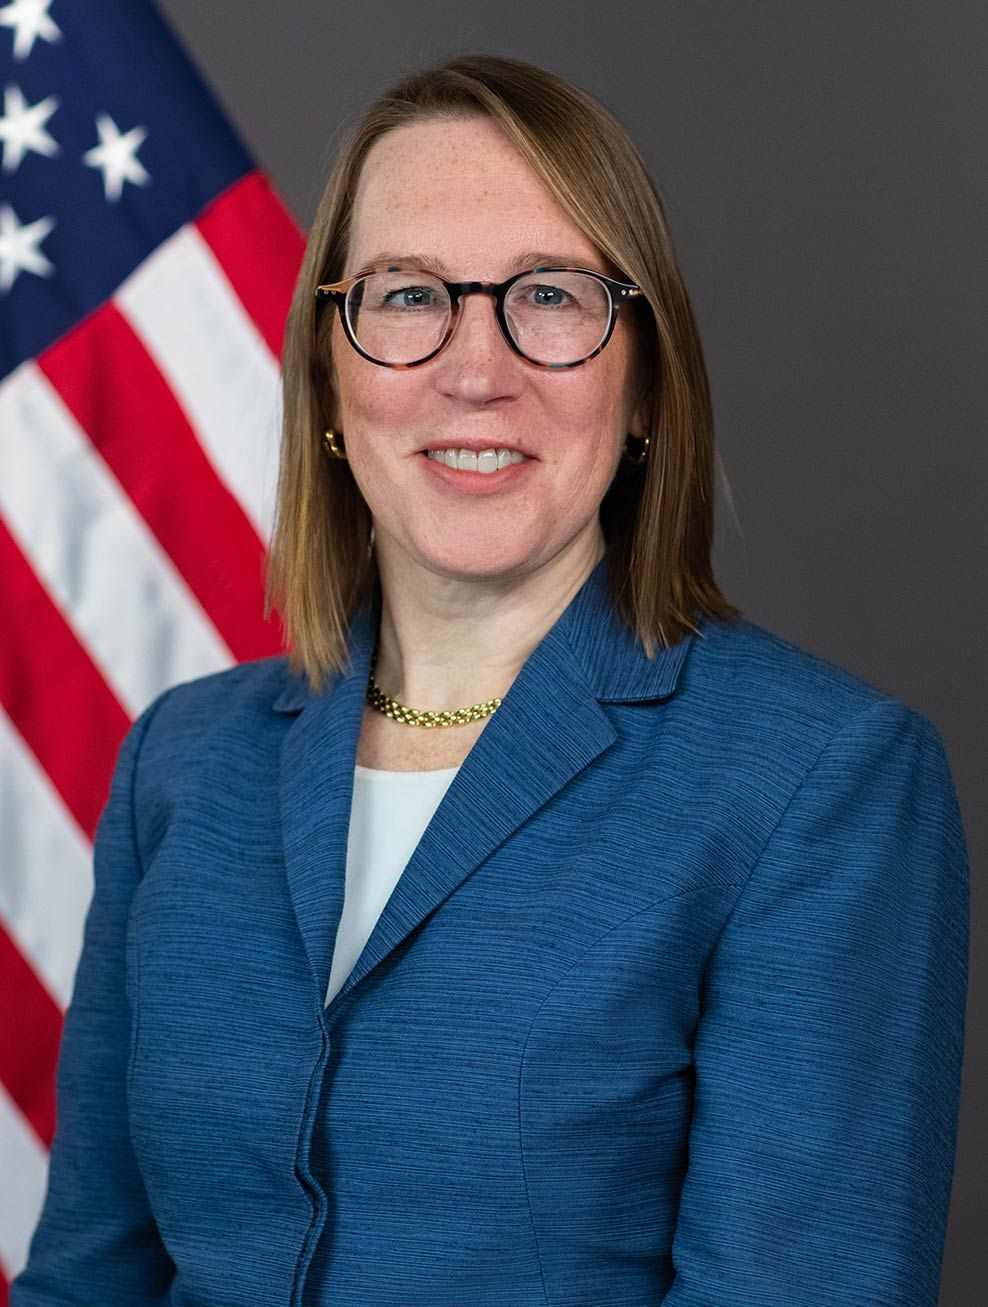
A photo of Hester Peirce on the SEC website, source: SEC
On July 26 of that year, the SEC again rejected the Winklevoss brothers’ Bitcoin ETF application. Peirce immediately issued a dissenting statement, saying that the relevant rule changes were consistent with the Securities Exchange Act of 1934 and, based on precedent, should be approved. The crypto community remembered the dissent and also bestowed upon her the nickname “crypto mom.”
In 2020, she proposed a plan giving developers three years to build functional or decentralized networks, during which the full securities registration requirements would not apply immediately. On April 13, 2021, she issued Safe Harbor 2.0, adding requirements for semiannual disclosure updates and exit reports. The plan ultimately was not adopted by the commission. But it did not disappear—corporate attorneys treated it as a reference framework for the design of token offering structures and repeatedly cited it.
After 2021, Gary Gensler became chair. The SEC did not issue rules targeting token issuances, DeFi protocols, or the registration of crypto exchanges; instead it advanced through enforcement actions. Peirce calls this approach “regulation through enforcement,” and similar criticisms can be traced back to 2020.
It was reported that she dissented in the 2021 DeFi Money Market settlement case, arguing that some of the projects being pursued were failed experiments, not fraud. When the SEC sued companies such as Coinbase, Kraken, Nexo, and Ripple, she publicly questioned whether it was worth putting resources into these lawsuits, and she worried it would crowd out the agency’s other work and set an improper precedent.
A review article in The Defiant argues that, between 2022 and 2023, she was the only person in the commission who supported crypto and also had voting rights, so regulatory practitioners could only rely on reading her dissent in place of official guidance.
2024: Late approval
Bitcoin ETFs are another main thread running through her tenure. In speeches, she criticized the SEC for refusing to engage in constructive communication with crypto users and developers for four straight years, and she added specific hurdles for crypto assets during the ETF approval process.
In 2024, Bitcoin spot ETFs were finally approved. But in her dissent at the time, she focused more on the long period of delay that came before: she argued that the SEC wasted a decade, damaged public trust, consumed staff resources, blurred the agency’s role, and left a generation of product innovators feeling alienated from the SEC. Industry observers say her earlier dissents helped pave the way for this approval, as well as for the SEC’s softened stance toward meme coins and developer activities in 2025. It’s not hard to see why so many people are willing to remember her this way.
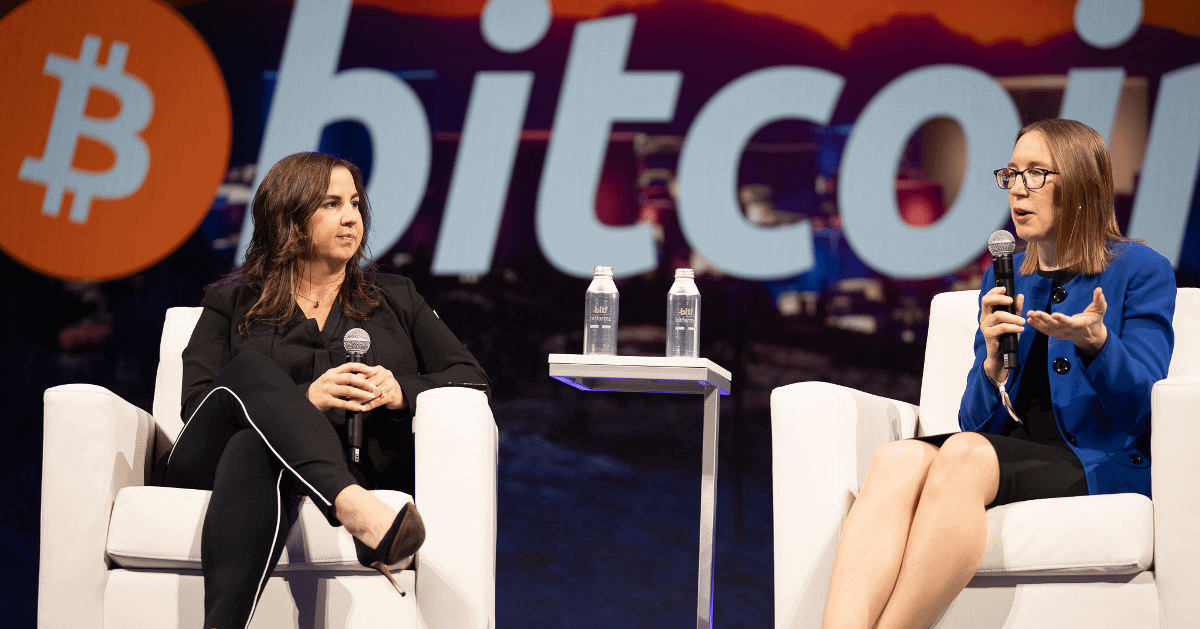
Hester Peirce at a Bitcoin conference
That same year, there was a White House transition, opening up the upper-level pipeline for the crypto industry, and the SEC welcomed a new person to steer the ship.
2025: From minority to steering the ship
On January 21, the Acting Chair Mark Uyeda announced the formation of a crypto working group and appointed Peirce as its head.
When the working group was formed, the SEC’s statement candidly admitted that, until then, it had mainly relied on enforcement to regulate crypto passively after the fact, and that, when it comes to providing workable options for those seeking registration, the SEC “could do better.”
A photo of Hester Peirce attending the meeting
The working group then outlined ten priority areas, including the defining of security attributes and custody arrangements. It held public roundtables, rescinded prior bank custody guidance, and added industry participants to provide input on tokenization and exchange rules. She described herself as a “maximalist of freedom,” and she has also said that many meme coins “probably won’t be within the SEC’s jurisdiction,” urging Congress and the CFTC to address the issue.
During her tenure as head of the crypto working group, the SEC’s enforcement posture toward the crypto industry made a clear shift. In February 2025, the SEC first jointly filed to pause litigation with Binance, then agreed to withdraw its lawsuit against Coinbase, and on February 27 filed a withdrawal request with claims that could not be refiled. On March 3, the SEC also agreed to withdraw its lawsuit against Kraken. Kraken said this outcome did not involve any admission of wrongdoing, any penalties, or any business adjustments. On May 29, the SEC jointly filed to withdraw its case with Binance, similarly with claims that could not be refiled.
According to Bloomberg, in the month leading up to early March, the SEC had withdrawn or stayed at least nine cases against crypto companies. Consensys’ case was also withdrawn, and Robinhood Crypto announced that the SEC had ended its investigation of it. In the withdrawal filings for the Coinbase and Binance cases, the ongoing work of the crypto working group was cited as a reason. While the dismissals were an overall SEC decision and not attributable to Peirce alone, the resolution of these cases not only carried her shadow—it also marked the complete exit of the “regulation through enforcement” approach she had criticized for years.
What she left behind, still unfinished
What has been advocated for years is now becoming documents. Many outside observers believe that the approach behind her safe harbor can already be seen in the SEC’s proposals, exemptions, and guidance. But most of this work is still in progress:
Regulation Crypto Assets (token-issuing rules): On August 18, the SEC proposed the rulemaking. It includes a one-time maximum “startup exemption” of $5 million (within four years), as well as a “financing exemption” of up to $75 million every 12 months, and would no longer treat crypto assets as the subject of an “investment contract.” The proposal would also take priority over states’ registration and qualification requirements. The public comment period would close on October 20. This is the SEC’s first crypto-specific notice-and-comment rulemaking of this type, proposed in writing by Atkins, Peirce, and Uyeda, with no one opposing. In her statement, Peirce said these exemptions and safe harbors cannot fit every model; they are just one step along a long path toward a clear, reasonable, and workable regulatory framework.
Custody rules: On October 1, the SEC issued a custody proposal that, in certain circumstances, would allow investment advisers and regulated funds to hold crypto assets themselves, and could use state trust companies as custodians, provided certain conditions are met.
Modernizing the transfer agent rules: This proposal, introduced on September 1, is the first substantive revision to the transfer agent rules in more than 40 years. It would allow transfer agents to use a blockchain or other distributed ledgers as the record of the main security holder or as part of that record, but it would not mandate such use. If transfer agents use blockchains or handle tokenized securities, the wallet addresses would need to be retained in the records detailing holdings. However, the proposal does not determine whether any particular crypto asset is a security.
Innovation Exemption: On September 17, the SEC issued this temporary, conditional exemptive order allowing eligible tokenized security venues to use NMS stocks traded via automated market makers and liquidity pool trading tokenized. The exemption period is five years, expiring on September 17, 2031. The SEC can shorten, extend, or modify it at any time, positioning it as a “sandbox” to serve as a reference for future rulemaking. First-tier stocks (S&P 500 and Russell 1000 constituents, etc.) are limited to 75 underlying securities, with trading volume not exceeding 0.25% of the average daily volume from the prior month; second-tier stocks are limited to 250 underlying securities, at 2.5%, and only for trading in the secondary market. The SEC also sought public input on the exemption.
The variable factor of the two-person era
Hester Peirce’s second term ended in June 2025. Under the rules, she could continue serving for about 18 more months, meaning she left roughly two months earlier than the term’s expiration.
The SEC that remained had only two commissioners. Rules passed in 1995 allow the commission to continue operating when fewer than three commissioners are present, but with just two people, if a disagreement or recusal arises, matters stall. The White House has not yet nominated a successor, and there is no clear decision on who will take over the crypto working group. At the congressional level, the CLARITY Act is still stuck in the Senate. In the absence of a legislative framework that fully delineates SEC versus CFTC regulatory authority, Regulation Crypto Assets has temporarily become the main vehicle for providing regulatory clarity in the near term. Some industry executives worry that, without legal backing, the rules may be changed by the future administration.
Conclusion
Eight years ago, when Hester Peirce walked into the SEC, crypto still looked like waters without navigational beacons. She brought only one out-of-step kind of stubbornness: when everyone stood on the opposite side of the crypto industry, she kept asking what good rules should actually look like. Thus, a dissent became a pebble, a safe harbor became a sketch, and a long minority stance became a landmark that later comers could repeatedly reference.
What the “crypto mom” left behind in the realm of industry regulation isn’t a completed building, but a drafted blueprint, a few scaffolds just erected, and a path that she walked step by step into existence. The road still has no name; the rules are not fully finalized; no successor has appeared yet—but the crypto waters are no longer as silent as they were eight years ago.