The October 27–28 FOMC is no longer a hike meeting on the data in hand. It is a hold, with December still open. Two prints did that work: August PCE on September 30, and September payrolls on October 2.
Inflation cooled on the month. It did not cool to target.
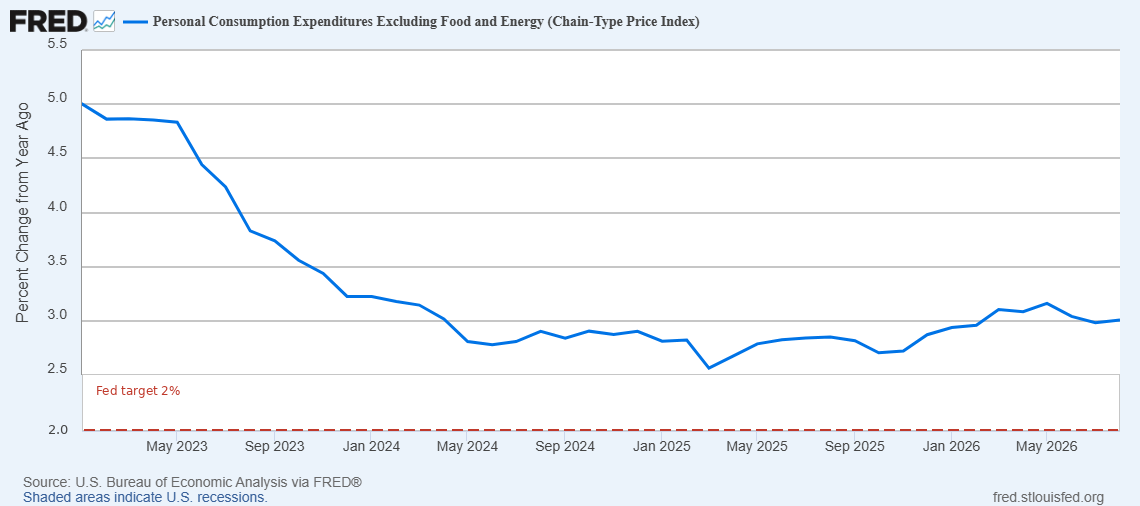
August headline PCE rose 0.3% on the month and 3.4% on the year. Core PCE, the Fed’s preferred gauge, rose 0.2% and 3.0%. Consensus was closer to 0.3% and 3.3% on core. Gasoline drove the headline. Food was flat.
The annual update matters more than the monthly miss. Revisions cut the prior core reading by about 36 basis points. July core, first reported near 3.3%, now sits at 3.0%. Part of the “improvement” is a rewritten history, not a one-month collapse in prices.
Spending did not confirm a demand break. Nominal PCE jumped 0.9%, real PCE 0.6%. Income rose 0.2%. Households spent. They did not get a matching pay rise.
Note: Core PCE is back at 3.0% after the revision. That is still 100bp above the Fed’s target. Source: BEA via FRED.
Core at 3.0% is 100 basis points above 2%. The next PCE, for September, is due October 29, the day after this meeting. The Committee will not have it.
The labor market is what took October off the table.
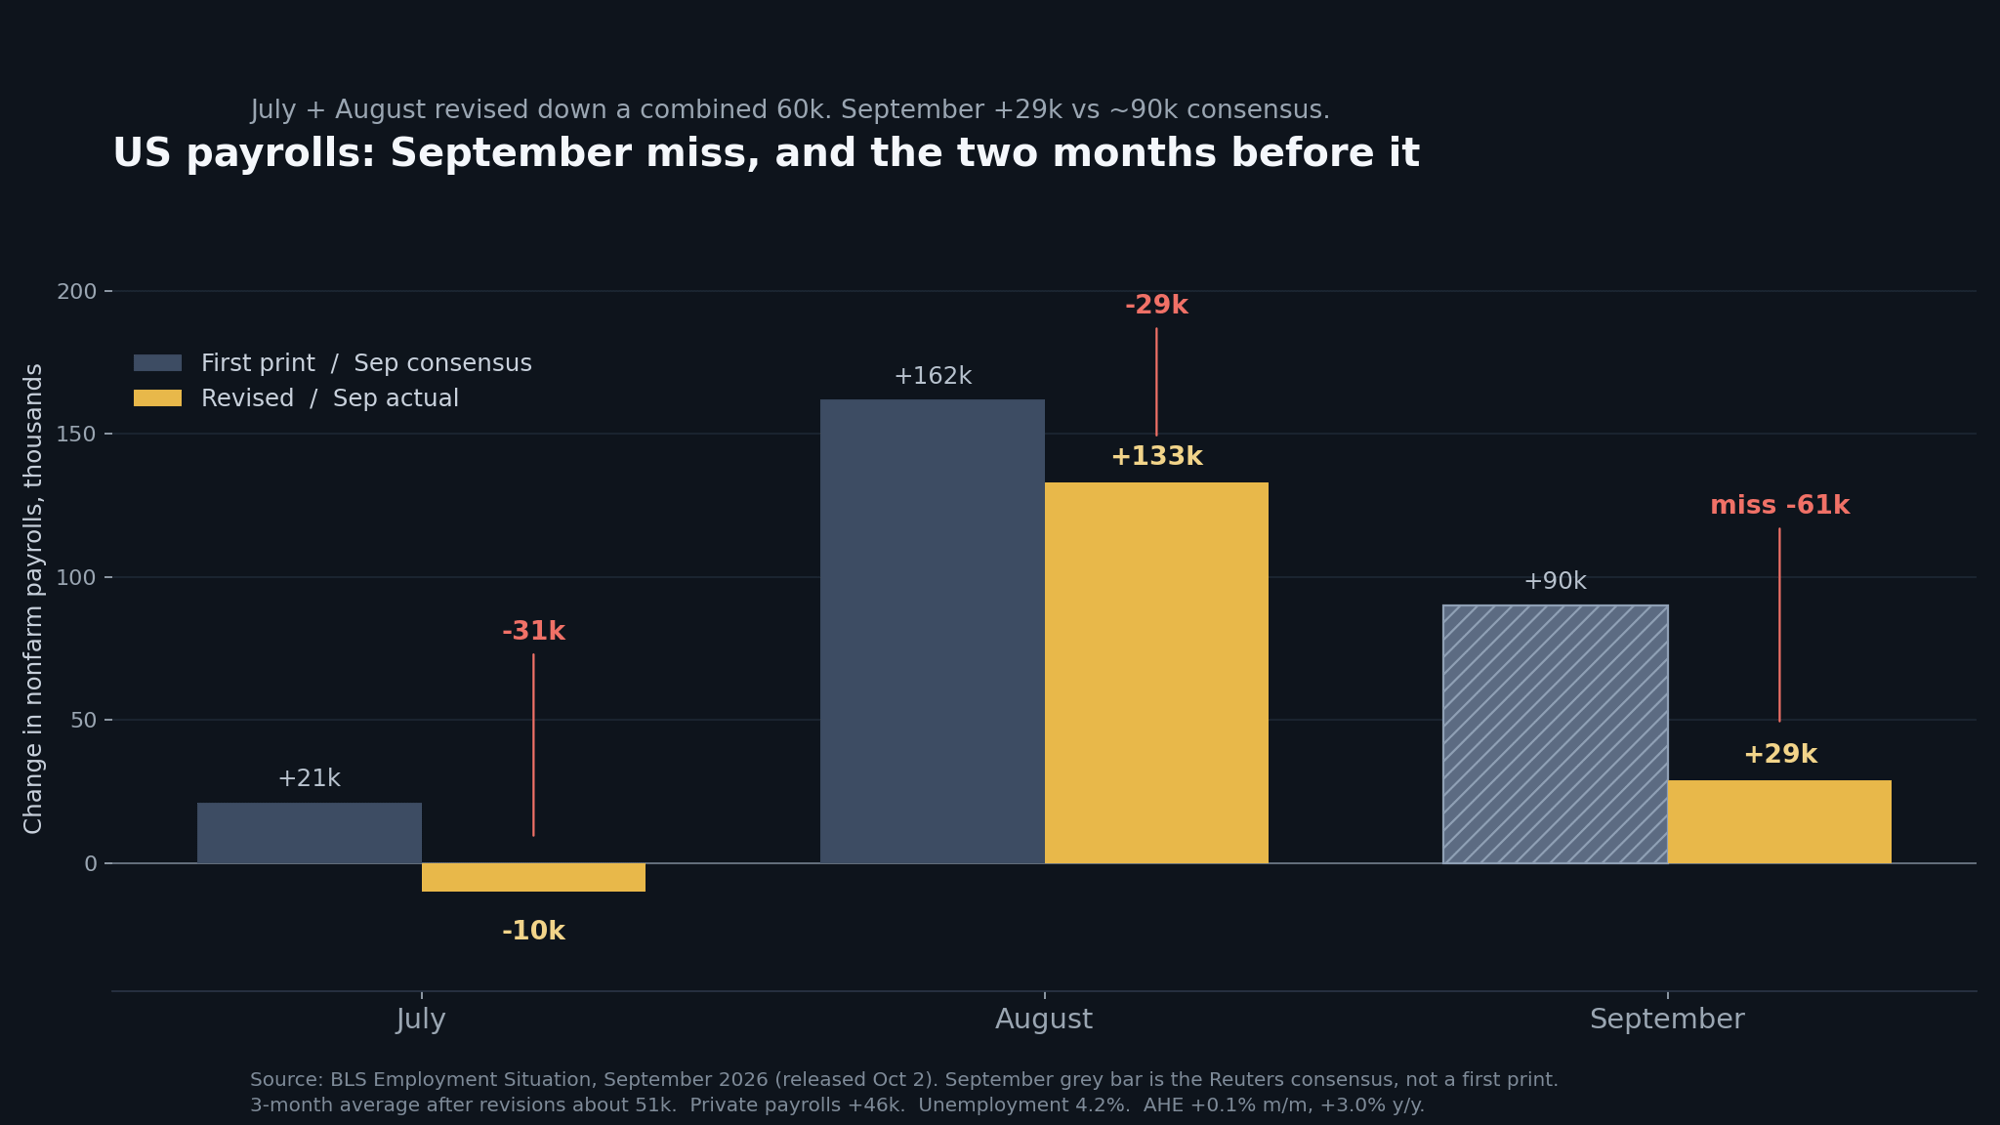
September nonfarm payrolls rose 29,000 against a consensus near 90,000. Private payrolls were +46,000. Government was −17,000. July and August were revised down by a combined 60,000. July is now −10,000. August went from 162,000 to 133,000.
Note: September +29k versus ~90k expected. July and August were revised down 60k combined. Source: BLS, October 2.
Unemployment rose to 4.2% from 4.1%. Unrounded it is 4.175%. Participation rose to 61.8% from 61.6%, and household employment rose 406,000. People entered the labor force faster than they found jobs. That is a softer print, not a break.
Wages are the clean part of the report. Average hourly earnings rose 0.1% on the month and 3.0% on the year, the slowest annual pace since 2021. The wage channel into core PCE is no longer the problem.
What the Committee walks in with
September already delivered the hike, to 3.75–4.00%. Sixteen of eighteen officials, in the last projections, still wanted at least one more increase this year. That was the setup before these two prints.
PCE took the urgency out of inflation. NFP took the urgency out of October. CME FedWatch odds of an October hike, near 70% on September 24, were about 37% after PCE and about 23% after the payrolls miss. The intraday low was near 13%. December is still the live meeting.
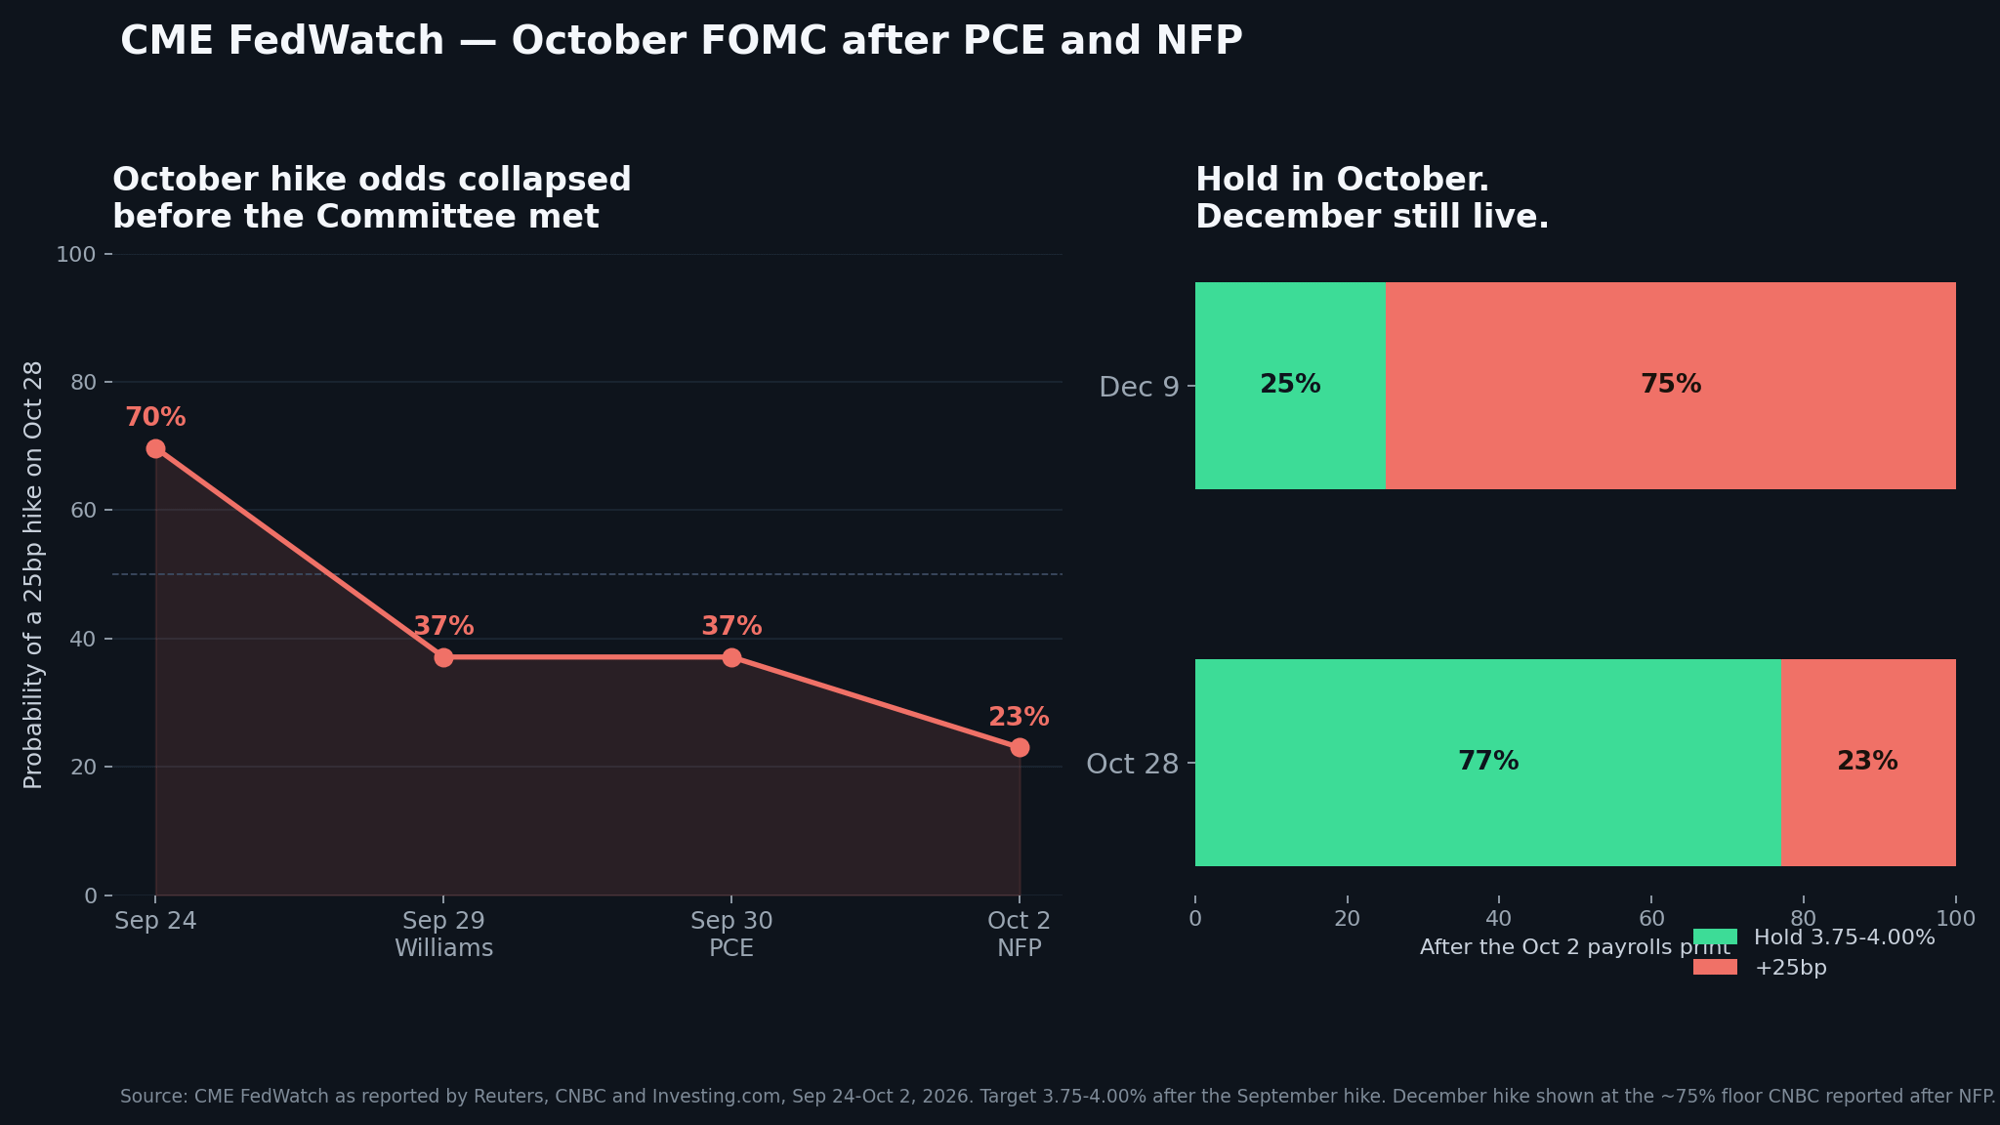
Note : October hike odds fell from ~70% to ~23% after the two prints. December is still priced near 75%. CME FedWatch as reported by Reuters and CNBC, not an official screenshot.
The constraint is the calendar. September CPI lands before October 28. A hot CPI can put a hike back on the table. A second soft inflation print locks the hold and pushes the argument to December.
The cross-asset tell
The front end is the tell, not the payroll headline. The 2-year yield peaked near 4.97% before the data, then fell to about 4.79% on the NFP candle and closed the week at 4.827%. DXY did not give the move back. It finished at 101.92. Gold sold off into the yield spike, bounced, and failed again after the payrolls print, last at 4,140.
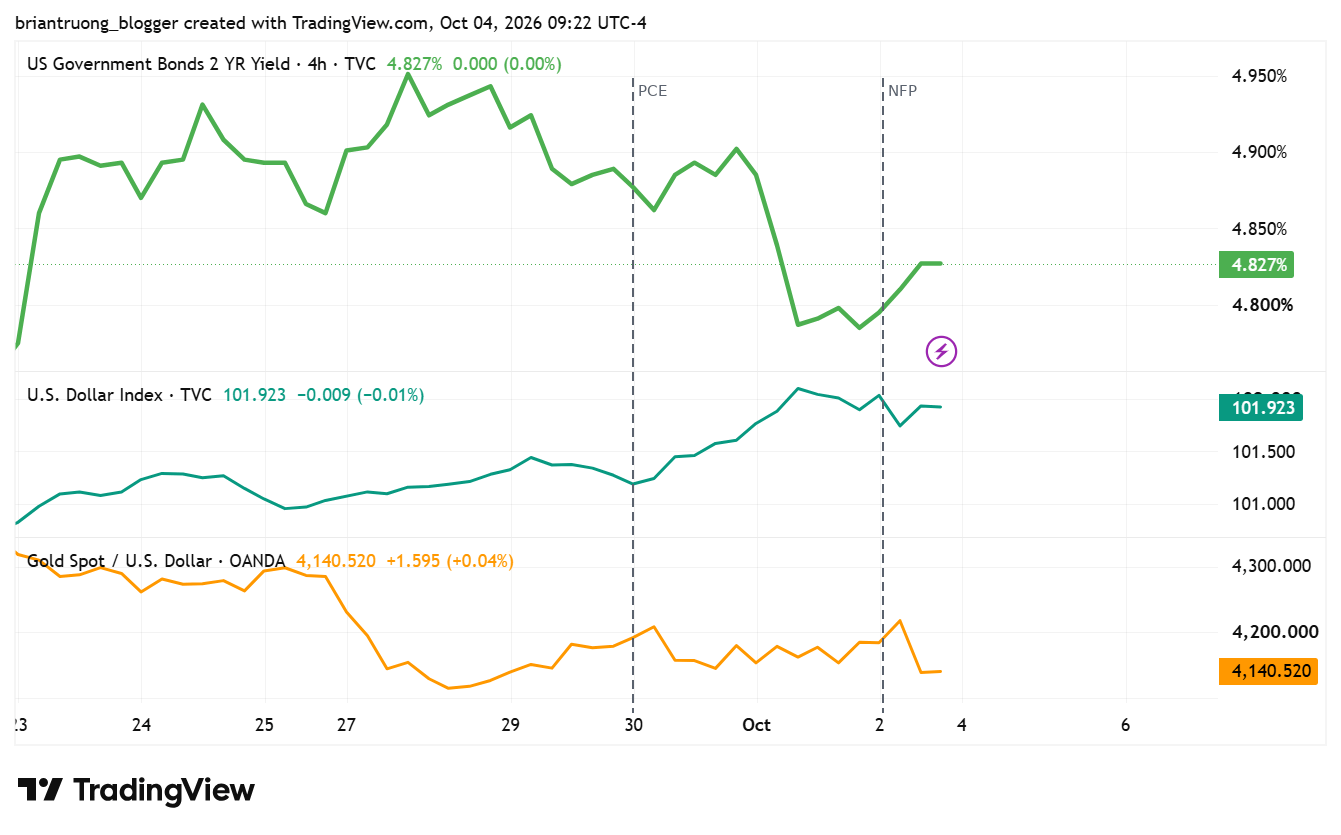
Note : 4H. The 2-year broke on the NFP print. The dollar did not. Gold traded the yield, not the headline.
A hold with core still at 3% is a range for gold, not a trend. A hot mid-October CPI reopens the hike and is the cleaner downside for XAU. Bitcoin does not have an independent variable here. It follows the dollar and real yields into the meeting.
Three paths into October 28
Base case: hold at 3.75–4.00%. The statement keeps December open. Inflation is still above target. Labor is no longer overheating. This is what PCE and NFP currently support.
Hawkish hold: hot September CPI, unemployment steady, wages not re-accelerating. December hike odds move back up. The front end sells off. Gold gives back the post-NFP bounce.
Dovish hold: CPI confirms the PCE miss, and claims or a soft retail print show the 29,000 was not a one-off. December odds fall with October. That is the only clean dollar-down, gold-up path, and it is not the base case on today’s data.
Cash is a position into CPI. The two prints already answered October. They did not answer December.
Not financial advice. Levels move with the next CPI.
BRIAN TRUONG
TRADE $XAU HERE👇