Has the October rate hike gone? Don’t pop the champagne yet—it’s just been moved to December
Last Friday, a jobs report sent markets into chaos: September new jobs were only 29,000 versus expectations of 90,000; the unemployment rate rose to 4.2%; wage growth (hourly earnings) hit the slowest pace since 2021, and the totals for the prior two months were revised down by 60,000
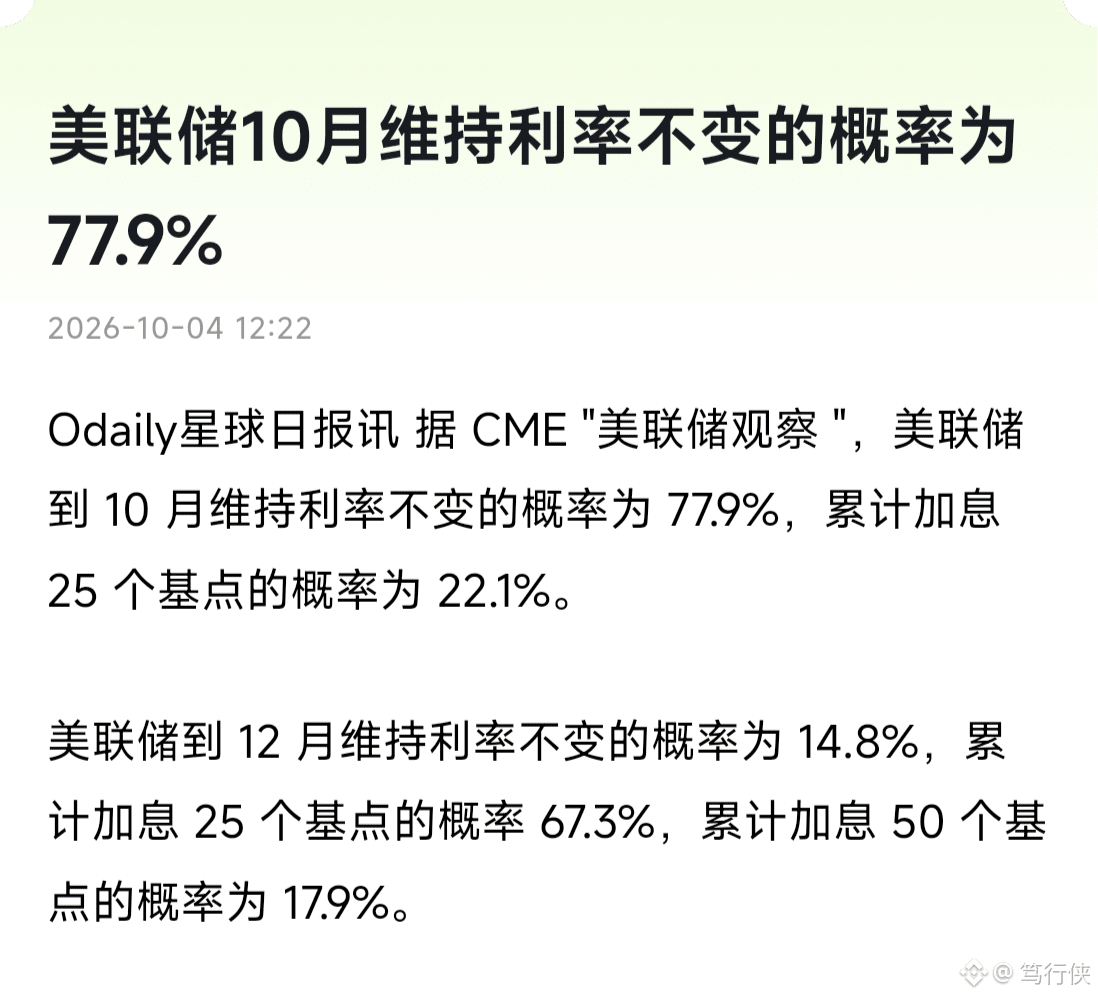
Interest-rate markets immediately flipped: the probability of an October hike was cut from 28% to 17%, while the odds of holding steady rose to 83%
In plain English: the Fed meeting on October 28 is very likely just a pond with no ripples
The Nasdaq hit a new intraday all-time high, gold jumped sharply, and crypto finally caught its breath
But the most anti-consensus moment was in the bond market: after the jobs report, U.S. Treasury yields first fell to 5.16%, then rebounded to 5.26% the same day, continuing to hover near the 5.3% 2024 high
In plain English: the bond market doesn’t believe “tightening is over” at all
Why? Because it’s not that the market is canceling rate hikes—it’s rescheduling them. Under the CME measure, the probability of a December hike is still above 75%.
In plain English: the faucet isn’t turned off—it’s just been loosened by half a turn
The real roadblock has never been employment, though: core PCE is still sitting at 3%, far from the 2% target; fighting in the Middle East pushed U.S. oil prices to a record $6.53 per gallon. The G7 even urgently released 100 million barrels from reserves, and Goldman’s calculations suggest it can only offset about half of the increase
U.S. 10-year Treasury performance in Q3 recorded the largest quarterly gain since 1994—this account can’t be settled until either inflation or fiscal issues are resolved, and not in a single day
For retail investors, two takeaways:
Short-end dovish repricing bought risk assets a breathing window—new Nasdaq highs and crypto rebounds both matter;
But don’t equate “no October hike” with “the cycle is over”—the real exam is September CPI before the FOMC (Oct 27–28)
The end of the rate-hike phase isn’t here yet—it’s just that the pace has slowed
Your question: for December, do we step on the gas—or not?
(Not investment advice, for reference only)
#美联储10月加息概率降至17%