

Over the past 24 hours, after a week of intense volatility, global financial markets have entered a new repricing phase again.
The biggest variable in the market is that the U.S. September nonfarm employment report came in far below expectations.
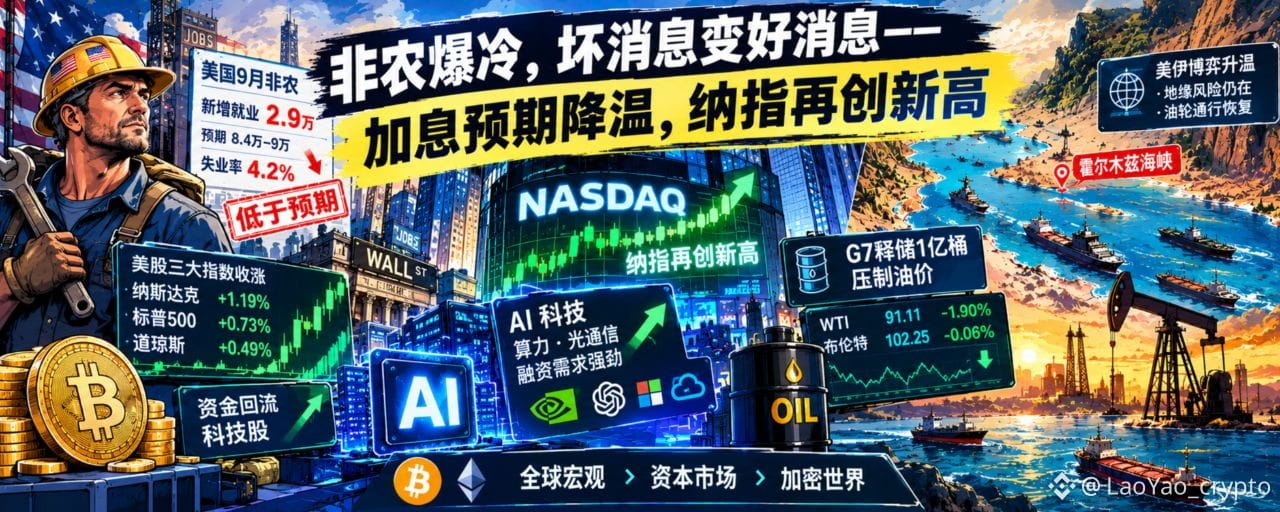
In September, nonfarm payrolls increased by only about 29,000, significantly below market expectations. The unemployment rate rose to 4.2%, and employment data for the prior two months was further revised downward.
A clear cooling in the labor market led the market to rapidly scale back expectations that the Fed would deliver another rate hike in October.
Poor jobs data → lower expectations for further rate hikes → U.S. Treasury yields fall back → technology stock valuations recover → risky assets rebound.
— Nasdaq sets a new intraday all-time high again.
Meanwhile, the G7’s announcement of strategic oil releases has pushed down crude oil prices; but as U.S.-Iran relations heat up again, it also limits further downside for oil prices.
The capital markets are simultaneously trading three main themes:
Cooling U.S. employment, global energy risks, and high interest rates in the medium to long term.
🧱 Geopolitical games:
① U.S.-Iran relations warm up again, and energy risks resurface
Iran says that if sanctions are relaxed, it can allow inspectors to enter.
Meanwhile, the U.S. plans to deploy a third aircraft carrier strike group to the Middle East and up to about 10,000 troops.
Reports say Trump is considering resuming airstrikes on Iran after the U.S. midterm elections.
Meanwhile, Saudi Arabia is planning military actions against Yemen’s Houthis to ease the pressure on Red Sea shipping.
Although tanker traffic through the Strait of Hormuz is recovering, geopolitical risks in the Middle East energy supply chain haven’t disappeared.
Oil prices are being pulled in two directions:
On one side, the G7 releases reserves to lower expectations of supply tightness;
On the other side, the Middle East situation continues to provide a risk premium.
② G7 releases 100 million barrels of strategic reserves, trying to push down energy prices
G7 countries announced they will inject up to about 100 million barrels of strategic reserves of crude oil and diesel into the market to ease supply tightness caused by an escalation in Middle East developments and damage to Russia’s energy infrastructure.
Trump also confirmed that, for now, it won’t implement an oil export ban.
After the news was announced, oil prices briefly fell sharply, and Brent crude temporarily broke below $100.
But afterward, the market started reevaluating the actual release size, the rollout timetable, and Middle East risks—so the magnitude of the oil price decline narrowed.
Reserve releases can ease short-term supply pressure, but they may not eliminate the geopolitical risk premium.
③ Nonfarm surprises: Why does bad news become good news?
In September, U.S. nonfarm employment increased by only about 29,000, far below the market expectation of about 84,000–90,000.
The unemployment rate rises to 4.2%, and employment data for July–August are revised down at the same time.
The market therefore quickly lowered expectations for the Fed to hike again in October.
and the capital markets respond accordingly:
U.S. Treasury yields spike and then fall back → technology stock valuations recover → major U.S. stock indexes rise.
💹 Capital mapping: The market recalculates the “interest-rate ceiling”
After a nonfarm surprise, what the market is trading isn’t just whether “employment is good or bad,” but:
Can the U.S. economy truly withstand long-term borrowing costs above 5%?
The weaker employment is, the less room the Fed has to keep tightening monetary policy.
The market isn’t hoping for a U.S. recession,
But at this stage, what capital worries about more is—
Inflation re-accelerates, forcing the Fed to keep even maintaining or raising high interest rates.
So as long as the cooling in employment hasn’t turned into an economic slowdown, the market may interpret it as:
“A good message in bad news.”
📊 Bond market: Long-end yields remain high
10-year U.S. Treasury: 5.24%;
30-year Treasury: 5.62%;
2-year U.S. Treasury: 4.72%;
Japan 10-year JGBs: 3.05%;
U.S. Treasuries have pulled back from their 2024 highs, while Japanese government bonds continue to stay near the ~30-year high.
After the nonfarm data was released, Treasury yields fell back, but yields on the long end remain at high levels.
This means:
The market reduced short-term rate-hike expectations, but it hasn’t truly escaped the “high interest rate era.”
Especially when 30-year U.S. Treasuries are still at extremely high levels.
What’s really worth watching isn’t whether a single nonfarm release can change the market, but:
Whether the U.S. economy can bear such high financing costs over the long term.
📈 U.S. stocks: AI regains valuation support
Nasdaq: +1.19%
S&P 500: +0.73%
Dow Jones: +0.49%
After employment cooled off, Treasury yields fell back again, giving high-valuation tech stocks new breathing room.
AI computing power, optical communications and other sectors strengthened, and the Nasdaq again set a new intraday all-time high.
At its core, the market is still trading:
Rate-cut expectations → lower discount rates → valuations of AI growth assets regain support.
But this doesn’t mean financing risks for AI assets have disappeared.
What truly determines the next phase of the AI cycle is still:
Can AI earnings ultimately cover the continuously rising capital expenditures and financing costs?
🛢️ Crude oil: G7 releases reserves collide head-on with Middle East risks
WTI: $91.11 per barrel, -1.90%
Brent: $102.25 per barrel, -0.06%
After the G7 release message was announced, oil prices briefly fell sharply.
but as the market reassesses the reserve-release size and execution pace, and as geopolitical risks such as U.S.-Iran tensions and the Red Sea persist, the extent of the oil-price decline has narrowed significantly.
So the current crude oil market is, in practice:
Supply release pushes down oil prices VS geopolitical conflict raises the risk premium.
Who gets the upper hand will directly affect global inflation expectations in the next phase.
🥇 Precious metals / FX: The market starts looking for balance again
Precious metals have pulled back significantly this week; today they continue to weaken slightly.
The dollar falls, and the yen gets a brief breather.
Although the nonfarm data reduces expectations for further rate hikes, the market does not believe the U.S. has entered a sustained easing cycle.
In other words:
Monthly employment data changes short-term expectations,
but not enough to change the broader environment of “high interest rates.”
🤖 AI: Safety and regulation are becoming another hidden thread
OpenAI has recently laid off multiple researchers involved in internal safety and model evaluation compliance issues.
Meanwhile, U.S. regulators are also paying attention to AI safety, competition, and compliance issues at companies such as OpenAI and Anthropic.
This means the AI industry is entering a new stage:
From a “model capability race,” gradually into an all-round competition of “capability + safety + regulation + commercialization.”
After the AI cycle truly enters its next phase, the market won’t focus only on model parameters and the scale of computing power, but on:
Who can turn AI capabilities into sustainable business cash flows.
💸 Web3 roundup: Money concentrates on leading players
Over the past 24 hours, the crypto market has been consolidating in a high range with reduced volume. Nonfarm data drove BTC higher in the short term; after the favorable news was realized, funds took profits and fell back. The structure is “leaders hold up better, smaller coins weaken,” and liquidity hasn’t fully rebounded.
Total market cap: ~2.94 trillion USD; 24H trading volume: ~107 billion USD
$BTC : About 86.8K, topping out at 87,229; market share 59.88%, slightly up
$ETH : About $2,760, up with the move but with less strength than BTC. Funds prefer BTC’s macro-hedging attributes; ETH lacks catalysts in the short term
BTC is still clearly outperforming ETH, and the logic behind it isn’t complicated:
In periods of higher macro uncertainty, funds are more inclined to allocate to leading assets with stronger liquidity and macro-trading characteristics.
Macro expectations recover → BTC benefits
Liquidity hasn’t fully rebounded → altcoins face pressure.
🧘 Crypto “mind learning”: Why does the market like “bad news”?
Why does the market get happier when U.S. employment data worsens?
Because capital markets are never simply driven by “buying good news and selling bad news.”
What the market is truly trading is whether this news will change the future price of capital.
Employment is the most direct window into the U.S. economy.
If cooling employment means the economy is running into a slowdown, then of course that’s bad news.
But if employment merely returns from an overheated state to normal, then it actually implies:
The Fed doesn’t need to keep hiking rates.
Cooling employment:
→ Rate-hike expectations fall
→ Treasury yields fall back
→ Cost of capital declines
→ Valuation repair for risk assets.
That’s the classic line from financial markets: “Bad news is good news.”
But there’s an even deeper layer here:
- The G7 releases strategic reserves to lower energy prices;
- U.S.-Iran relations rise again, lifting geopolitical risk;
- Energy prices determine inflation expectations;
- Inflation expectations determine Fed policy;
- Fed policy determines global cost of capital;
- The cost of capital ultimately determines asset valuations.
So what’s truly worth paying attention to is a chain of capital transmission:
Geopolitics determines the energy risk premium
↓
Energy determines inflation expectations
↓
Inflation determines interest rates
↓
Interest rates determine the cost of capital
↓
The cost of capital ultimately determines asset valuations
As for BTC, it still sits at the end of this global capital transmission chain.
⚠️ The above is personal opinion, for observing and discussing the market only.
Geopolitics is changing quickly—watch position sizing and leverage risk; this is not investment advice.
📌 LaoYao (@LaoYao_crypto )
Use mind learning to observe capital, and use the cycle to judge trends;
Find certainty in uncertainty, and anchor value amid volatility.