Accenture Q4: Orders are higher than revenue, guidance unchanged
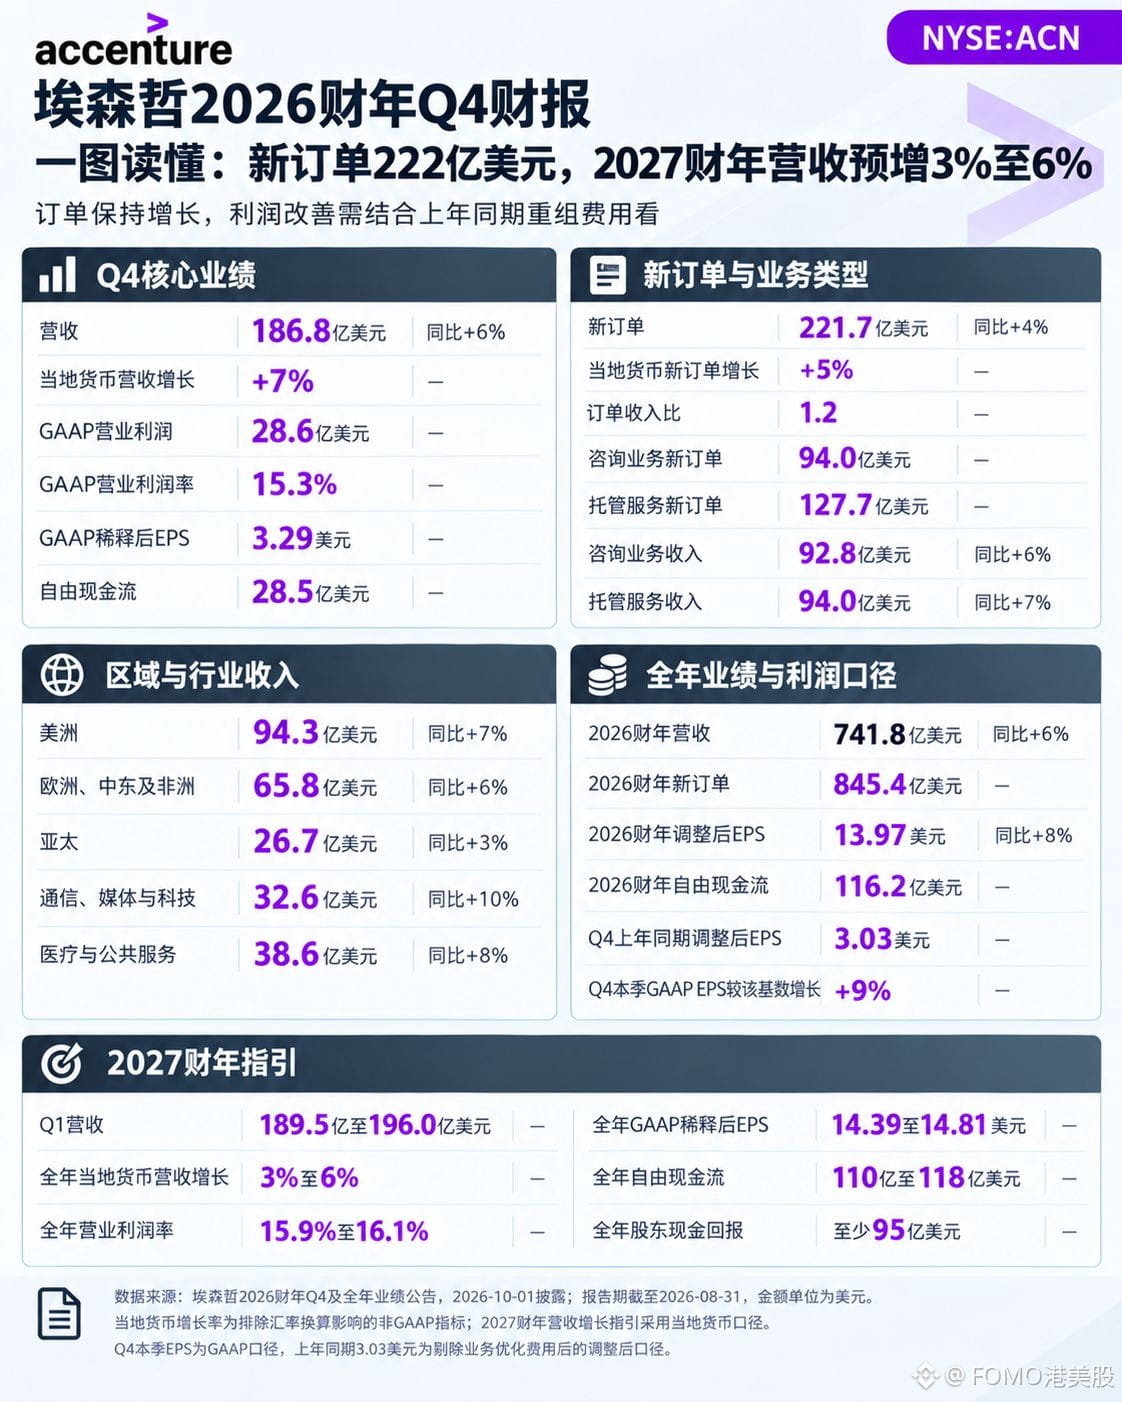
Accenture $ACN Q4 revenue was $18.68 billion, up 6% year over year, exceeding the top end of its own guidance; new orders were $22.17 billion, higher than revenue for the quarter. But its FY2027 revenue guidance remains local-currency growth of 3% to 6%.
Don’t rush to look at the year-over-year EPS yet. This quarter’s GAAP diluted EPS was $3.29 versus $2.25 in the prior-year period, up 46%; however, the prior year included business optimization costs—excluding them, EPS was $3.03, so on that comparison it’s only up about 9%. Once the base changes, the conclusion changes. The same goes for the profit margin: 15.3% versus 15.1% for the prior year, adjusted.
The business picture isn’t narrow. Consulting revenue was $9.28 billion, up 6%, and managed services was $9.40 billion, up 7%. In the Asia-Pacific region, USD growth was only 3%, while in local currency it was 7%. Exchange rates “ate” four percentage points. Full-year free cash flow was $11.62 billion, higher than $10.87 billion last year.
Going forward, what I’m watching is the speed at which orders convert into revenue. The order-to-revenue ratio was 1.2, and the backlog is enough; but what determines whether next year lands on the 3% or 6% end is whether Asia-Pacific and consulting can drive their growth rates higher. I tend to view the Q4 cash flow decline as seasonal and will reassess next quarter.
The above is a compilation of public information and does not constitute investment advice.
#埃森哲 #美股财报季来袭 #企业服务