MARKET WATCH | Crypto, Tokenization, AI and Wall Street enter the same playing field
The market began October showing that crypto and the traditional market are becoming less and less separated. Bitcoin, technology stocks, interest rates, artificial intelligence, and tokenized assets are reacting to forces that, until recently, seemed to belong to different markets.
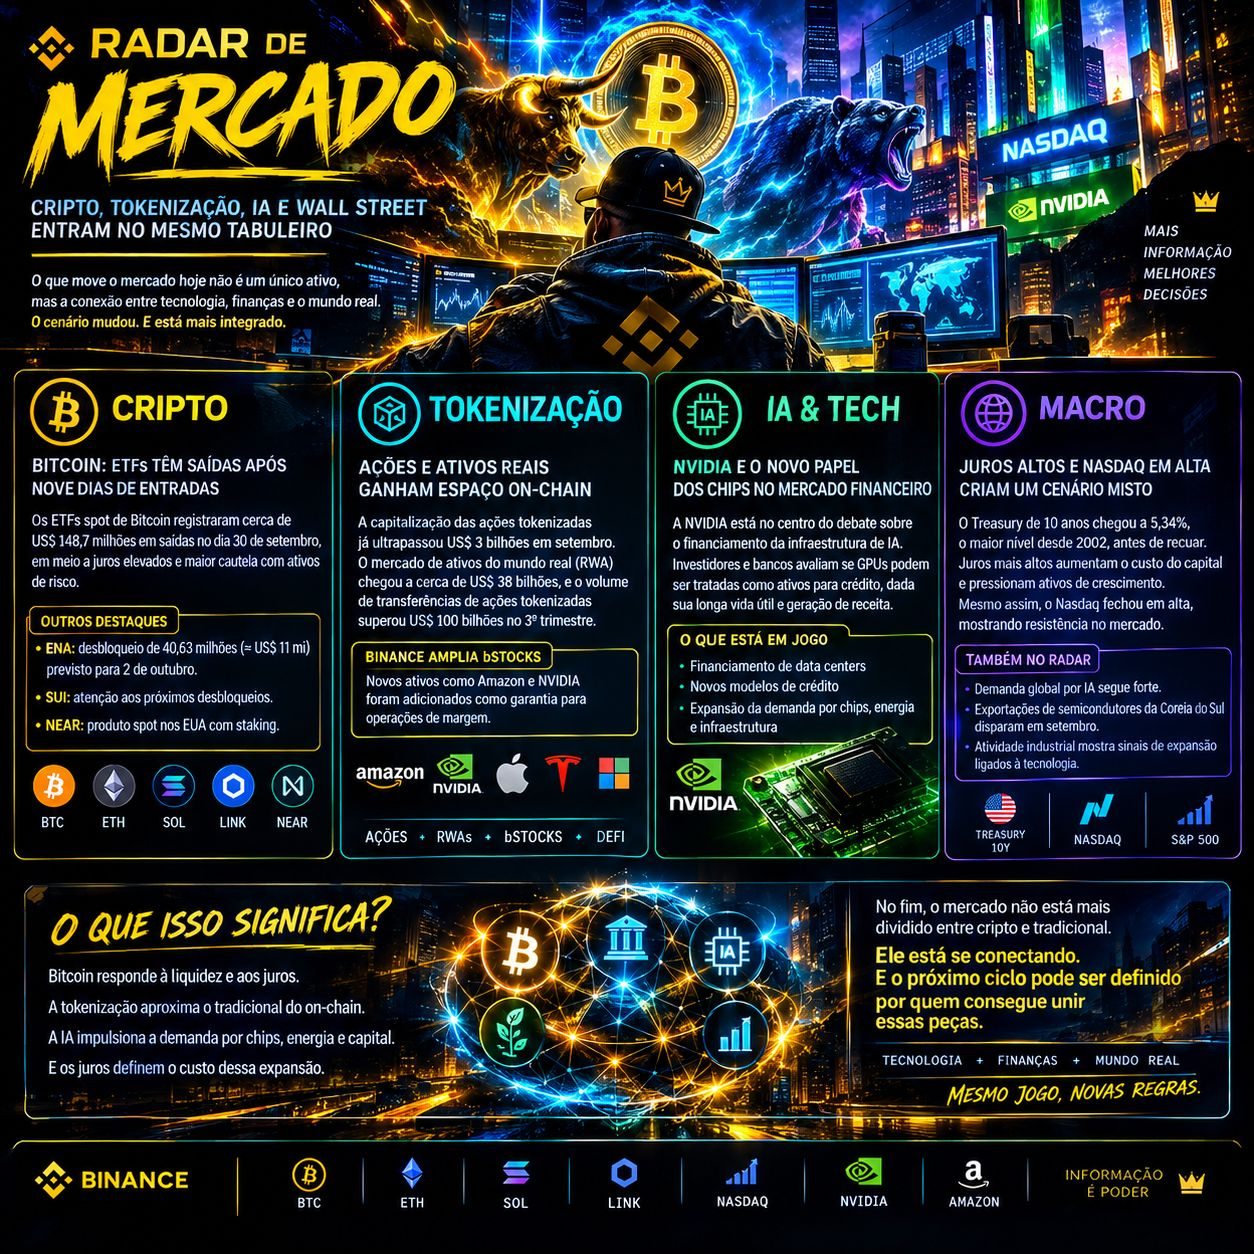
In the crypto universe, Bitcoin went through a change in spot ETF flows. After a streak of nine sessions of inflows, the products recorded outflows of approximately US$148.7 million on September 30. The move is happening in an environment of high long-term interest rates and greater caution with risk assets.
Among the altcoins, some events deserve special attention. For example, Ethena is facing an unlock of approximately 40.63 million ENA, estimated at about $11 million, scheduled for October 2. The market has already been reacting ahead of the event, again showing how unlock calendars can affect liquidity and participant behavior.
SUI also remains on the radar because of the upcoming unlocks, while NEAR gained institutional attention after the launch in the United States of a spot product with exposure to the asset and staking.
But perhaps the most interesting transformation is happening in another area: tokenization.
According to data analyzed by Binance Research, the market capitalization of tokenized stocks surpassed $3 billion in September. The broader market for tokenized real-world assets reached approximately $38 billion. In the third quarter, transfers of tokenized stocks exceeded $100 billion.
This change is important because the blockchain begins to carry not only assets created within the crypto market itself, but also digital representations of companies and traditional financial instruments.
Binance itself has recently expanded its bStocks structure, adding new tokenized stocks as collateral assets for margin operations. Among the assets available in the structure are companies like Amazon and NVIDIA.
And NVIDIA appears on another important front.
The company is involved in an ever-growing discussion about financing artificial intelligence infrastructure. One of the questions raised by banks and investors is whether AI chips can be treated as assets capable of supporting credit operations.
NVIDIA argues that its computing systems have a much longer useful life and higher productivity than traditional equipment. Financial institutions, however, still use more conservative criteria to evaluate depreciation and residual value.
The debate is bigger than NVIDIA itself.
If computing infrastructure begins to be treated as a financial asset class, that could change how data centers, GPUs, and computing capacity are financed.
And there is also the macroeconomic component.
The U.S. 10-year Treasury reached approximately 5.34%, the highest level since 2002, before pulling back. Higher rates increase the cost of capital and can pressure both growth stocks and assets considered more risky.
At the same time, global demand for AI infrastructure remains strong. South Korea’s semiconductor exports surged in September, while industrial activity across different regions showed expansion signals tied to demand for technology and artificial intelligence.
So what we’re seeing, therefore, are not isolated stories.
Bitcoin responds to liquidity and interest rates.
Tokenization brings stocks and traditional assets closer to on-chain infrastructure.
Artificial intelligence increases demand for chips, energy, data centers, and capital.
And interest rates determine how much it costs to finance this expansion.
Maybe the market’s most significant shift is right there: the boundaries between technology, traditional finance, and blockchain are becoming increasingly difficult to separate.
The next cycle may not be defined only by which asset goes up the most.
It may be defined by which infrastructures can connect these different markets.