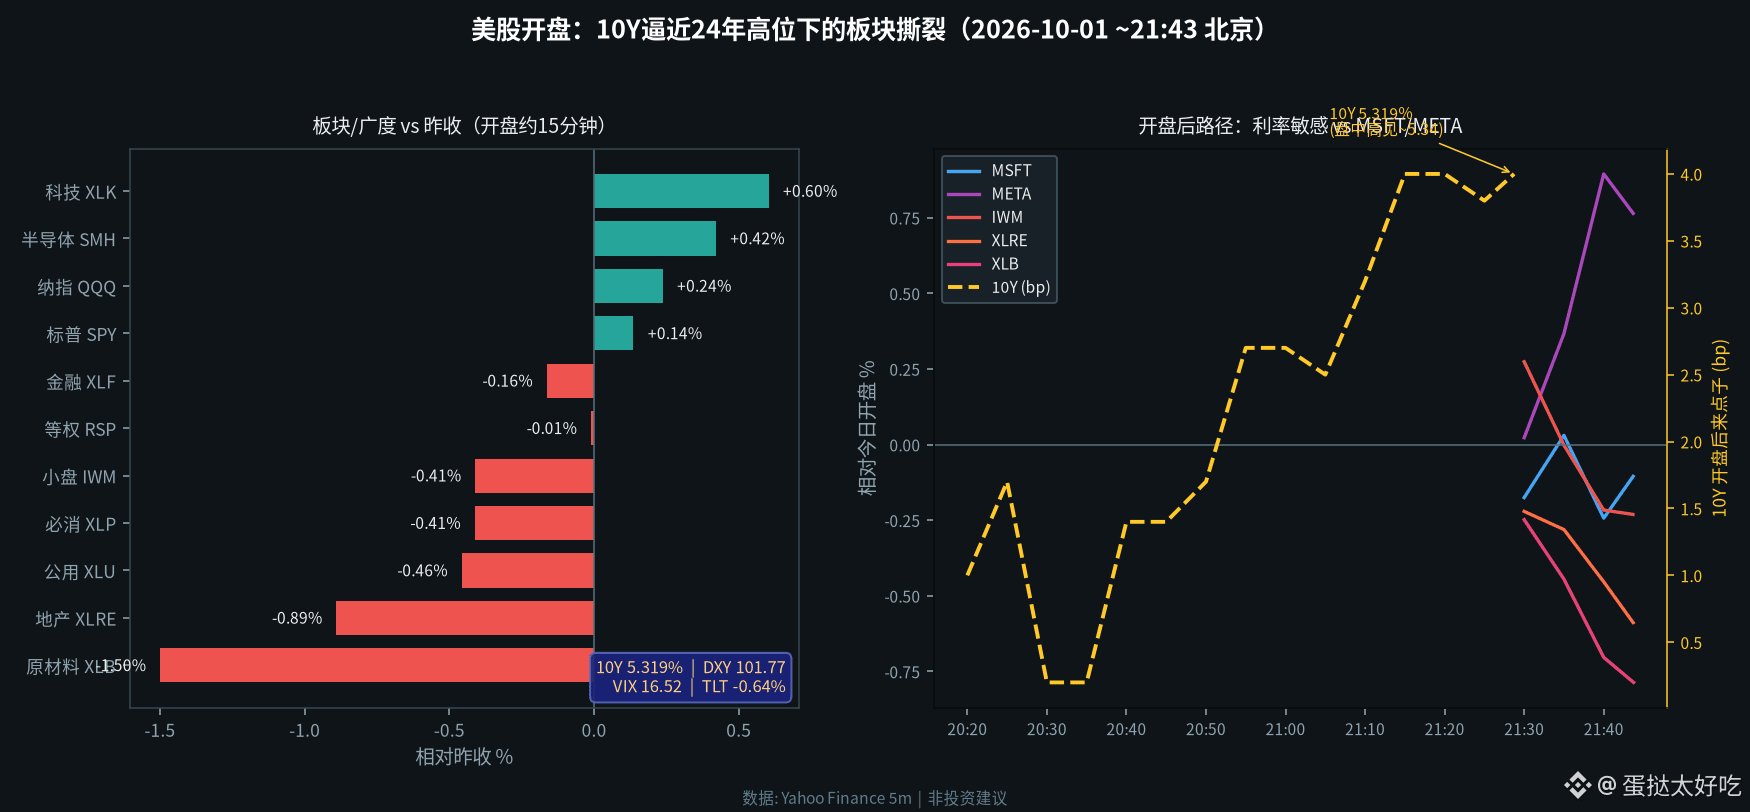
The 10-year U.S. Treasury yield touched about 5.32%—roughly a 24-year high, yet the index is still in the red: this isn’t a broad liquidation—rates are picking winners among sectors.
The cash market’s been open for about a quarter of an hour: 10Y is currently 5.319% (about +5 bps vs. the prior close, rising after the open; intraday high around 5.34%). The U.S. Dollar Index is around 101.77 (+0.3%), long-duration Treasuries (TLT) are -0.64%, and the VIX is up to 16.5. Rate-sensitive areas immediately showed it: materials XLB -1.5%, real estate XLRE -0.9%, utilities/consumer staples about -0.5%, small caps IWM -0.4%, while equal-weight RSP is nearly flat.
Meanwhile, tech is still attracting money: XLK +0.6%, $MSFT +1.3%, $META +1.2%, and NVDA around +1.0%. AAPL, however, is down -0.35%. SPY is only +0.14% and QQQ +0.24%—the green is coming from the leading AI/software names, not breadth.
This isn’t the same play as last night’s after-PCE “fake breadth with Apple leading while META got dumped”: today, yields hitting multi-year highs are pricing duration and rate-sensitive stocks, with flows concentrating into more rate-resilient, cash-flow-strong tech bellwethers. For the short term, watch whether the 10Y can retreat from above 5.30; if it keeps pushing toward 5.35–5.40 while IWM/XLRE can’t hold, that little bit of green in the indices will be even less trustworthy.
What are you more worried about right now: yields pushing higher again, or continuing to hold MSFT/META to hedge the breadth?
$MSFT $META #美股 #国债收益率 #Technology stocks