

EXCAVO MOMENTUM PORTFOLIO: MECHANICS, PERFORMANCE, AND TRAPS OF SYSTEMATIC ROTATION
Analytical review of DVA
Sometimes the most interesting thing about an investment strategy isn’t which stocks it buys, but the rule by which it sells them.
EXCAVO Stocks — a good example of this approach. The company offers a model portfolio of U.S. stocks from the S&P 500 universe. Officially, EXCAVO describes it as a momentum strategy: the system ranks stocks by price dynamics, updates about one-third of the portfolio every month, and does not use value or quality as separate factors.
And this is exactly where the interesting part begins.
FACT: this is not a forecast, but a selection algorithm
EXCAVO takes S&P 500 stocks and calculates 9–1 momentum — the price change from 10 months ago to 1 month ago.
Next, a portfolio of 26 positions is formed. The model uses three staggered tranches of 15 stocks. Each tranche is held for a quarter, but it is updated with a one-month shift. Therefore, roughly one-third of the portfolio changes every month. Some strong positions may enter immediately into two or three tranches.
The weight of one position is from 2.22% to 6.67%, and the share of a single sector is capped at 40%.
In other words, the algorithm doesn’t ask: “Which company do I like?” It asks: “Which stocks currently have the strongest relative price dynamics?”
This is a fundamental difference.
MECHANISM: strength remains, weakness shows up
Momentum is a bet that an asset’s relative strength can continue for a period of time.
Therefore, the system is not required to sell a stock just because the company is “bad.” And conversely, it is not required to hold a stock only because it generated a big profit. If the ranking changes, the position can be reduced or closed.
For a systematic investor, there should be no concept of: “I already made money on this stock, so I don’t want to sell it.” There is only one rule: if the criterion is satisfied → the position remains. If the criterion is no longer satisfied → the position changes.
This is not a forecast of the future. It’s a disciplined reaction to data that already exist.
RESULT: what EXCAVO itself shows
According to EXCAVO Stocks’ current official page, over a five-year period the model shows +253.1% total return or +27.7% annualized. The maximum stated drawdown is −19.1%, and the longest period below the previous peak is 15 months. EXCAVO notes that the results shown account for estimated transaction costs and slippage.
Over the years on the current page, it shows:
Year EXCAVO S&P 500
2025 +37.1% +14.6%
2024 +31.2% +22.9%
2023 +16.1% +18.7%
2022 −5.3% −13.6%
2021 +14.3% +9.1%
This is an important detail for the analysis. 2022 was a losing year. So EXCAVO’s own history does not validate the thesis of a system that constantly beats the market. It shows something else: the outcome depends strongly on the market regime.
WHY MOMENTUM CAN WORK
The idea of momentum is not invented by EXCAVO. The academic literature has studied for decades the phenomenon that stocks with relatively strong recent returns tend to preserve relative strength for some time.
Dimensional notes that the momentum premium historically concentrates over a relatively short horizon and gradually fades: in their analysis, the outperformance over the market disappears after roughly 9 months, which creates high turnover—for continuous use of the premium, turnover can exceed 100%. That’s why systems trying to capture it need regular position updates.
S&P Dow Jones Indices also has a separate S&P 500 Momentum Index, designed to measure S&P 500 stocks with persistent relative price performance. As of August 31, 2026, this index had 99 constituents, up +23.12% since the start of the year, down −2.37% over three months, and up +26.37% over one year.
So momentum is not just a marketing buzzword from EXCAVO. It’s a factor studied long ago. But a factor is not the same as a guarantee.
TRAP #1: momentum looks backward
That’s the key feature. The system sees what has already happened. If a stock has risen strongly over the previous months, it gets a high momentum rating. But that does not mean it will necessarily keep going up.
A reversal can happen: strong trend → market change → decline → a late exit signal. The algorithm didn’t “make a mistake” if the future turned out differently. It simply worked with the data that were available at the time of the decision.
TRAP #2: momentum crashes
This is no longer a theoretical problem. Daniel and Moskowitz (2016) describe rare but prolonged negative periods for momentum strategies, known as “crashes.” The researchers link them to sharp market rebounds after a drop and high volatility: in such conditions, yesterday’s winners can become sources of losses, and yesterday’s laggards can turn into unexpected leaders.
And that’s why momentum cannot be assessed only by average returns. You also need to look at: returns → drawdown → drawdown duration → turnover → costs.
TRAP #3: portfolio turnover
Monthly rotation means the strategy requires trading. Dimensional notes that the fast fading of the momentum premium implies high turnover to capture it: since up-momentum stocks typically no longer contribute to the premium after about 9 months from their previous ranking, turnover for continuous use of the premium can exceed 100%.
This creates a practical problem for the investor. Even if EXCAVO includes estimated transaction costs and slippage in its historical model, a real investor may get a different result due to the specific broker, spreads, the timing of trade execution, taxes, and their own position size. EXCAVO explicitly states that the user performs the trades themselves and bears the related risks.
TRAP #4: don't confuse momentum with fundamental analysis
This is especially important to fix in the introductory material. EXCAVO explicitly states:
«No other factors are used: no value, no quality — momentum only».
Therefore, explaining their portfolio through business quality, backlog, margins, or free cash flow as part of the algorithm — is incorrect when we’re talking specifically about STOCKS. This does not mean fundamental data cannot be useful to an investor. It only means one thing: you cannot attribute to the system factors that it does not officially use.
2026: an important test for momentum
This year, there’s another interesting detail. The S&P 500 Momentum Index showed very strong performance in the first half of 2026, but in the summer momentum saw a sharp reversal. According to S&P Dow Jones Indices, as of August 31 the index was up +23.12% YTD, but over the previous three months it was down −2.37%.
Public market commentaries also recorded a drop in momentum by more than 9% from July 1, alongside the broad S&P 500 rising by about 2.8% over the same period.
This is a good example of why momentum cannot be equated with steady outperformance. A strong factor can quickly change behavior.
DVA: what truly matters here
For DVA, the main lesson from EXCAVO is not found in specific stocks. It lies in the decision architecture:
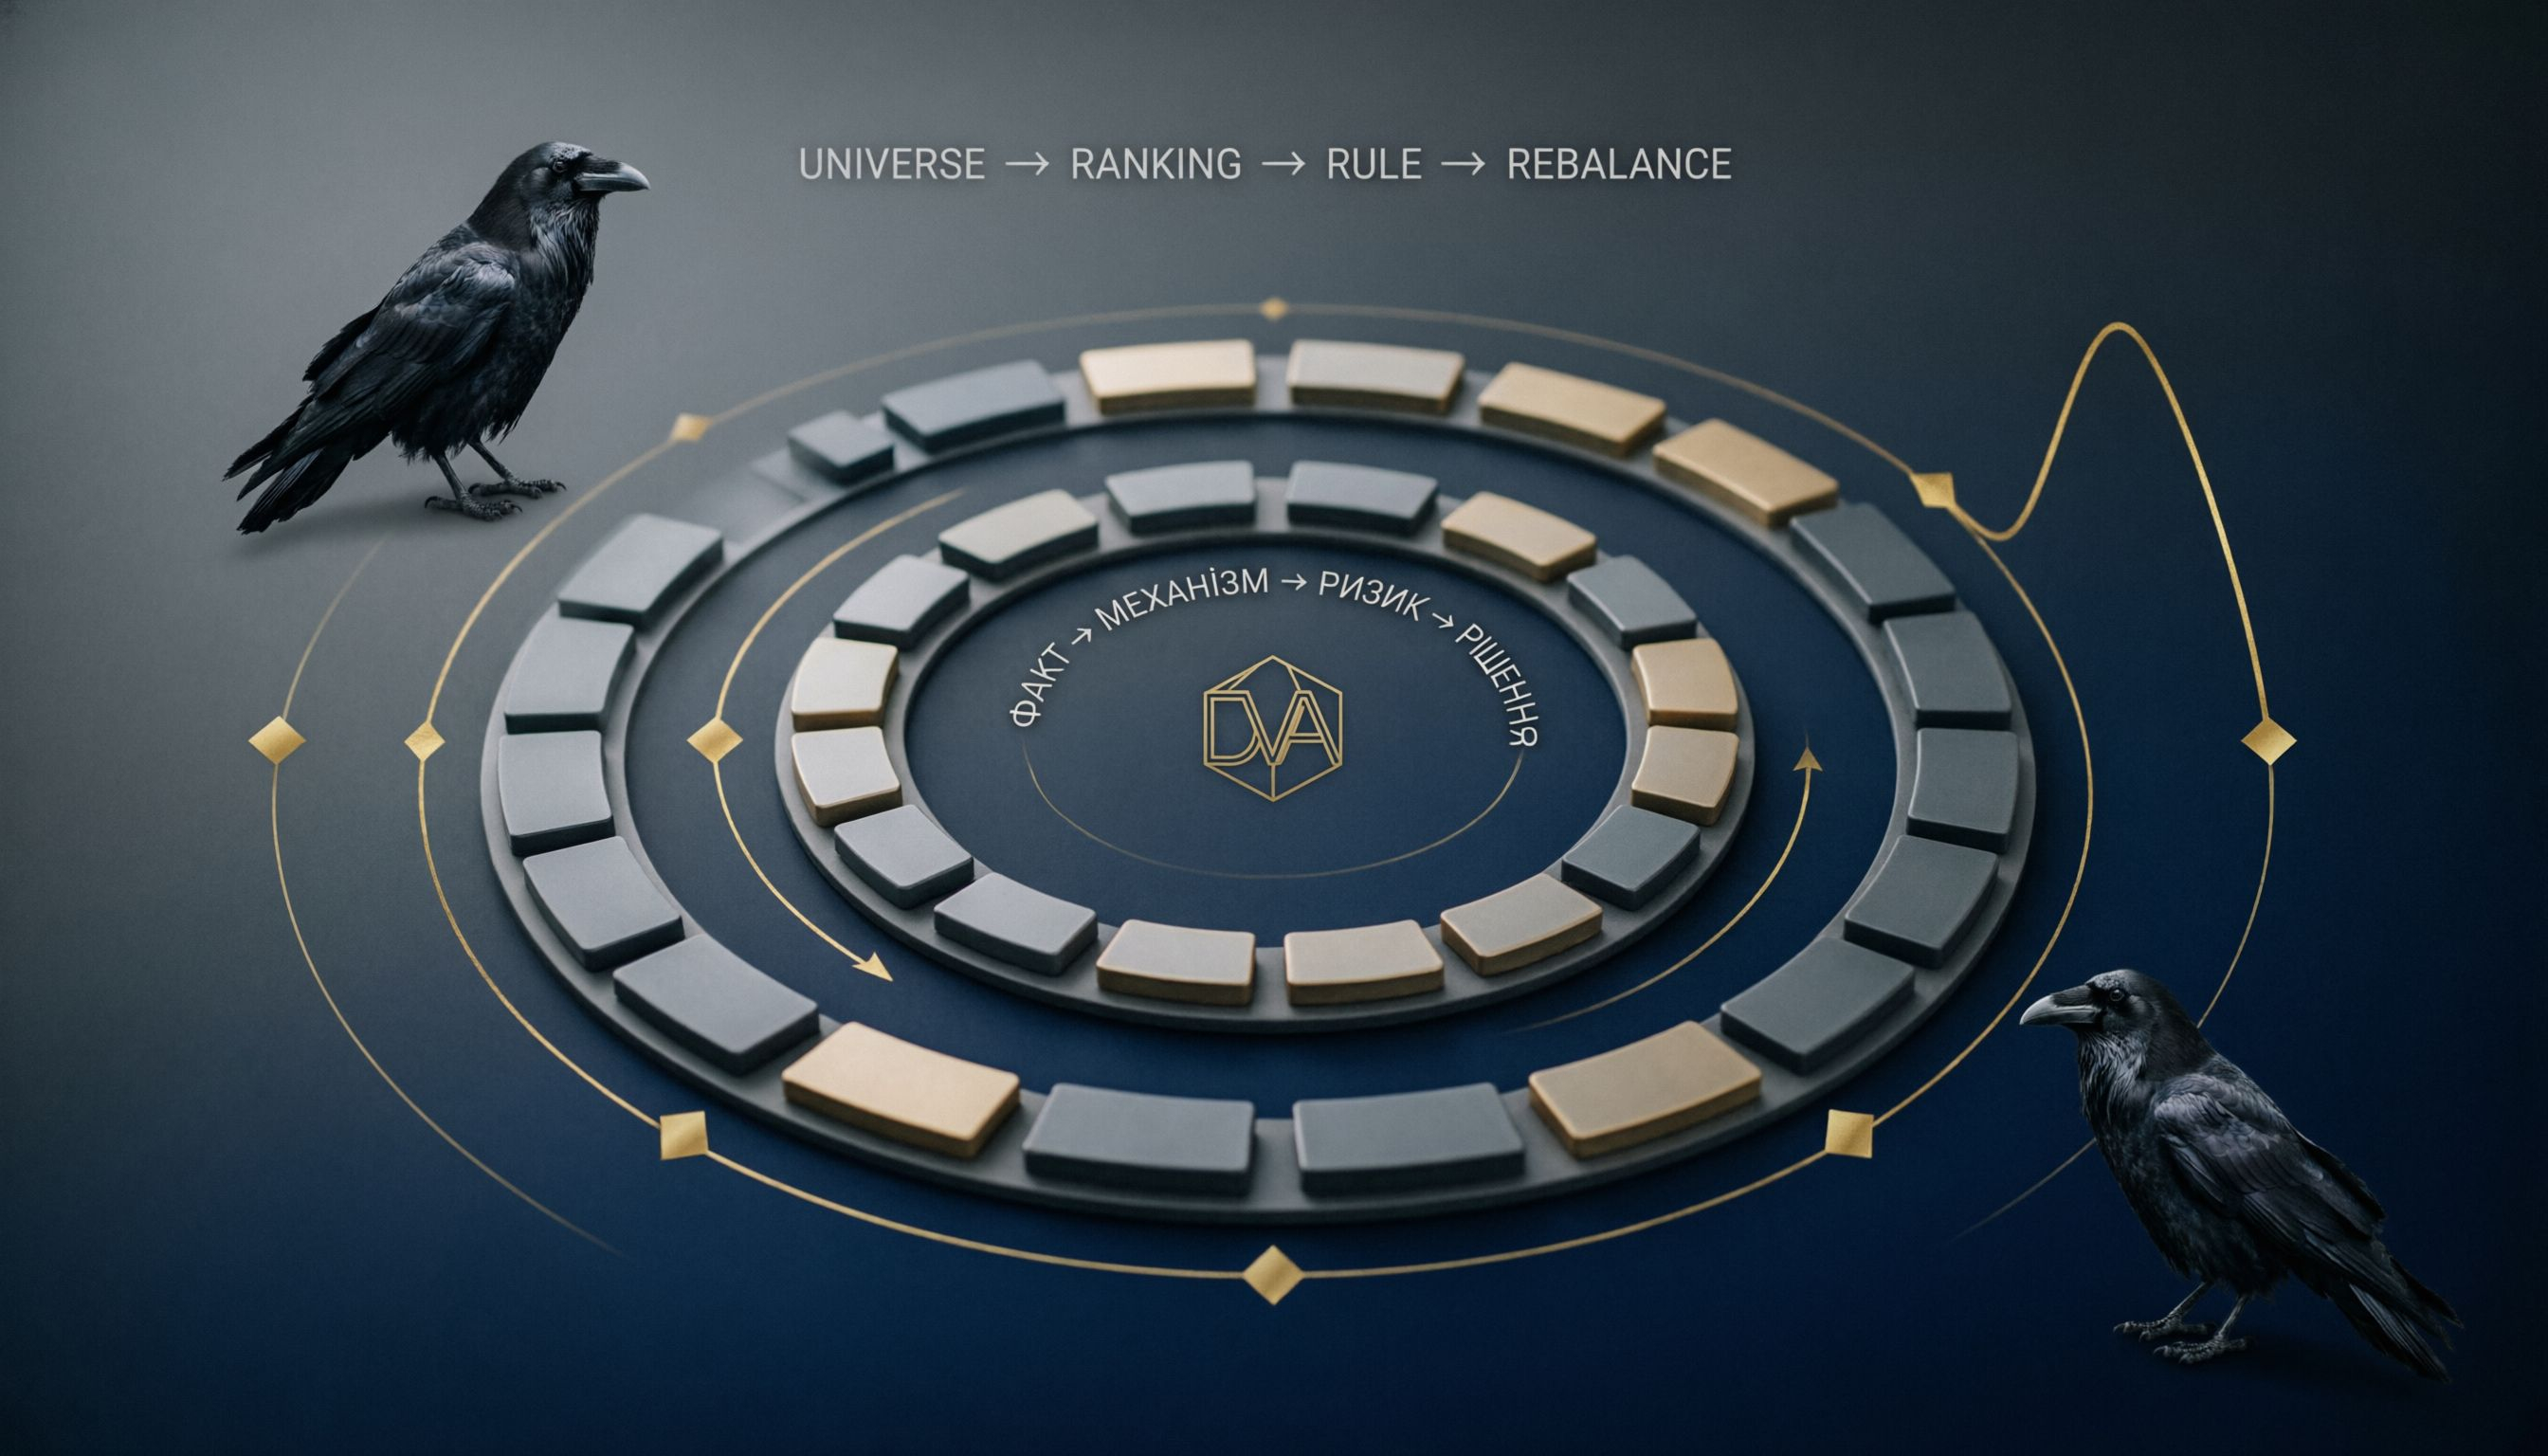
UNIVERSE • RANKING • RULE • REBALANCE
First, a defined universe. Then, one clear criterion. Then, a mechanical decision. Then, regular review.
This is a completely different psychology than: “I believe in this company, so I’ll hold it until it comes back.”
But there’s a second half to the lesson. The system does not eliminate risk. It only transfers risk from a human decision to the properties of the system itself.
Therefore, before copying any DVA algorithm, it asks five questions:
1. What exact signal is used?
2. What is the data horizon?
3. How often is the portfolio changed?
4. What is the maximum historical drawdown?
5. What happens when the market regime changes?
And only after that does it make sense to look at the nice return figure.
DVA CONCLUSION
EXCAVO does not prove that momentum “beats” the market. It shows something else: a clearly defined rule can systematically replace part of an investor’s subjective decisions.
In a favorable environment, this can produce strong results. In an unfavorable one, the system will still carry out its rules just as rigorously and lock in weakness.
So the main lesson is not: “buy what EXCAVO buys.” Instead: “understand the mechanism before buying the result.”
For DVA, it’s one formula:
FACT • MECHANISM • RISK • DECISION.
Don’t fall in love with an asset. Don’t fall in love with the algorithm either. First, understand the rule.
Sources:
· EXCAVO Stocks — official methodology and track record
· S&P 500 Momentum Index — S&P Dow Jones Indices
· Dimensional, “Myth-Busting with Momentum: How to Pursue the Premium”
· Daniel & Moskowitz (2016), “Momentum Crashes”
#DVA #Stocks #Momentum #S&P500 #Investing