

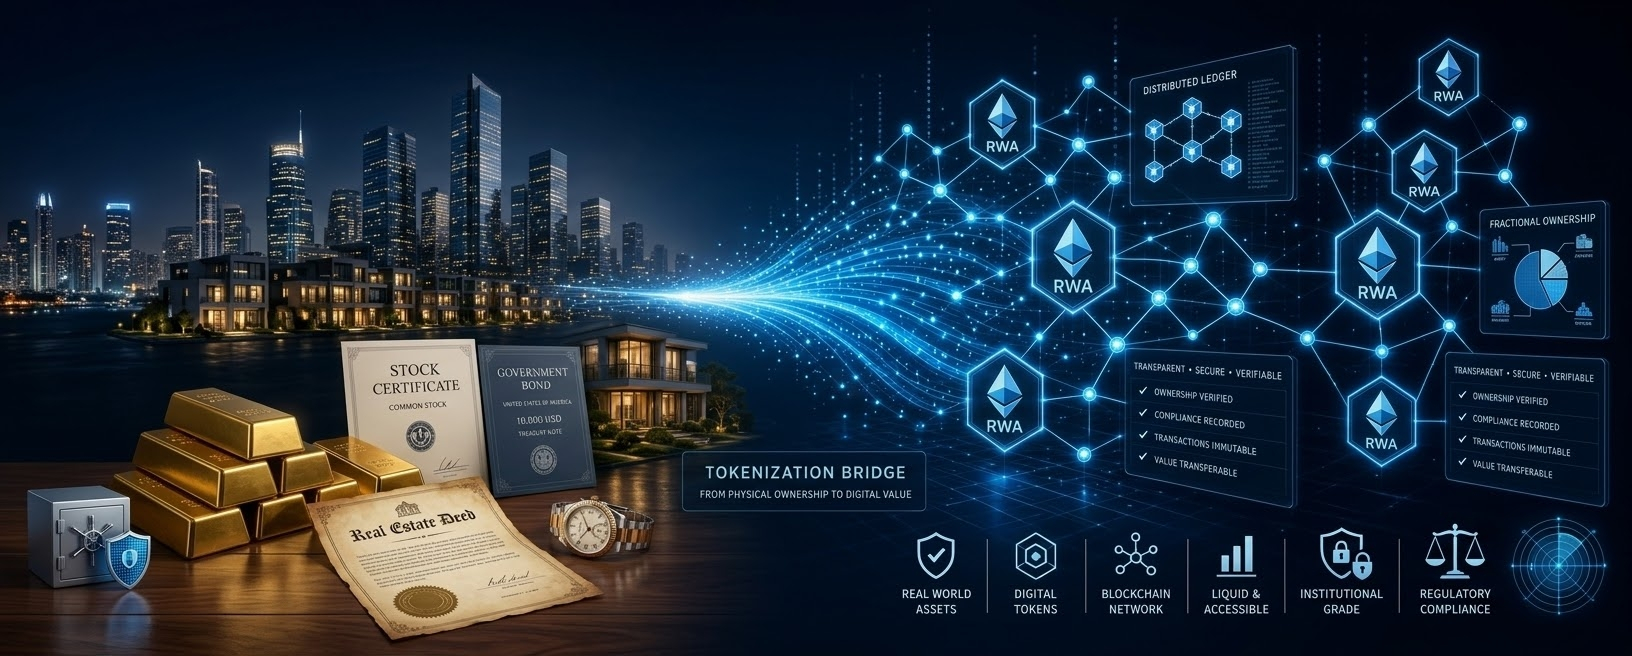
The tokenization of real-world assets (RWA) has stopped being a promise and become infrastructure. But almost everyone gets the size of this market wrong when they talk about it, because the numbers depend on how you count.
How much is the real market worth?
Trackers use two different metrics:
Distributed value (on-chain): tokens that an investor can buy, sell, and hold in their own wallet, not counting stablecoins. It ranges from US$ 34 to 46 billion by the end of September 2026. RWA.xyz points to around US$ 38–39 billion, and the variation between platforms comes from the methodology.
Value represented: assets recorded on blockchain as a record layer, but which often can’t circulate freely outside the issuing platform. Here the number rises to something between US$ 350 and 390 billion.
If you add stablecoins—which technically are also tokenized real assets—the total exceeds US$ 330 billion. That’s why the numbers floating around seem contradictory: everyone uses a different definition.
Where the money is
US Treasuries and money market funds lead, at about US$ 14–18 billion.
Next come private credit and commodities, mainly gold.
Tokenized stocks are the fastest-growing segment: they already total US$ 3–4.5 billion, with growth in the hundreds of percent year over year.
One detail that few mention: only 6% to 12% of these assets are actively used in DeFi, as collateral or in yield strategies. Most are still parked in institutional reserves. The technology is already there, but usage is still far from its potential.
Why this matters
Near-instant settlement (T+0) and operations 24 hours a day, 7 days a week.
Fewer intermediaries, which reduces custody and clearing costs.
Bridge the gap between the traditional market and crypto: institutions use blockchain without giving up the assets they already know. BlackRock, Franklin Templeton, Securitize, and Ondo are in this race.
The move that changed the game in the US
On September 17, 2026, the SEC published the "Innovation Exemption." It’s a temporary 5-year exemption that allows the secondary trading of tokenized stocks on permissioned platforms that use AMMs and liquidity pools on public blockchains, without requiring the venue to register as a national exchange. There are volume and number-of-assets limits, and the SEC opened a public consultation.
Meanwhile, the NYSE and DTCC are advancing on-chain infrastructure for stocks, ETFs, and Treasuries. SEC Chair Paul Atkins has publicly argued for moving parts of the equities market onto blockchain networks.
The risks the market hasn’t solved yet
Regulation fragmented across countries.
Taxation without clear rules in many cases.
Low secondary liquidity across several assets.
Custody of the real asset that sits behind the token.
Oracle failures and counterparty risk.
Representation versus ownership: some tokens are only a synthetic right, without giving real ownership of the underlying asset.
Without clear rules, and without heavyweight custodians and clearing houses, the market won’t scale.
My take
Growth is real, but most of the value is still institutional and little used in DeFi. The SEC decision lowers the regulatory barrier in the US and can accelerate that usage. Anyone who understands the difference between "distributed value" and "value represented" will analyze this market with far more clarity than most.
Did you like the analysis?
I track crypto, tokenization, and regulation moves every day, with verified data and no fluff.
Follow my profile here on Binance Square so you don’t miss the next analyses.
Comment: do you think tokenized stocks will beat the volume of tokenized Treasuries? I read and respond.
Share with anyone who still confuses "tokenized" with "transferable".