Data revisions are fine; the issue is getting the market to trust this data. However, at the moment, the market doesn’t seem to show much satisfaction with tonight’s PCE revision.
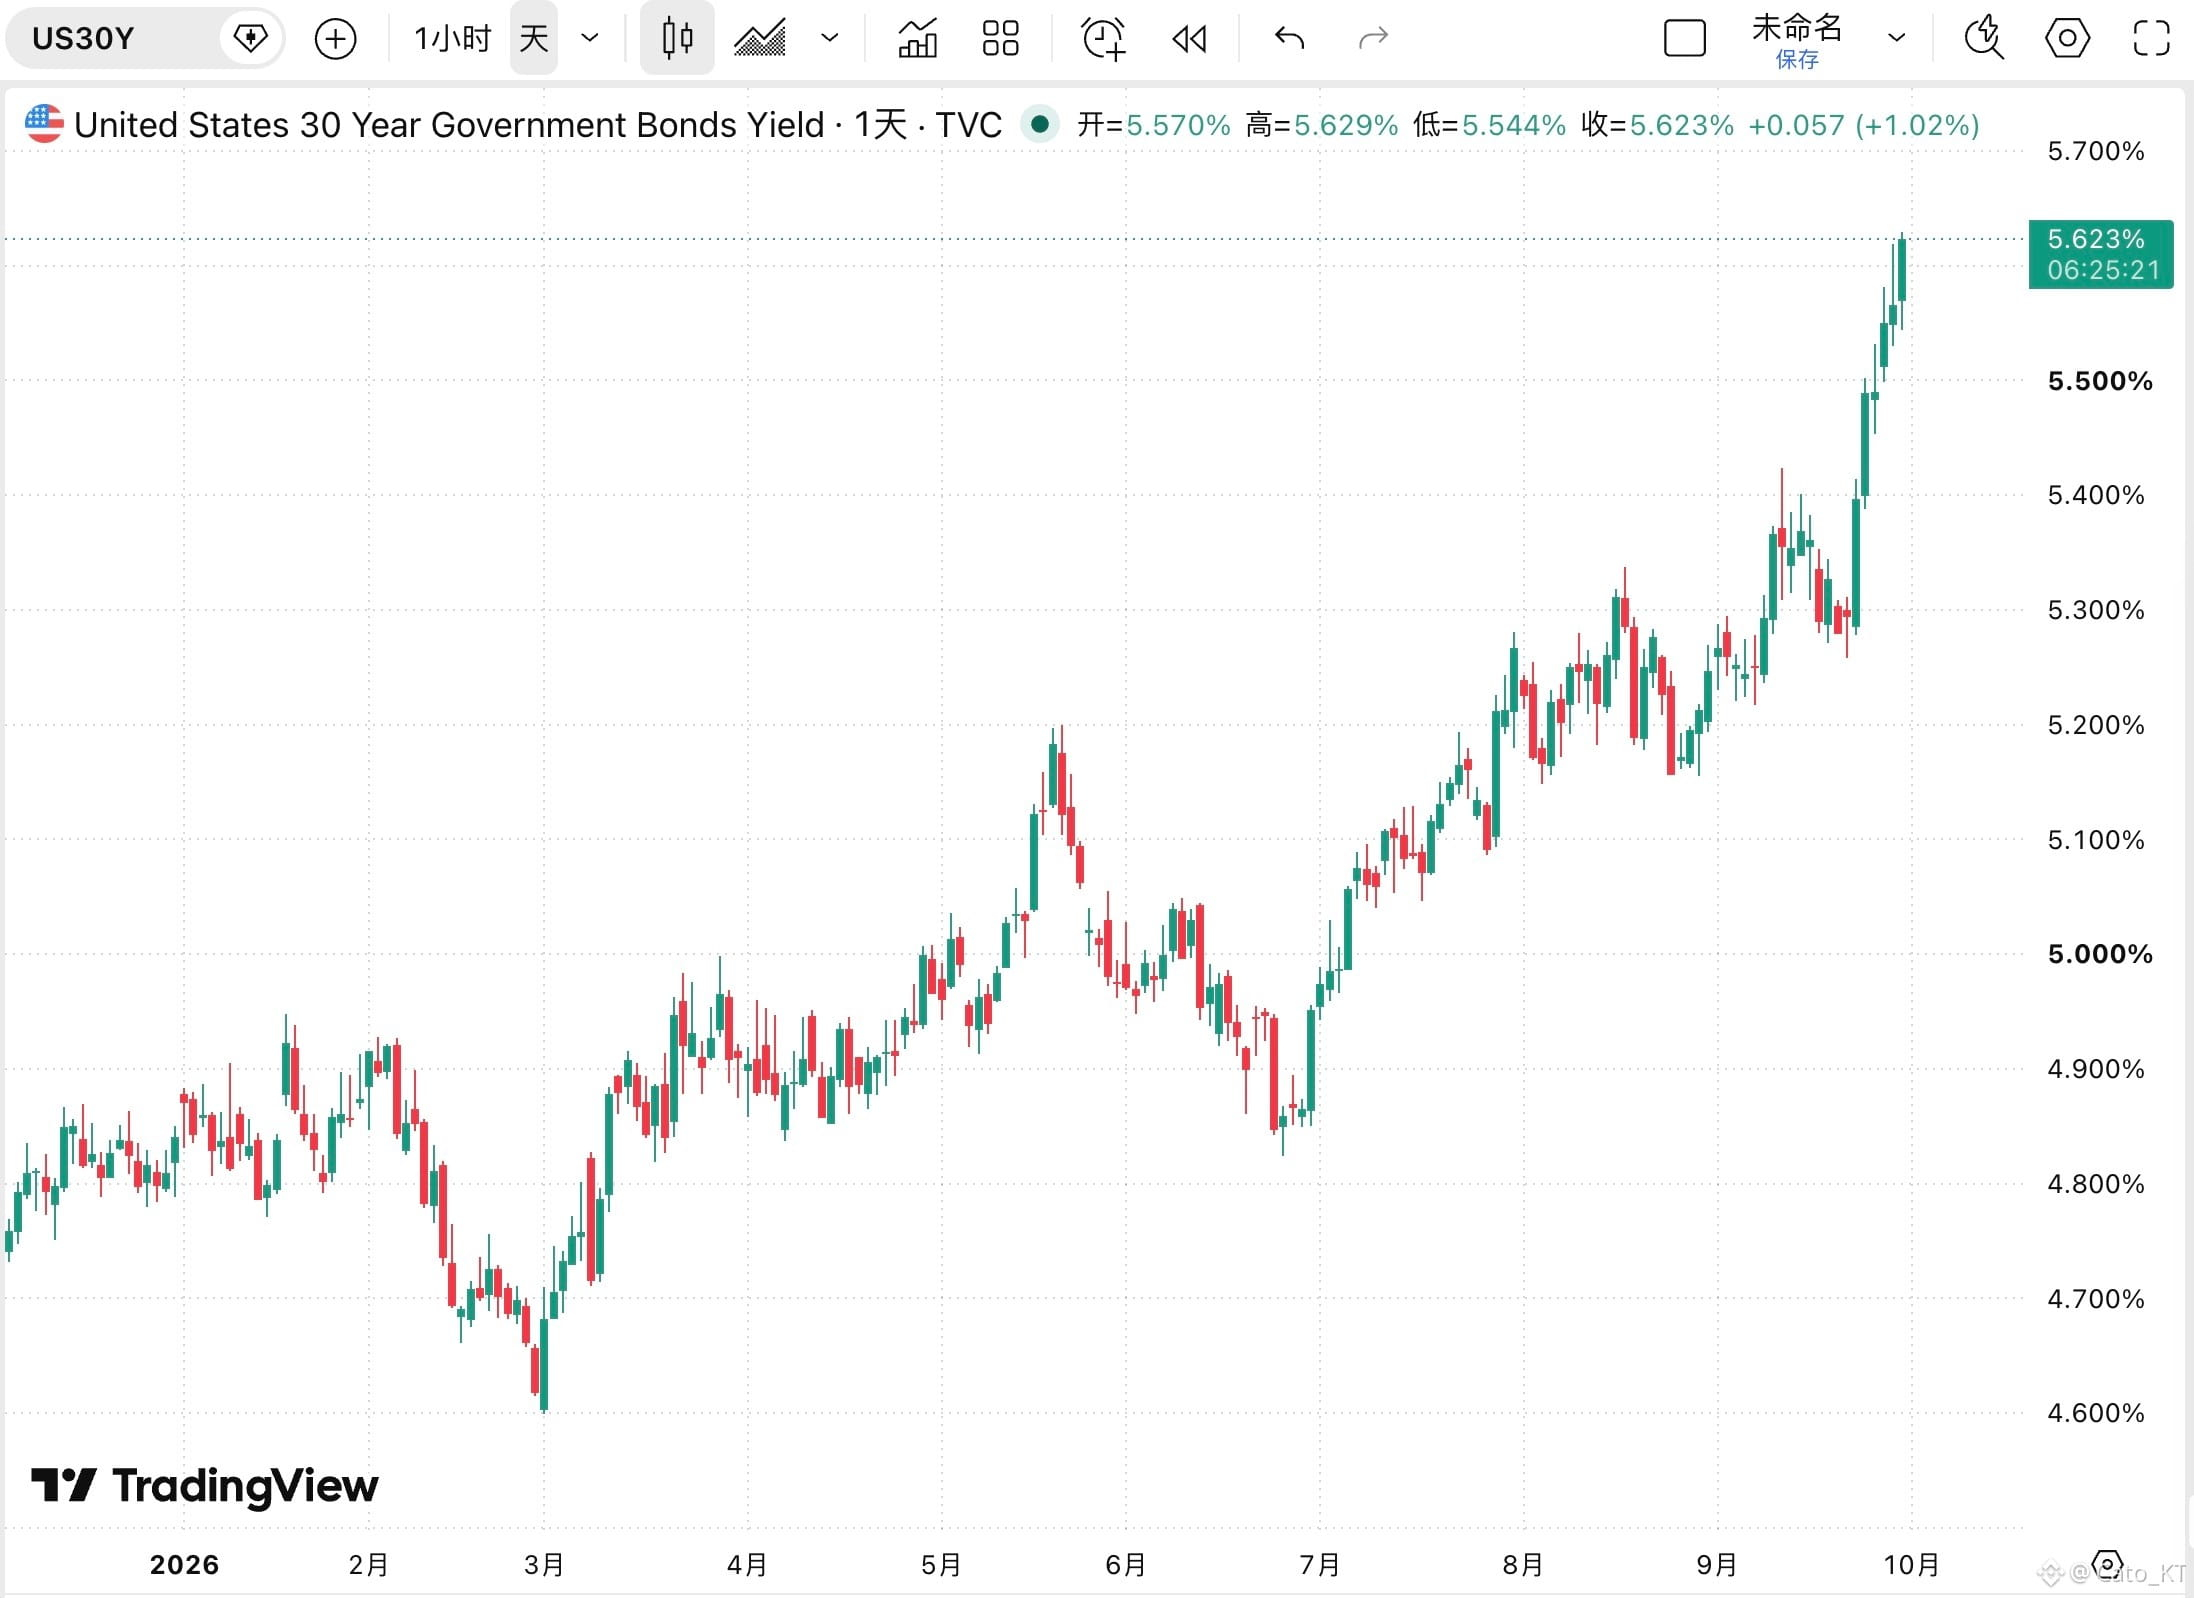
Two hours after the August PCE release, the yield on the 30-year U.S. Treasury broke to a new high. What does that indicate?
It suggests the market is not interpreting this PCE downward revision as a long-term inflation risk being resolved. Problems on the long-end have become so complicated that they’re not just about inflation anymore. The main factors keeping long-term Treasuries under heavy selling pressure include the term premium, fiscal supply, real interest rates, and uncertainty around long-term policy.
Moreover, the continued rise in long-term Treasury yields directly offsets the positive impact of the revised PCE on risk assets, putting additional pressure on risk assets. So after the PCE data release, I think we should still focus on how much the market trusts the data before discussing any next steps.
Of course, regarding risks in the bond market, here I’d like to wrap up with a comment: the bond market’s risks have not yet fully materialized. Next, watch the gold price trend. If long-end Treasury yields continue rising while gold rises in tandem, that would imply the bond market’s credit system itself is being called into question. That may be one of the biggest risk points in the bond market!#美国8月核心PCE降至3%