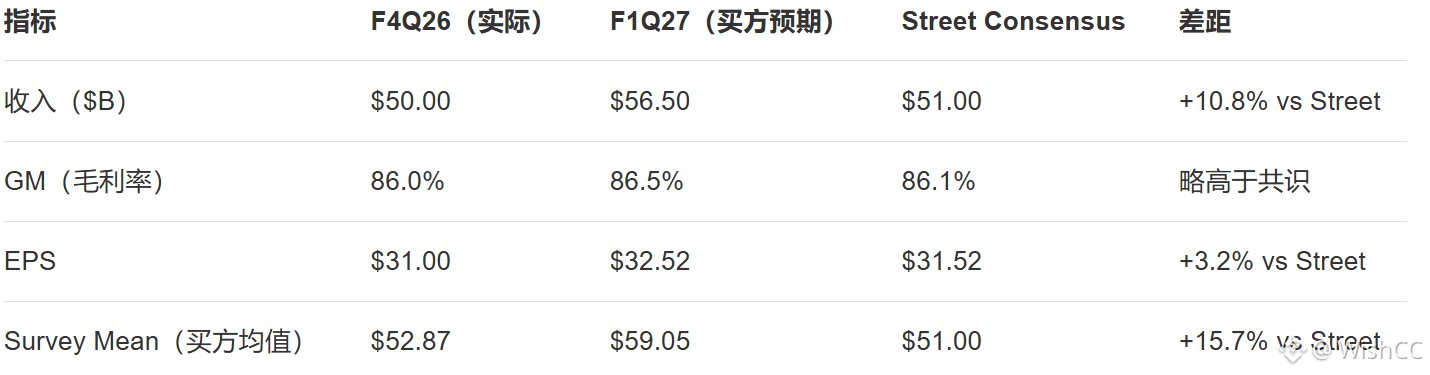
#Micron ( $MU ) current buyer expectations are significantly higher than Wall Street consensus
Key drivers include strong quarter-over-quarter growth in DRAM/NAND prices, accelerating HBM4 shipments, DC SSD revenue exceeding $5 billion, and cost advantages plus long-term earnings resilience from production capacity agreements (SCA);
F1Q27 guidance is expected to be materially raised, alongside the high-cash-return commitment supported by CHIPS Act catalysts (starting end of 2026, 100% of free cash flow will be used for buybacks), which will support upside valuation potential