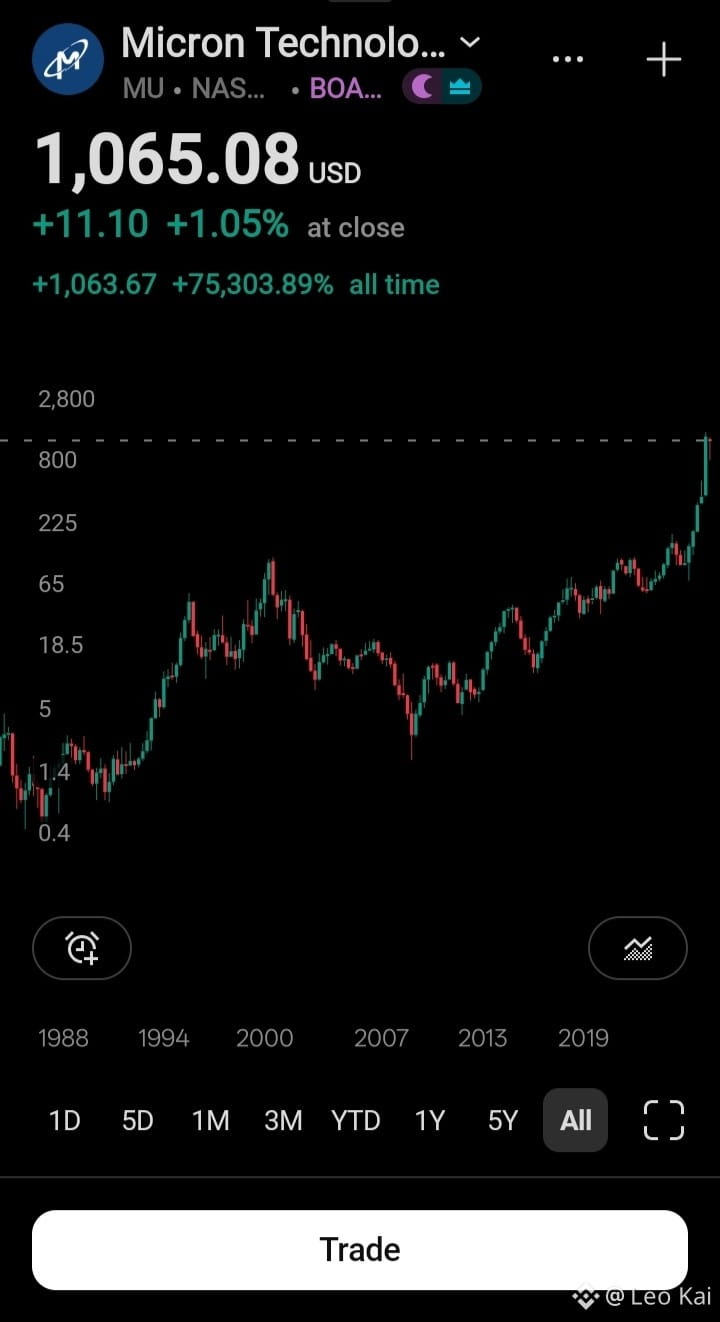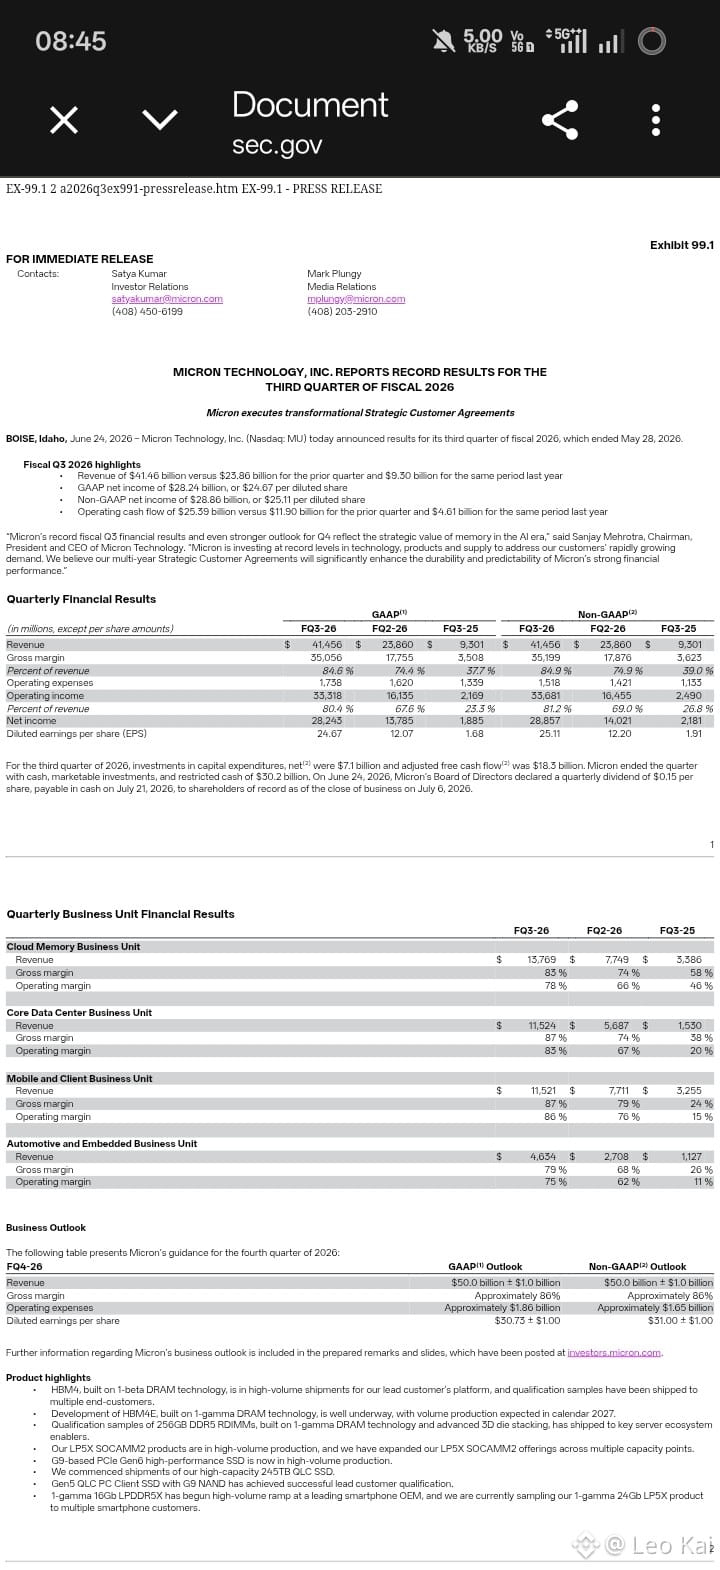
$MU Micron reports tomorrow and honestly the numbers are almost silly. Guide is $50B revenue, ~86% gross margin, ~$31 EPS. A year ago the same quarter was $11.3B. Q3 was already up 346% YoY.
But that's the catch. Consensus sits around 86.3% GM, so an in-line 86% isn't a surprise, it's the price of admission. Management also said price increases are moderating, so the easy "prices go up, margins go up" leg looks done.
What keeps me from turning bearish is the structure. Multi-year customer agreements with take-or-pay and price floors, and supply that stays tight past 2027. New fabs don't really help until 2028.
So I'm bullish on the cycle lasting longer than people expect, but I'm not chasing into the print. A good number can still sell off when the bar is this high.
Not advice, just my read. What are you doing into earnings? $MU
#EarningsSeason