Everyone is looking at Micron’s result tomorrow.
But I think the most important number is NOT the revenue.
It’s the margin.
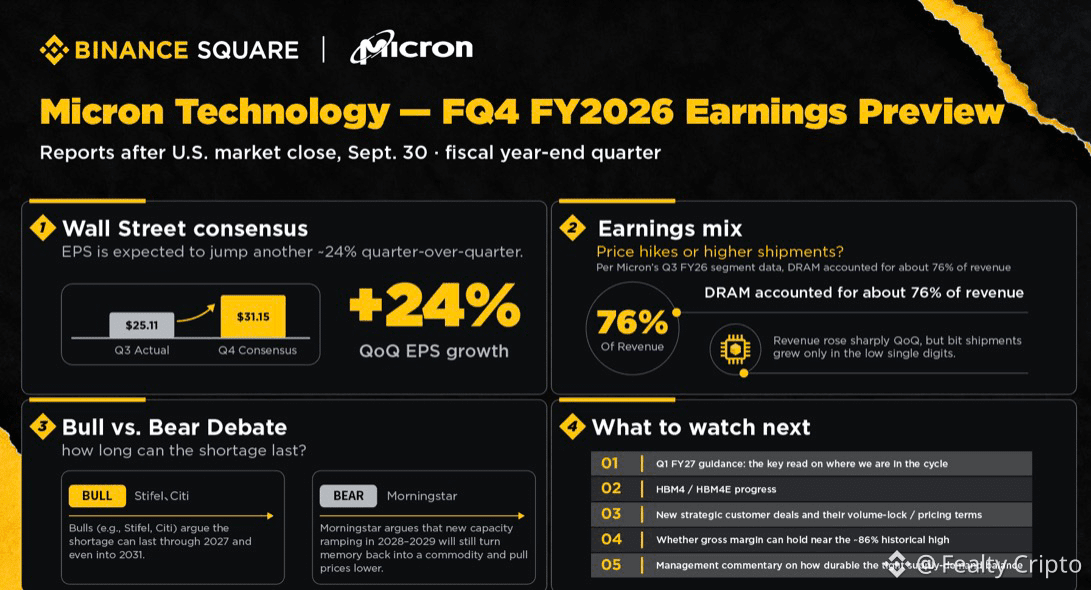
Even $MUB itself projected approximately:
US$50 billion in revenue
≈86% gross margin
≈US$31 earnings per share
That’s absurd for a company that for a long time has been treated as a “cyclical” memory manufacturer.
And here’s why:
AI doesn’t just need GPUs.
It needs A LOT of memory.
HBM has become a key component to feed AI chips with data fast enough.
So, for me, tomorrow’s result will answer a bigger question than:
“Did Micron beat or miss the consensus?”
The question is:
can this memory supercycle really continue?
If Micron delivers margins near or above 86% and still shows strong demand for HBM, the thesis that AI is structurally changing the memory market gains momentum.
But there’s a risk I wouldn’t ignore:
$MUB has already risen a lot, and expectations are enormous too.
When everyone expects an outstanding result, sometimes “excellent” just isn’t enough anymore.
What I want to see above all:
margin
guidance
demand for HBM
and how much the company plans to invest to increase capacity.
Because strong results count the past.
Guidance tells you what the company is seeing ahead.
$MUB #EarningsSeason #AIStocks #MicronSharesRise10
For you, is the memory supercycle still just beginning… or has the market already priced in too much expectation?