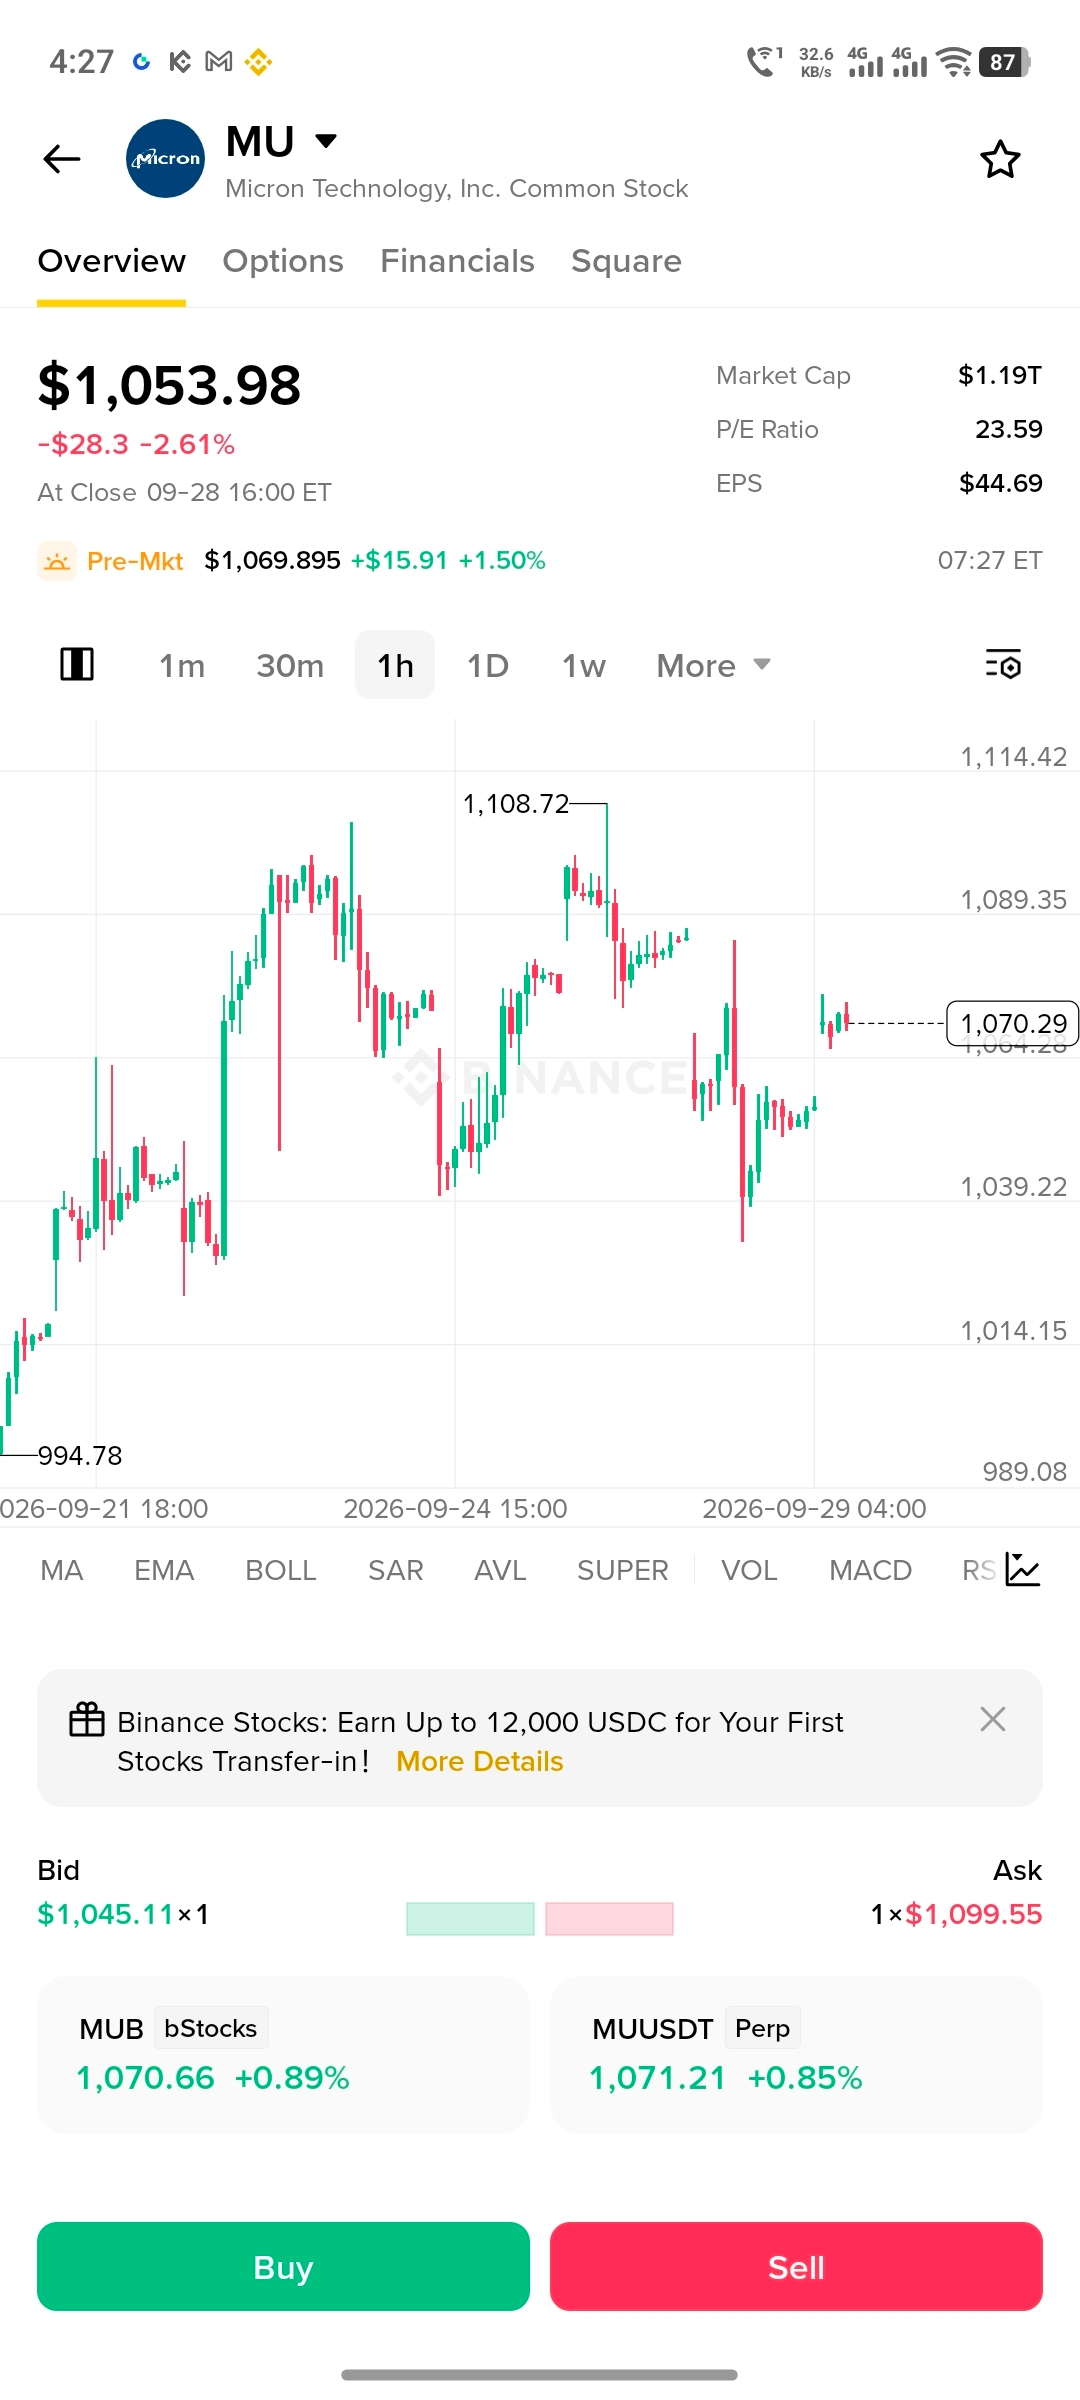

$MU is heading into one of its biggest earnings tests of 2026.
Micron is guiding for around $50B revenue and 86% gross margin in FY2026 Q4, after reporting $41.46B revenue and roughly 85% gross margin in Q3.
For me, the key question isn't just whether Micron beats estimates. I’m watching whether HBM demand, DRAM pricing and margins can stay strong enough to support the memory supercycle narrative.
If Micron confirms another strong quarter and gives solid forward guidance, the market could get a fresh signal that AI-driven memory demand is still expanding. But if margins or guidance disappoint, expectations are high enough that the reaction could be sharp.
Bullish or bearish? I’m watching the numbers before choosing a side.
#EarningsSeason #MU
#Micron #stocks #Aİ