


The Market Demands its Release and the End of the Official Rate.
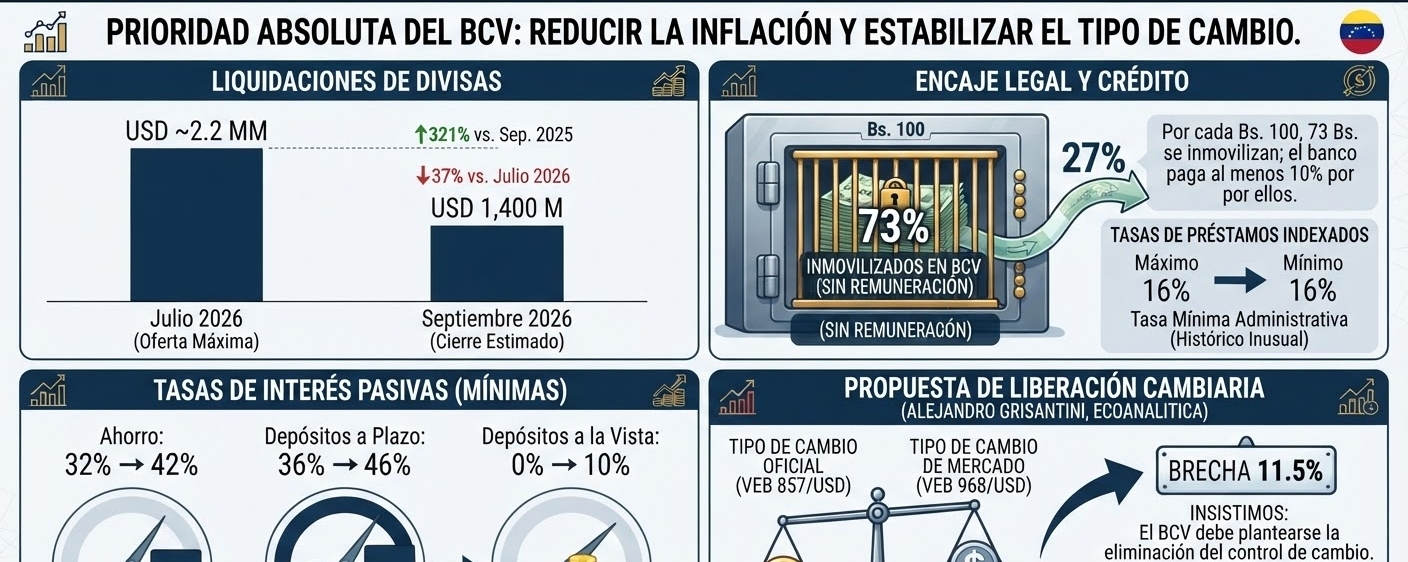
After a recent meeting between the BCV and the country’s leading banks, it became clear that the central bank’s absolute priority is to reduce inflation and stabilize the exchange rate, even at the cost of lower growth and a sharp credit squeeze.
The first sign is in foreign currency. September would end with settlements close to USD 1.4 billion. Although this represents a 321% increase compared to September 2025, it implies a 37% drop from July, the month with the highest supply of foreign currency.
The second front is interest rates. The BCV decided to significantly raise the minimum yields that banks must pay:
Savings: 32% → 42%
Time deposits: 36% → 46%
Sight deposits: 0% → 10%
This last change is particularly important. For every Bs.100 the banking sector receives, Bs.73 must remain immobilized at the BCV, with no remuneration. Now the bank will have to pay at least 10% for those same deposits. This is a direct and significant increase in the cost of financial intermediation.
On the credit side, something even more unusual happens: the active rates, on loans indexed to the official exchange rate, go from having a maximum of 16% to a minimum of 16%. We do not recall in Venezuela’s recent economic history that the BCV has administratively set a minimum rate for loans.
This is added to by the increase in the cost of financing through defaults on legal reserve requirements, which further discourages the granting of new loans. As a countermeasure, the BCV is “recommending” raising credit card limits from approximately USD 100 to USD 300.
🇻🇪ALEJANDRO GRISANTINI PROPOSES LIBERATING THE EXCHANGE RATE (ECOANALITICA)
The official exchange rate opens at VEB 857/USD, against a market exchange rate of VEB 968/USD. This places the official rate 11.5% below the market. With a spread of this magnitude, we insist that the BCV should seriously consider eliminating the exchange controls, especially as we are entering simultaneously a period of lower availability of foreign currency and higher seasonal demand.
We understand and share the goal of stabilizing the exchange rate and reducing inflation. But trying to defend an exchange rate that is increasingly farther from the market through less credit, managed rates, and a 73% reserve requirement can end up generating new distortions.
There is an opportunity to eliminate exchange controls. The larger the gap between the official rate and the market, the more expensive it will be to do so later.
#venezuela #finanzas #economy #Macro #Bancocentral $CL $BZ $BTC