U.S.-China Tariffs Cut by About $30 Billion Each: Moving From “Statements” to “Implementation”
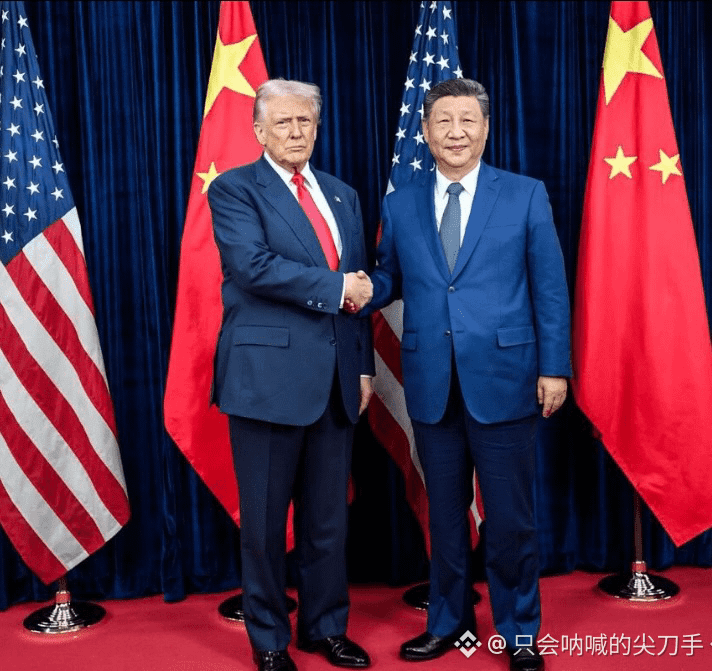
Substantive progress has been made in economic and trade talks between the U.S. and China. The two sides are no longer confined to a verbal consensus of “willingness to reduce tariffs.” They have reached agreement on reciprocal tariff-reduction lists for about $30 billion worth of each side’s imported goods: more than 90% of the relevant items’ tariffs will be rolled back to the MFN rate level. After their respective domestic legal procedures are completed, the reductions will be implemented simultaneously.
The “gold content” of the lists is high. On the U.S. side, the 77 items related to China’s exports include toys, household appliances, baby products, kitchen and bathroom appliances, and holiday gifts—mostly people-focused consumer categories frequently purchased by consumers in the U.S. mainland. On the China side, the 1,619 items related to imports from the U.S. include agricultural products, personal care items, medical devices, and coal, directly targeting real needs on the domestic consumption, healthcare, and industrial fronts. Neither side has filled the lists with obscure or peripheral items. This indicates that the concessions are targeted and come with “give-and-take.”
Its significance goes beyond sentiment. In the short term, the uncertainty surrounding trade frictions is narrowing. Global markets’ risk-avoidance expectations of “tariffs driving inflation and supply chains breaking again” may cool, and preferences for risk assets could recover. In the medium term, tariff reductions on consumer goods and intermediate inputs will directly ease U.S. household spending and reduce import costs for Chinese companies—both positive factors for inflation control on both sides and for stabilizing supply chains.
Of course, this is still “cooling off,” not “ceasefire.” Deeper issues such as remaining tariffs, non-tariff barriers, and industrial subsidies have not yet reached the bottom. But at the very least, both sides are willing to put real goods backed by real dollars on the table and pull tariff rates back. That in itself is a long-awaited rational signal in the narrative of a trade war—confrontation has a cost, and stepping back is more worthwhile than hardening one’s stance.