#SolanaETF #SOL Last week, U.S. SOL funds saw net inflows of about $188 million, but today SOL is falling. Put these two numbers side by side—it’s more interesting than just shouting “institutional buying.” Fund subscriptions reflect real demand, but why didn’t they hold up the current coin price?
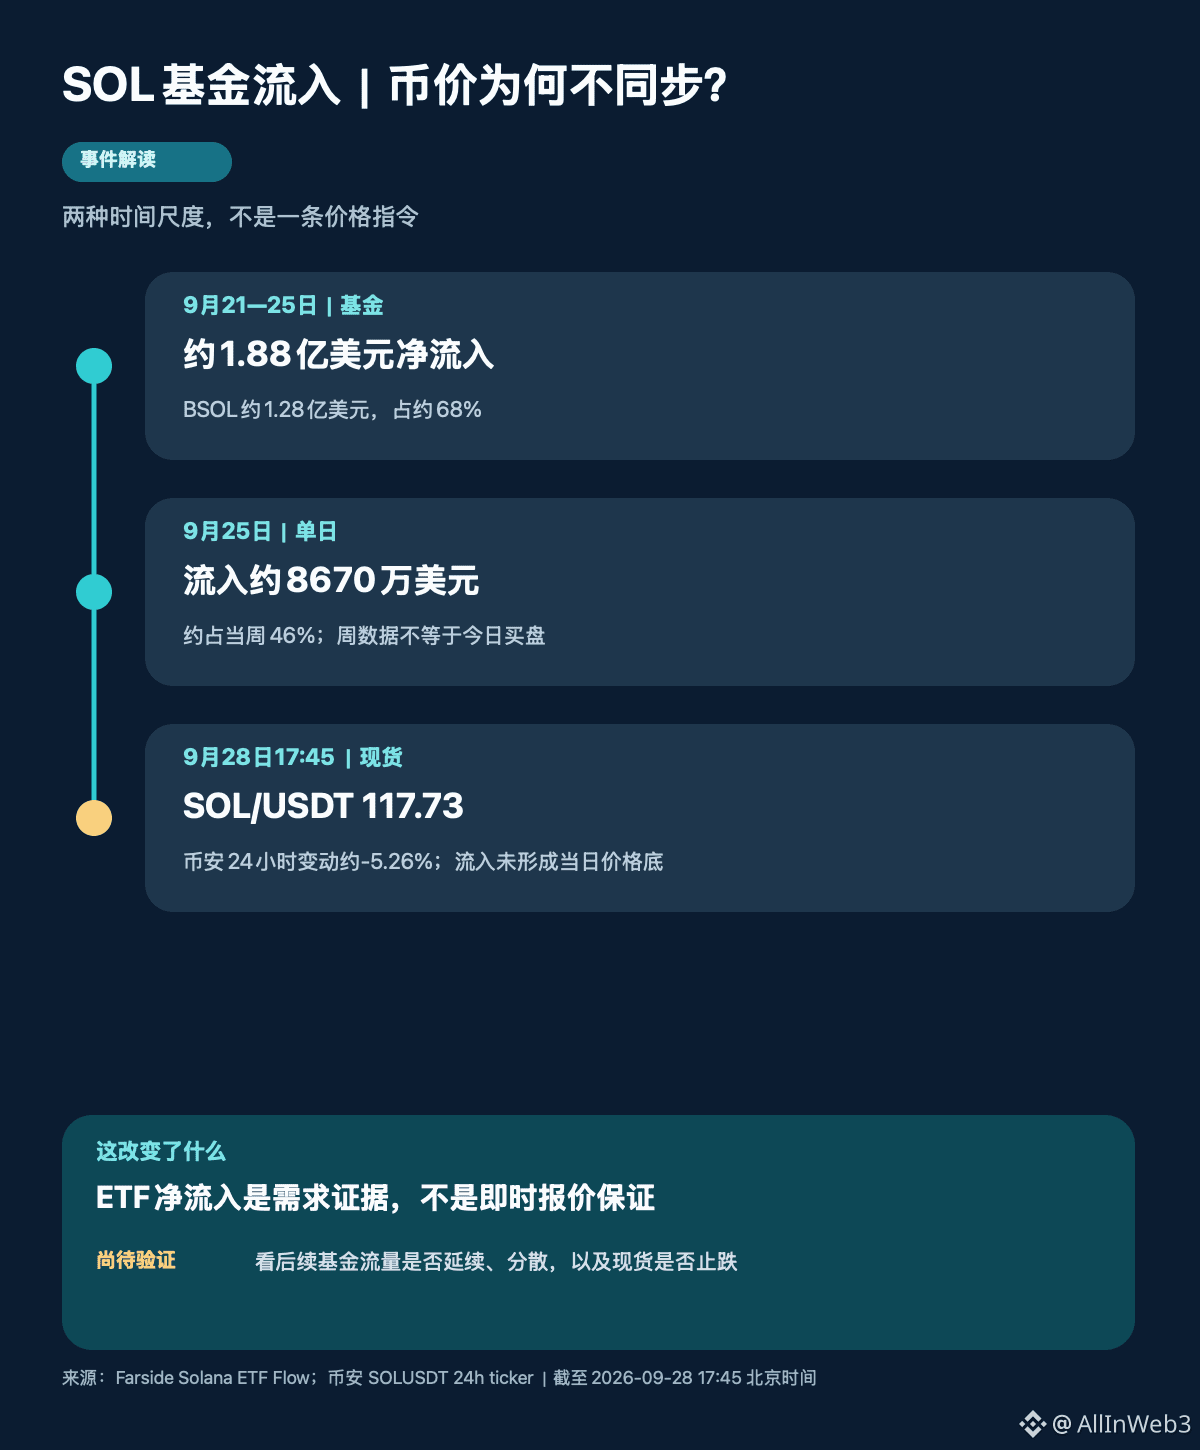
First, get the timing right. Farside shows that from September 21 to 25, over five trading days, total net inflows were about $188 million. Bitwise’s BSOL accounted for about $128 million, or roughly 68%. And on only the 25th, all funds combined saw inflows of about $86.7 million. But these are data from last week’s U.S. fund trading days—not the live buy orders on Binance spot at this moment on September 28.
Now look at today. At 17:45 Beijing time, Binance SOL/USDT is around $117.73, down about 5.26% over the past 24 hours. This doesn’t prove that ETF flows are “unused,” and it also can’t prove the drop was caused by any single seller. Fund share subscriptions/redemptions, market maker hedging, selling pressure from other exchanges, and the broader crypto market’s risk appetite can all cause fund flows and coin prices to fall out of sync in a short window. Right now, there isn’t enough evidence to rank the causes as primary or secondary.
What I care about more is the structure of the inflows: about two-thirds last week were concentrated in BSOL. That suggests this demand channel is strong, but it also warns us not to misread a weekly total as meaning every channel is adding exposure with the same intensity. And we definitely can’t automatically translate “weekly net inflow” into “the next daily candle must be bullish.” Net inflow measures changes in fund-share-level capital, while price is determined by the combined buy and sell forces at the moment—so the definitions and clocks don’t match.
So my view is: this dataset shows there’s an additional observable thread of sustained SOL demand, but it’s still not enough to declare that the short-term selloff has ended. What would truly improve confidence is whether inflows continue on the next fund trading day, whether they’re no longer overly concentrated in a single product, and whether SOL spot can stabilize under selling pressure. If funds keep flipping to net outflows, or if inflows persist while spot continues to break down, then we must reassess the claim that “fund demand is sufficient to absorb supply.”
Would you treat consecutive fund net inflows as a leading signal, or would you keep waiting for spot price and trading activity to confirm each other? If they continue to diverge, which one would you adjust first?