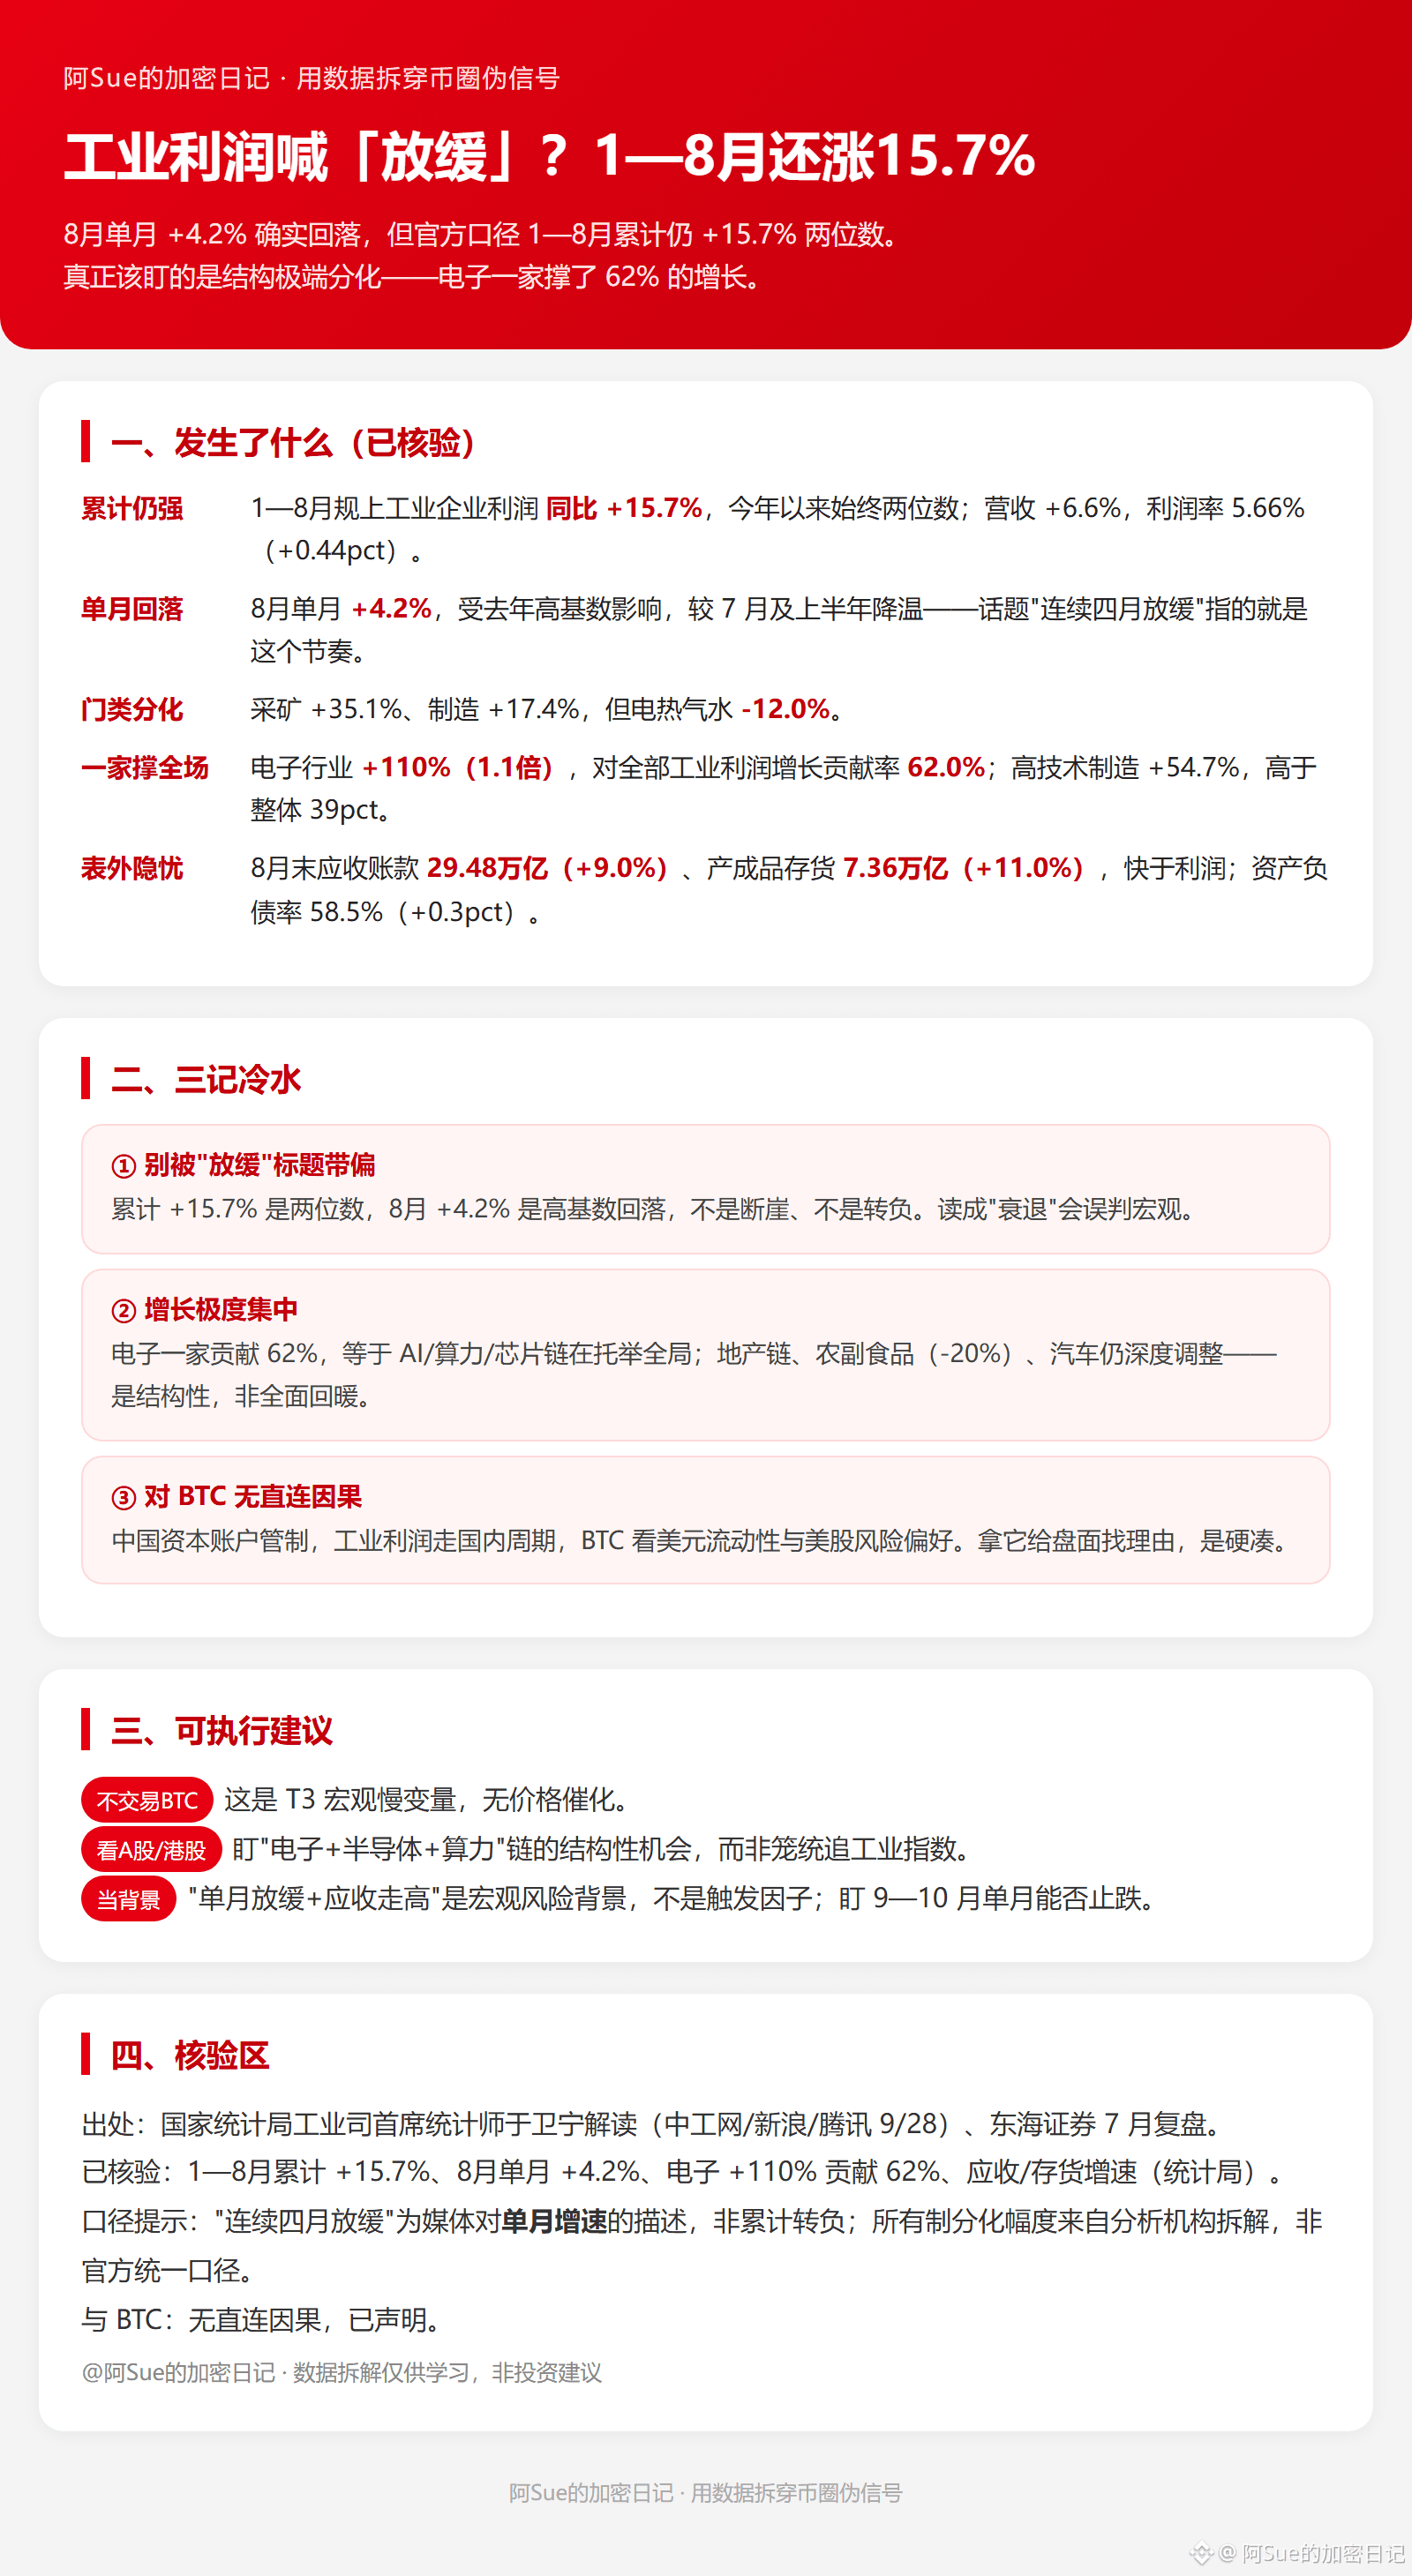
#中国工业利润增速连续四月放缓 Industrial profit calls for a “slowdown”? 1–8 months were actually still up 15.7%
The National Bureau of Statistics released on 9/28 the data for industrial enterprises’ profits for January to August 2026: profits for above-scale industrial enterprises were up 15.7% year-on-year, maintaining double-digit growth; revenue was up 6.6%, and the profit margin was 5.66% (+0.44 percentage points). But in August alone, profits rose only 4.2%, down from earlier periods—“a four-month consecutive slowdown” refers to single-month momentum, not a return to negative territory on a cumulative basis.
Data card (verified):
· Still strong cumulatively: January to August +15.7%, and double-digit growth has been sustained throughout the year.
· Single-month drop: August +4.2%, affected by the high base from last year, cooling versus July and the first half.
· Divergence by sector: mining +35.1%, manufacturing +17.4%, electricity/heat/gas/water -12.0%.
· One sector propels the whole show: electronics +110% (1.1x), contributing 62% to total industrial profit growth; high-tech manufacturing +54.7%, above the overall figure by 39 percentage points.
· Concerns off the balance sheet: by end of August, accounts receivable were 2.948 trillion (up 9.0%), and finished goods inventories were 0.736 trillion (up 11.0%); both are rising faster than profit growth. Asset-liability ratio was 58.5% (+0.3 percentage points).
Three buckets of cold water:
1) Don’t let “slowdown” mislead you: cumulative +15.7% is still double-digit; August +4.2% is a pullback from a high base, not a cliff—reading it as “recession” would misjudge the situation.
2) Growth is extremely concentrated: electronics alone accounts for 62%, essentially propping up the whole picture with the AI/computing/chip chain; the real-estate chain and farm/food (down -20%), as well as automobiles, are still in deep adjustment. This is structural, not broad-based recovery.
3) No direct causality to BTC: China’s capital controls mean industrial profits follow domestic cycles. BTC mainly reflects U.S.-dollar liquidity and risk appetite for U.S. equities; forcing a link is just finding an excuse.
Actionable steps: Don’t trade BTC based on this (T3 slow variable has no catalyst); focus on A-shares/H-shares/ Hong Kong stocks by targeting electronics + semiconductors + the computing chain rather than a generic industrial index. Treat “single-month slowdown + receivables rising” as background macro conditions, not a trigger factor—watch whether single-month performance in Sep–Oct can halt the decline.