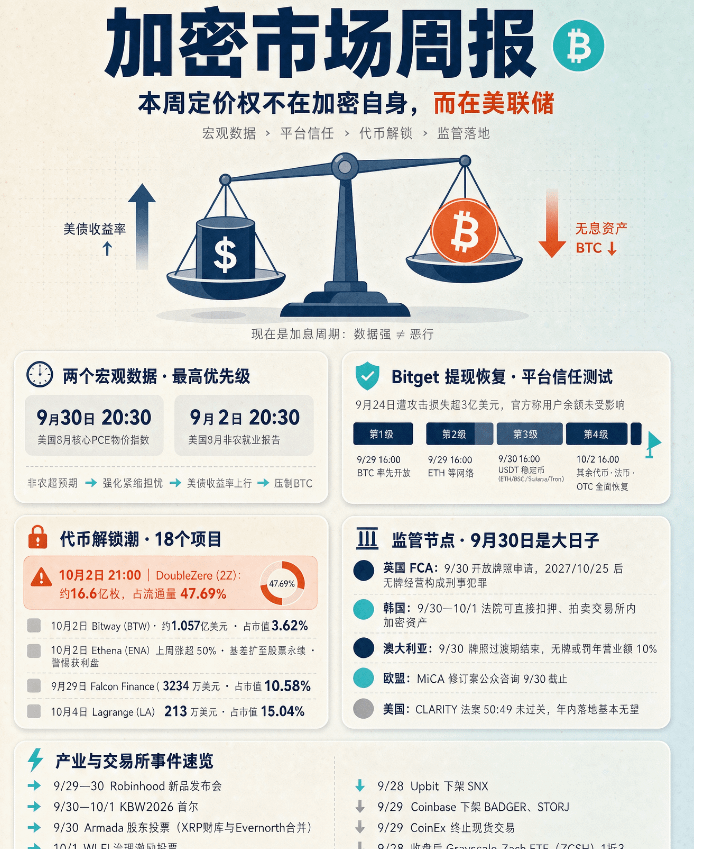
First, the judgment: in this week (Sep 28—Oct 4), crypto markets’ pricing power does not lie within crypto itself, but with the Federal Reserve.
I. Two macro data points that determine the direction (highest priority)
Beijing time: Sep 30 at 20:30; Oct 2 at 20:30
Data: US August core PCE inflation index; US September non-farm employment report
Key logic to recognize: this is not an environment of "data weakness → rate cuts → good news"; it is a rate-hiking cycle. If the Non-Farm Payrolls come in hotter than expected, it will actually strengthen concerns about tightening, push up US Treasury yields, and suppress interest-free assets like Bitcoin.
II. Bitget withdrawals resume: this week’s biggest test of platform trust
September 24: Bitget suffered a hack with losses exceeding $300 million. The official says the vulnerability has been fixed, user balances were not affected, and the losses are covered by the platform protection fund. This week is a critical window for phased resumption of withdrawals:
September 28, 16:00 → BTC opens first (CEO live AMA responding to the community at 15:30 the same day)
September 29, 16:00 → ETH and other networks
September 30, 16:00 → USDT-type stablecoins (ETH/BSC/Solana/Tron)
October 2, 16:00 → All other tokens, fiat, and OTC fully resume
Third: a wave of token unlocks—there’s one ratio that’s unusually and excessively high
September 28–October 4: roughly 18 projects unlock; focus on these:
🔴 October 2, 21:00|DoubleZero (2Z): about 1.66 billion tokens, 47.69% of circulating supply; value about $114 million—nearly half of the float is released at once, with very high sell-pressure risk
October 2|Bitway (BTW): about $105.7 million (3.62% of market cap)
October 2|Ethena (ENA): ENA surged by over 50% last week, and Ethena has just expanded its basis strategy to stock perpetuals—be cautious about unlocking compounded profit positions
September 29|Falcon Finance (FF): $32.34 million, 10.58% of market cap
October 4|Lagrange (LA): $2.14 million, 15.04% of market cap
Fourth: A dense rollout of regulatory milestones (September 30 is the big day)
UK: The FCA opens a window for crypto company license applications on September 30 and closes it on February 28, 2027; Operating without a license after October 25, 2027 will constitute a criminal offense. Existing AML registrations will not be automatically converted—platforms, custody, and stablecoin issuers all need to reapply
South Korea: New rules on civil compulsory execution for virtual assets take effect on September 30 / October 1. Courts can directly seize and auction the crypto assets held by debtors on exchanges; exchanges must cooperate to freeze
Australia: The digital asset license transition period ends on September 30; unlicensed companies may face a fine of up to 10% of annual turnover
European Union: Public consultation on the MiCA amendment ends on September 30
United States: Last month, the CLARITY Act failed in the Senate 50:49; passage within the year is basically unlikely. The regulatory gap will be filled by the SEC/CFTC through administrative rules; the five-year "innovation exemption" announced by the SEC on September 17 is the main current upside
Fifth: Industry events that are scattered but worth a quick look
September 29–30: Robinhood product launch event; the CEO preheats with "not to be missed"
September 30–October 1: KBW2026 Seoul
September 30: Armada shareholder voting (XRP escrow fund and Evernorth merger); Router Protocol, Fireplace, and Trepa shut down; Offramp stops crypto withdrawals
October 1: WLFI governance incentive voting
Delisting/withdrawal: Upbit removed SNX on September 28; Coinbase removed BADGER and STORJ on September 29; CoinEx ended spot trading on September 29
After market close on September 28: Grayscale Zcash ETF (ZCSH) share split (1-for-3)