

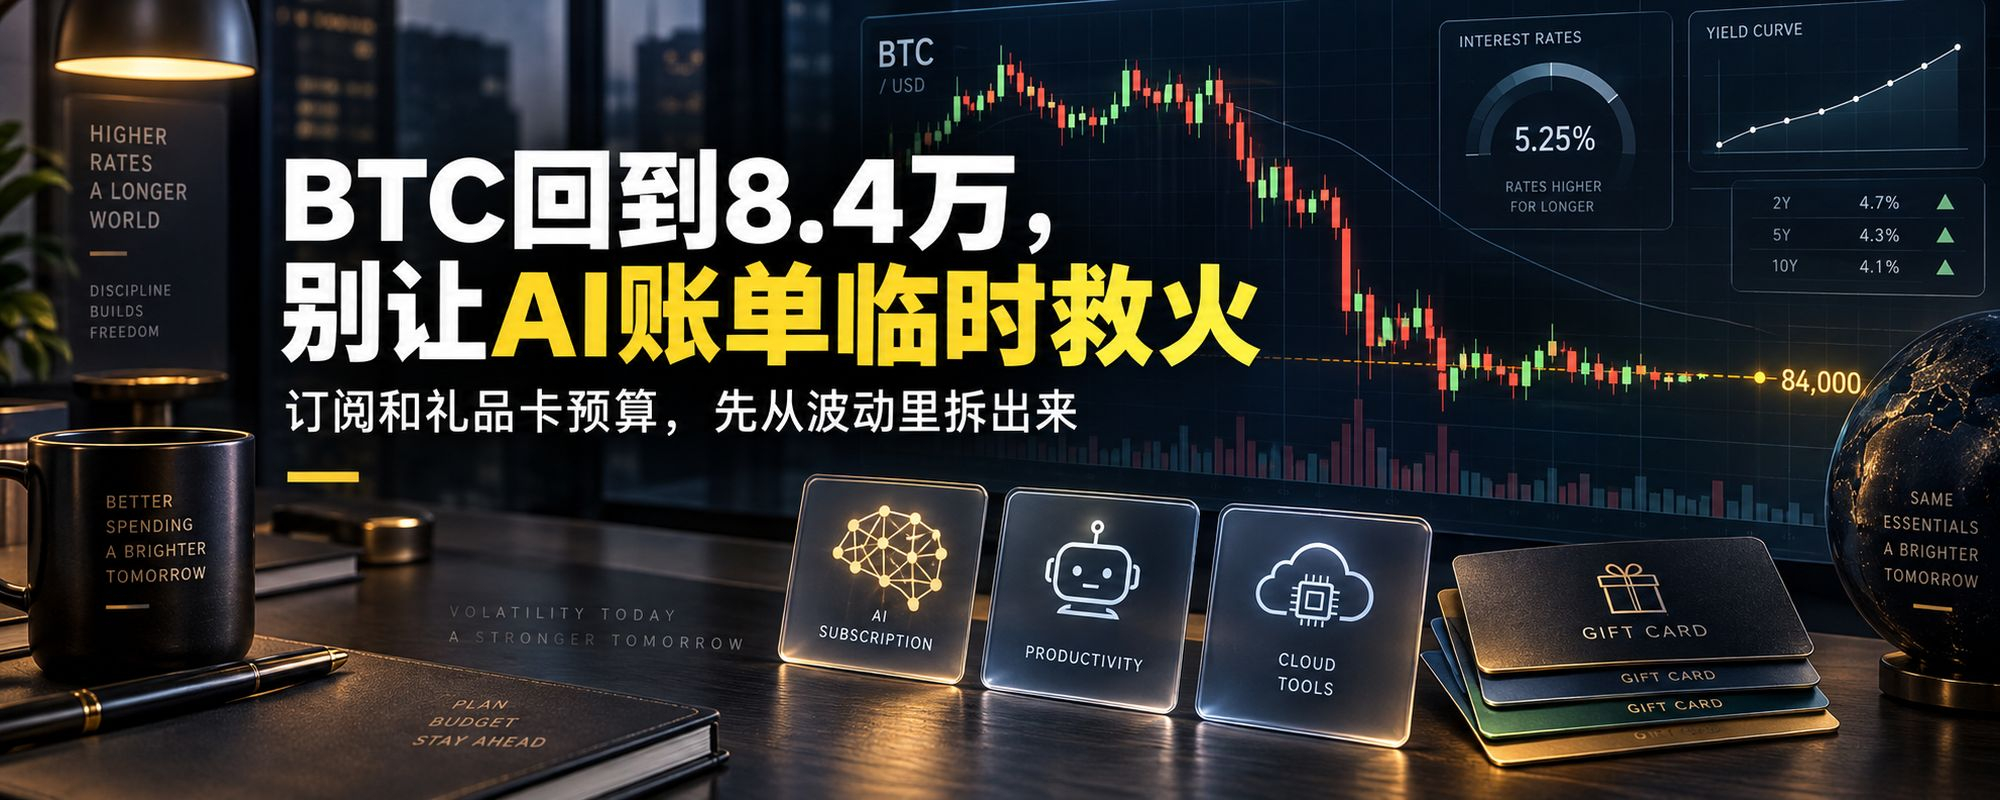
The most worth watching over the past couple of days isn’t just BTC hovering around $84,000—it’s the market is重新给 “the time cost of money” a new price tag.
Reports overnight said traders are starting to reprice the path to higher future interest rates, putting pressure on risk assets. Meanwhile, BTC has rebounded from the lows to above about $84,000, while ETH and SOL have only managed a small breather. On the surface, this looks like a market issue: whether it goes up or down, and whether you should jump in now.
But for many real users, at 8:00 in the morning there’s another more annoying problem: can your AI membership, code tools, cloud services, and shopping gift card budget be renewed smoothly today?
These small amounts—typically $20 to $100—can still be costly once they get stuck. AI tools can’t be used, project documentation can’t be accessed; when you need to buy gift cards temporarily, you find the assets are still sitting in a volatile trading position. Your shopping budget is already set, yet you have to swap assets first, wait for confirmation, and then top up the payment method. In the end, you’re not dealing with a small bill—you’re dealing with an entire money flow.
The more unstable the market is, the more obvious this problem becomes.
Many people put all their assets into a “waiting for a better price” state. When BTC returns to 84,000, they don’t want to sell; when it drops below, they don’t want to sell even more; when it rebounds, they want to wait a bit longer again. This mindset is completely normal, but it isn’t suitable for handling fixed expenses. A trading account seeks flexibility, while a consumption budget needs certainty. Mixing the two most often leads to this outcome: the market decides when you pay.
What really should be separated isn’t necessarily a large profit—it’s the money that you absolutely must spend in the next 24 hours to 7 days.
For example, today’s $29.9 AI membership renewal, the collaboration tool your team needs this afternoon, a $100 gift card you prepared for the weekend, or digital products and daily essentials you’ve already decided to buy. These expenses don’t need to participate in market timing; they just need to be available on time.
To put it a bit against common sense: the smaller, more frequent, and more certain the expense, the less you should route the full end-to-end money process every single time. Because what you save isn’t just a few dollars in trading fees—it’s the total cost of payment failures, waiting for funds to arrive, switching paths at the last minute, and interruptions to your work.
So under today’s market conditions, I prefer to view assets in three layers:
The first layer is the trading account, still exposed to volatility;
The second layer is stable balances, keeping liquidity/mobility;
The third layer is a fixed spending allocation—only handling known expenses such as AI subscriptions, gift cards, and shopping budgets.
This isn’t about getting people to exit the market—it’s about not letting every everyday expense be driven by market fluctuations. If you know how to trade, what you end up competing on isn’t just direction; it’s also cash-flow planning. Especially when macro expectations get harder again and the market feels uncomfortable both ways, being able to handle fixed bills in advance is itself a form of risk control.
After PayAll’s complete redesign, you can process two types of high-frequency spending—AI membership subscriptions and gift card purchases—through shorter, more direct paths. For AI subscriptions, see https://beta.payall.pro/explore/ai. For gift cards and shopping spending, see https://beta.payall.pro/explore/gift. The key isn’t adding another entry point; it’s avoiding the moment when payment fails and you’re forced to improvise and “rescue” the situation within the market.
#BTC #stablecoin