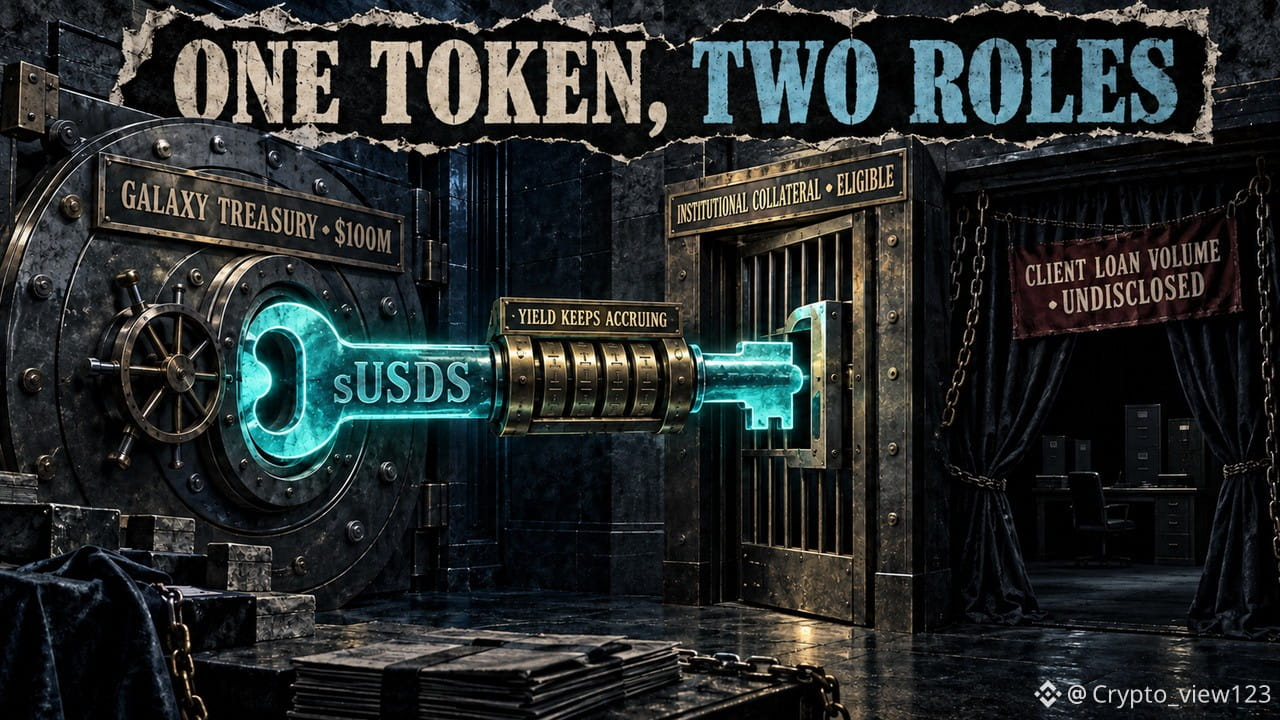
An institution puts a $100 million worth of savings certificates into its own balance sheet and allows customers to use them as collateral for loans.
A notice dated September 23 shows that a $100 million on-chain savings token was recorded in the institution’s corporate treasury and approved as collateral for institutional clients. The notice only gives the scope of approvals and does not disclose the volume of customer loans backed by the token, nor does it report the first completed lending.
The pitch is a dual benefit: after borrowers pledge the token as collateral, they can still continue to accrue returns at the savings interest rate. In other words, collateral and yield coexist within the same position. For borrowers, this is effectively liquidity without giving up yield.
But the verifiable parts are limited. The savings interest rate is determined by protocol governance, sourced from protocol surplus, and adjusts with funding conditions; the final deployment amount of the collateral is also not disclosed, making the real impact of the partnership hard to assess. Once governance parameters are changed, both the actual returns and borrowing costs will change.
For the industry, the progress of arrangements like this depends on on-chain data rather than the wording of announcements. The criteria are straightforward: whether real loans have actually occurred, and whether the collateral size increases over time. For institutions, what can be verified matters more than what can be marketed.
The announcement says “approved”; the data says “effect.”
#去中心化金融 #institution funds
A notice dated September 23 shows that a $100 million on-chain savings token was recorded in the institution’s corporate treasury and approved as collateral for institutional clients. The notice only gives the scope of approvals and does not disclose the volume of customer loans backed by the token, nor does it report the first completed lending.
The pitch is a dual benefit: after borrowers pledge the token as collateral, they can still continue to accrue returns at the savings interest rate. In other words, collateral and yield coexist within the same position. For borrowers, this is effectively liquidity without giving up yield.
But the verifiable parts are limited. The savings interest rate is determined by protocol governance, sourced from protocol surplus, and adjusts with funding conditions; the final deployment amount of the collateral is also not disclosed, making the real impact of the partnership hard to assess. Once governance parameters are changed, both the actual returns and borrowing costs will change.
For the industry, the progress of arrangements like this depends on on-chain data rather than the wording of announcements. The criteria are straightforward: whether real loans have actually occurred, and whether the collateral size increases over time. For institutions, what can be verified matters more than what can be marketed.
The announcement says “approved”; the data says “effect.”
#去中心化金融 #institution funds