

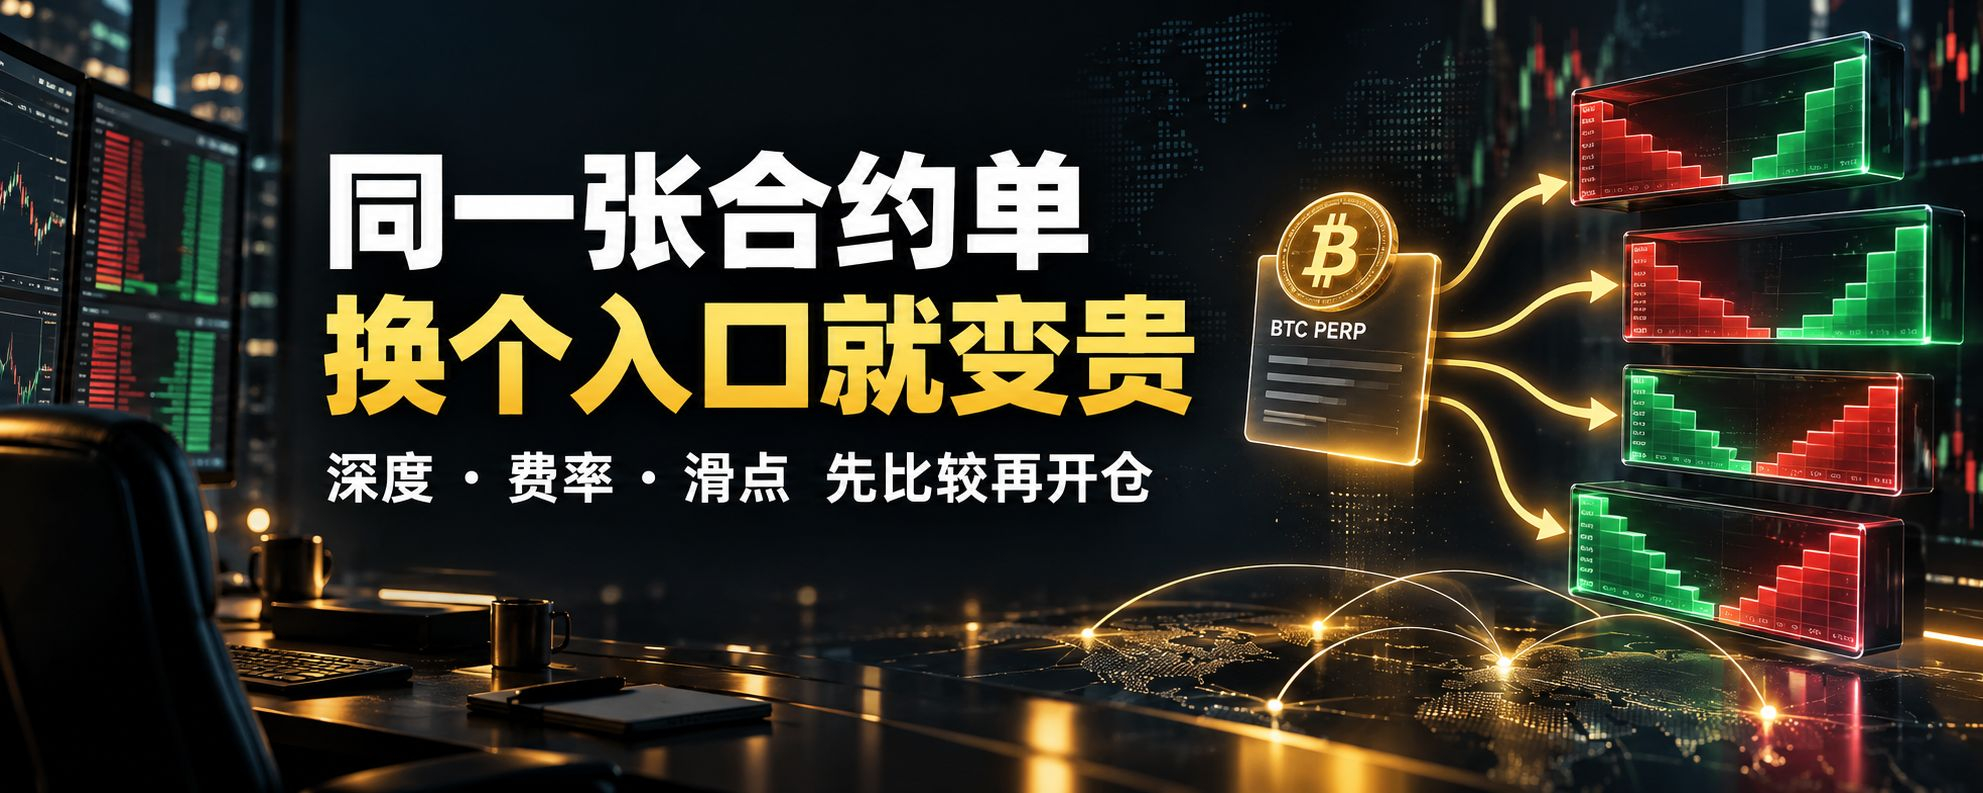
The same contract order—just a different entry point, and it ends up costing more
The most interesting thing this afternoon wasn’t the fact that BTC was again tugging around the $84,000 mark. Rather, it was that many people, despite watching the same price when opening their positions, ultimately paid completely different costs.
On the order book, prices moved down from above 87,000 back to around 84,000. Long liquidations triggered a broad pullback across altcoins as well. Short-term traders then began frequently doing three things: chasing rebounds, adding to positions, and flipping. It looks like everyone is trading the same BTC or ETH futures contract, but in reality, when they place orders, each person doesn’t actually get the same thing.
You think the difference is only a 0.01% or 0.02% fee—but it’s actually much more complicated than that.
The first layer is order book depth. For example, if you only want to open a 20,000 USDT notional position in a thin-depth market, a market order might sweep through several ticks. In a thick-depth market, the same order barely moves the price. Before the direction is even verified, your entry price already loses out a bit.
The second layer is the funding rate. After a drawdown, many people watch for whether the market has fallen “too much” and should bounce. But if one venue is crowded on the long/short side, the funding rate has already priced in sentiment early. When you hold for 8 hours or 16 hours, your cost starts gradually being deducted from your profits. Especially when doing short-term trades that carry overnight, the fee isn’t background noise—it’s part of your holding cost.
The third layer is stop-loss and liquidation rules. In a market like today—first rallying high, then pulling back—the easiest mistake is a misjudgment: you remember setting a stop-loss, but you didn’t actually look closely at what price triggers it, how the order book holds up, and where the liquidation buffer sits. With the same 1% stop-loss distance, in different execution environments it can mean a normal exit, or it can turn into passive losses after slippage widens.
So I’m increasingly convinced that the most dangerous habit in futures (contract) trading isn’t getting the direction wrong—it’s treating the “entry point” as an indistinguishable button.
Before opening a position, many people check the K-line chart, news, liquidation data, and support/resistance—but they rarely spend an extra 10 seconds before placing the order to see where this specific order should travel. The problem is: the faster the market is moving and the more fragmented liquidity becomes, the more valuable those 10 seconds are. You’re not searching for a forever-best venue—you’re choosing the most suitable execution spot for this order right now.
My counter-consensus view is: the competition for future Perp trading won’t just be about who gives you a more eye-catching entry button—it will be about who can help traders see clearly the depth, funding rate, slippage, trading fees, and differences in rules before they even open a position.
This is also how I understand the value of Perp aggregators like Perpex / PerpEX: first pick the asset, then compare the execution conditions across different venues, and only then decide where to route this order. It’s not about making trading more complicated—it’s about surfacing the costs that are normally hidden in the execution result, before you place the order.
The market is already hard enough to judge. At least don’t let the same contract order become more expensive just because you didn’t compare the entry.
#BTC #Futures contract trading