


Original|Odaily Planet Daily ( @OdailyChina )
Author|Wenser ( @wenser 2010 )
Will Avalanche become the official tokenized blockchain network of ICE, the parent company of the NYSE?
Last week, Ava Labs president Cooper said publicly that the NYSE has been testing Avalanche technology throughout the past year and assessing feasible paths to integrate it into existing trading systems. At present, both sides have established a partnership, but the NYSE has not yet finally confirmed whether it will choose Avalanche as its blockchain for tokenized securities. ICE, meanwhile, said the two sides are working closely together and that the Avalanche chain meets several requirements, but neither side has announced that they have selected each other at this time.
In January this year, the NYSE announced plans to launch a platform for tokenized trading of U.S. stocks and ETFs with on-chain settlement; in August, ICE’s parent company also invested in tZERO and chose it as a platform partner.
With the U.S. SEC opening up its innovation exemption policy for tokenized stock trading platforms, the new round of focus in public-chain competition has also shifted to the integration of liquidity trading platforms in traditional financial markets.
Why does ICE like Avalanche: technical strength, compliance advantages, and proven mature use cases
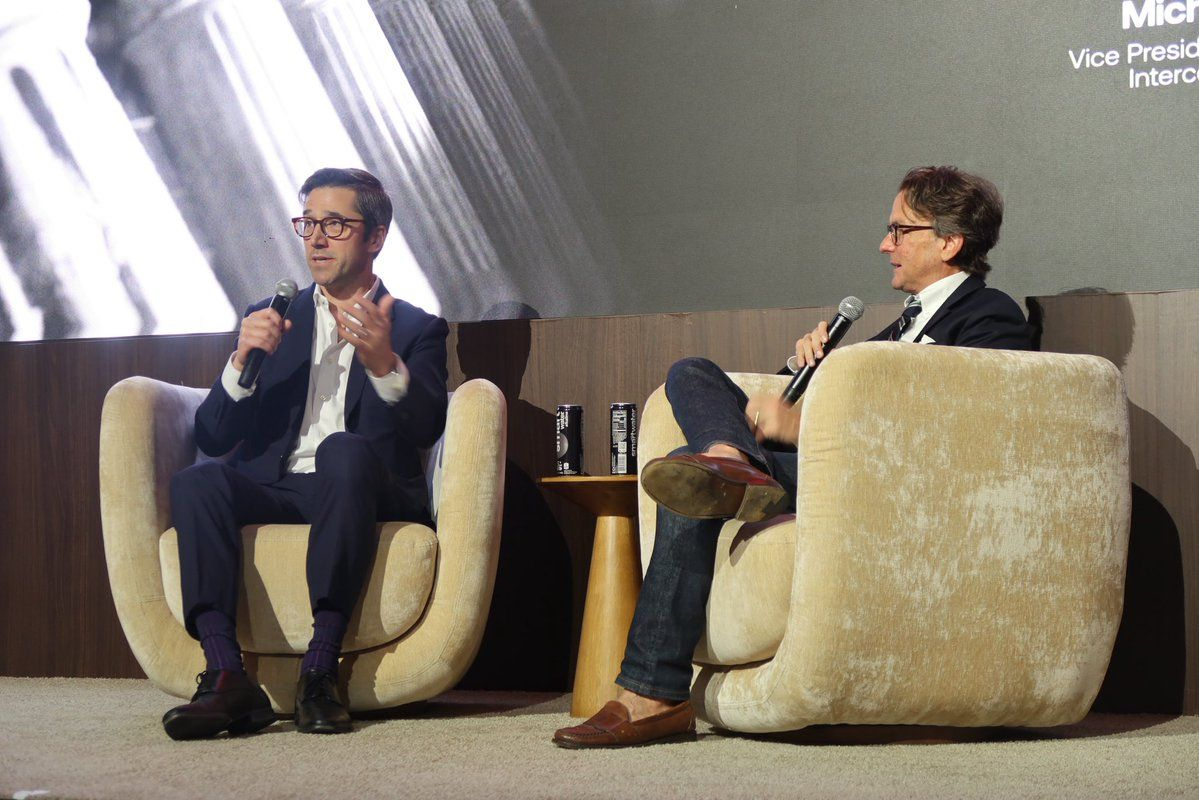
At the Avalanche Summit held last week, Michael Blaugrund, ICE’s strategic planning director, said that during the company’s evaluation of blockchain platforms, it has been “in close alignment” with the Avalanche team, and that “in many respects, Avalanche meets our requirements.”
And based on the information available so far, Avalanche is the biggest reason ICE considers it a “potential partner,” mainly for three reasons:
First, the strong technical strength accumulated by the Avalanche chain.
As a long-established public chain, Avalanche has accumulated strengths in public-chain performance, support for institutional wallets, interoperability, and its ability to connect with existing securities infrastructure. Its average cost per transaction is also extremely low, usually around $0.001–$0.02.
Second, it is Avalanche’s compliance advantage.
Apart from the inherent advantages of companies based in the United States, unlike other types of open public chains, the Avalanche chain allows institutions to directly embed compliance rules at the protocol layer while still preserving interoperability with the broader ecosystem. Relevant features include user and trading whitelists, validator permission controls, contract deployment controls, isolation and autonomous control, the Evergreen institutional framework, and a balance between privacy and auditing. In simple terms, institutions can flexibly adopt these measures as long as they meet regulatory and compliance requirements. Previously, token-related Avalanche ETFs and exchange spot products launched by companies such as VanEck, Bitwise, and Grayscale also reflect the rigor of their compliance.
Third, it is Avalanche’s mature use cases.
The first stablecoin backed by the Korean won—KRW1—released by U.S. Wyoming’s stablecoins, U.S. California DMV vehicle ownership, and the Korean crypto custody service provider BDACS; a multi-token platform based on Avalanche launched by Japan’s payments giant TIS; UAE PASS, a digital identity recognition system based on Avalanche launched in the United Arab Emirates; $2.7 billion worth of assets tokenized and put on-chain on the Avalanche-based Japanese securities token platform Progmat; a tokenized securities platform built on Avalanche by Hanwha Investment & Securities—these all run on the Avalanche chain and meet local regulatory requirements. In terms of existing mature use cases, Avalanche has delivered impressive results.
The road of collusion between securities exchanges and public chains: they need each other, not one being stronger than the other
At the same event, Ava Labs President Cooper said that within the next year, some securities trading venues are expected to begin offering 24-hour trading services on business days.
“Will it be a mainstream exchange? Will it be the largest exchanges globally—like the London Stock Exchange, the NYSE, the Chicago Mercantile Exchange, and so on? I’m not sure about that,” he said. “There are a number of smaller securities trading venues that are actively proving their appeal worldwide to attract liquidity.”
It’s clear that, to some extent, bringing in public-chain networks and rolling out tokenized platforms has become a consensus among many securities exchanges. After all, building a blockchain network from scratch involves not only technical issues and time costs, but also presents fewer incremental opportunities compared with integrating into mature blockchain ecosystem networks. Even a strong retail brokerage platform like Robinhood didn’t choose to build its own blockchain network from the ground up. Instead, it leveraged the technical foundation of Ethereum ecosystem L2 networks to launch today’s Robinhood Chain, which has dual support for “RWA assets + Meme coins.”
For the many public-chain networks out there, the comfort zone of crypto-native markets is no longer enough to support an even bigger vision and longer-term development. To gain more users, more trading volume, and more ecosystem-building projects, they must shift toward partnering with larger systems and frameworks. Traditional securities exchanges are naturally the best choice.
In particular, top U.S. stock exchanges such as the NYSE and Nasdaq—their trading volume, liquidity, and user markets are enormous “prizes” that crypto blockchain networks dream of. In the not-too-distant future, as tokenized stock platforms pass regulatory review by oversight bodies, the settlement and trading networks ultimately selected by traditional securities exchanges will achieve leapfrog development through their brand endorsement. By comparison, today the various TVLs within the crypto market’s ecosystem are still dwarfed by these opportunities.
Compared with past narratives such as ETF applications and listed-company treasury/custody stories, the institutional-level narrative that guides the next wave of development in the crypto industry may be possible only by relying on the partner ecosystem introduced through traditional securities exchanges. This point, together with regulatory reforms led by institutions such as the U.S. SEC and CFTC, may help the crypto market enter a second growth curve—when market size truly explodes into the trillion-dollar range.
Recommended reading
The U.S. SEC opens the “Pandora’s box,” and on-chain tokenized stock trading is officially underway.
SEC’s five-year “innovation exemption” takes effect—who gets the ticket to tokenized U.S. stocks?