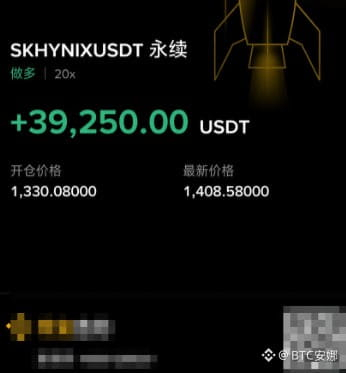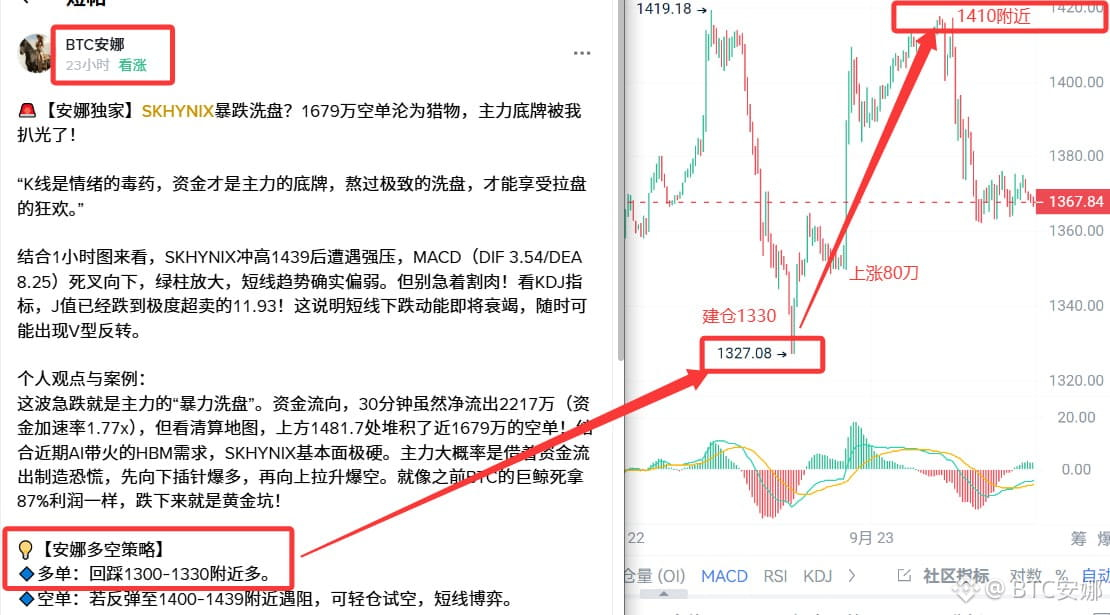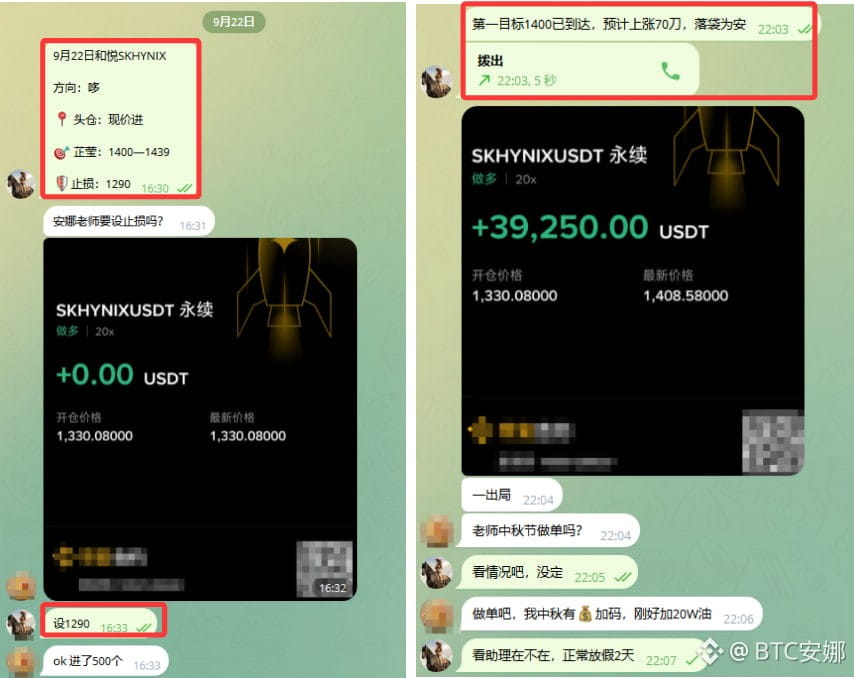
SK Hynix Zhi Ying 39250 oil, bought in at 1330, exited around 1400—overall captured a $70 move up!
Long-position setup rationale:
SK Hynix’s surge is driven by an AI-fueled HBM super-cycle: demand growth is outpacing supply, HBM4 prices are seen rising, and wafer shortages may persist until 2030. Financial performance keeps exceeding expectations—2026 Q2 operating margin above 76%. Customers are scrambling to invest to secure capacity, shifting industry power toward suppliers. Goldman Sachs, UBS, and others have raised their target prices to 3.0–3.5 million Korean won.
#AI股持续上涨还有哪些投资机会 #21Shares推出欧洲首只Zcash实物ETP $SNDK $SKHYNIX $ZEC