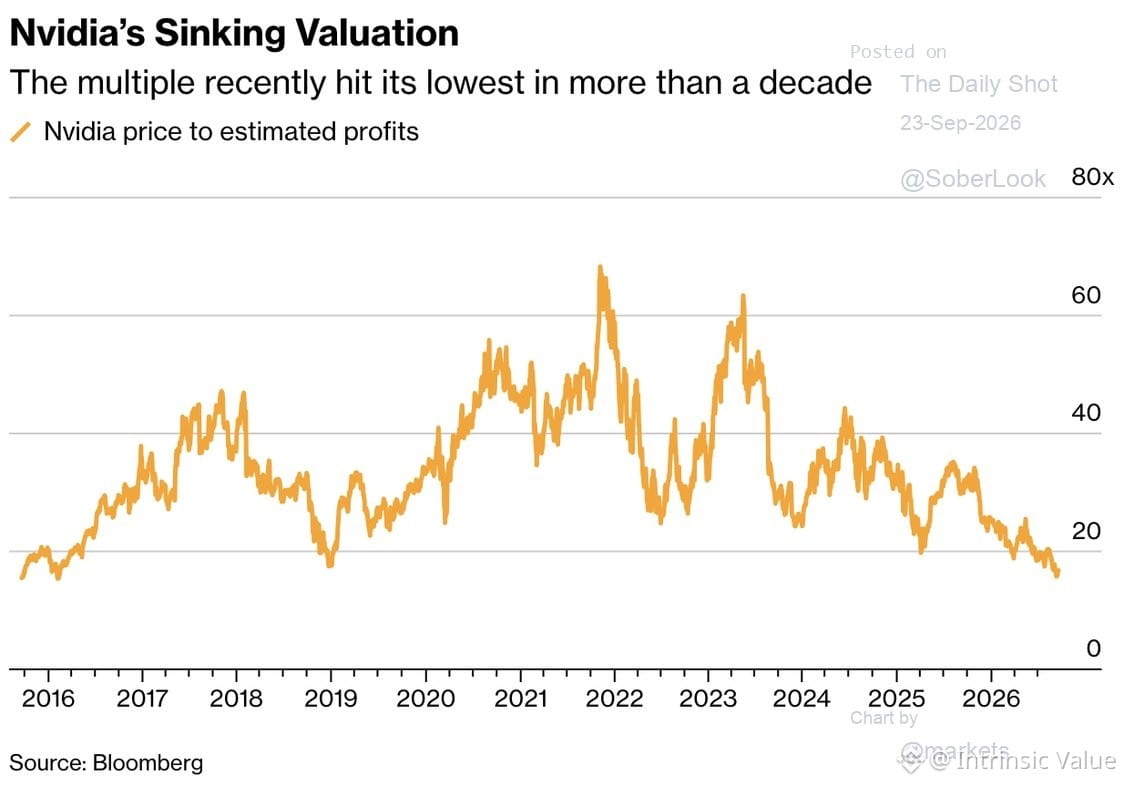
$NVDA trading at sub-17x forward P/E — lowest in over a decade.
Context matters. This is a company that's been priced for perfection for years. When growth expectations reset, multiples compress. The question isn't whether it's cheap relative to history, but whether the growth story that justified 50x+ is still intact.
Cheap can get cheaper if margins compress, competition intensifies, or AI capex cycles normalize. Forward P/E assumes the forward E is accurate. In high-growth tech, that's rarely guaranteed.
Valuation is always relative to fundamentals, not history.
Context matters. This is a company that's been priced for perfection for years. When growth expectations reset, multiples compress. The question isn't whether it's cheap relative to history, but whether the growth story that justified 50x+ is still intact.
Cheap can get cheaper if margins compress, competition intensifies, or AI capex cycles normalize. Forward P/E assumes the forward E is accurate. In high-growth tech, that's rarely guaranteed.
Valuation is always relative to fundamentals, not history.