

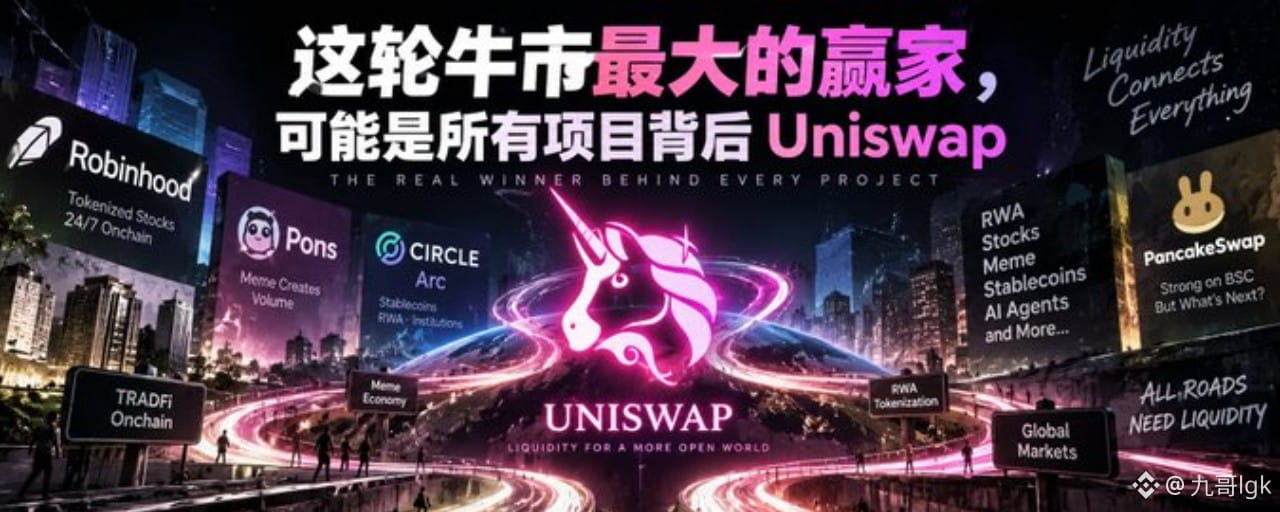
Recently, I’ve increasingly felt that if this bull market really continues moving toward on-chain finance, one of the biggest beneficiaries in the end probably won’t be any single chain or any one Meme, but rather Uniswap.
The reason is actually very simple.
Who issues the assets doesn’t really matter; in the end, all these assets need a place to trade.
Robinhood Chain has already run this logic recently.
Next, on September 16, Circle’s Arc mainnet goes live—time to run through it all again.
If in the future more and more stocks, stablecoins, RWAs, Memes, and even traditional financial assets are moved onto the chain, then what Uniswap truly wants to do may have long been more than just “a DEX.”
What it wants to do is:
The liquidity layer for on-chain assets.
01 | Robinhood Chain has already demonstrated a template for Uniswap
Robinhood Chain officially opened its public mainnet on July 1 this year.
From the start, Robinhood’s positioning was actually very clear: tokenizing stocks, RWA, and 24/7 on-chain trading.
And on the very first day the mainnet launched, Uniswap was already on it.
And it’s not a regular partnership.
The official Robinhood directly defined Uniswap as:
Primary Public AMM.
In other words, Robinhood Chain is mainly the public liquidity protocol. Uniswap’s V2, V3, and V4, UniswapX, the Web App, Wallet, and API were all fully integrated from day one.
What happened two months later might even not have been fully expected by Robinhood itself.
Robinhood Chain’s initial breakout wasn’t stock tokens.
It’s Meme.
Especially after Pons emerged, the trading volume across the entire chain suddenly got pulled up.
In early September, Robinhood Chain’s weekly DEX trading volume reached as high as $12.4 billion, more than doubling compared to the previous week. On September 4, the daily on-chain fees set a record of about $6 million.
Pons is even more exaggerated.
On September 2, Pons issued nearly 25,000 Tokens in a day; the 24-hour trading volume hit $544 million, generating about $5.95 million in fees that same day.
And here’s something that’s easy to overlook:
When Pons went big, Uniswap also ended up taking a large chunk of the upside behind it.
Because after the Pons V2 Tokens graduate from the bonding curve, they automatically enter Uniswap V4, creating permanent locked liquidity pools.
In other words, Pons keeps producing new assets.
Uniswap is responsible for picking up these assets’ long-term trading after they graduate.
That’s also why when I researched Pons V2 earlier, the more I studied it, the more I felt that Uniswap is the underlying infrastructure hidden in the back. Pons can issue tens of thousands of coins in a day, but for those coins to truly form a long-term market, they still need Uniswap.
02 | How many trades does Robinhood Chain have that go through Uniswap?
This data is what’s most outrageous.
A recent set of Robinhood Chain data shows that the 24-hour DEX trading volume is about $1.88 billion.
Among them:
Uniswap V3: about $879 million
Uniswap V4: about $601 million
Uniswap V2: about $51 million
Altogether, the three versions are about:
$1.53 billion
So, under this set of data definitions, Uniswap accounts for roughly 81% of Robinhood Chain’s DEX trading volume.
At peak times, it’s even more exaggerated.
Some statistics show that on the most active trading days for Robinhood Chain, Uniswap once handled close to 98% of on-chain DEX trading volume.
What’s more interesting is looking the other way around.
It’s not only Robinhood Chain that needs Uniswap.
Uniswap V4 also increasingly needs Robinhood Chain.
Data from early September shows that Robinhood Chain once contributed about 56.3% of Uniswap V4’s total network trading volume.
So this is no longer simply:
Uniswap has been deployed to the Robinhood Chain.
It’s rather that:
Robinhood Chain has become one of Uniswap’s most important new growth sources.
This difference is huge.
03 | After Pons went big, Uniswap’s response was very fast
There’s another thing here that I really appreciate about the Uniswap team: when a sudden competitor shows up, its response is extremely fast.
After Pons truly exploded, Uniswap Labs didn’t choose to fight it head-on all the way.
Instead, it bought PONS directly.
On September 3, Pons officially announced:
Uniswap Labs has purchased $PONS for long-term alignment.
That is, Uniswap Labs has already purchased PONS for long-term alignment of interests between the two sides.
How much it bought exactly, how much it paid, and where it bought from—neither side has published that yet, so we can’t just guess.
But the action itself is already very interesting.
Because Uniswap itself also built a Launchpad.
On August 5, Uniswap Labs launched Pools.trade, directly competing with Pons on Robinhood Chain.
When they launched, the number of tokens issued by Pools.trade even briefly exceeded Pons.
Less than a month later, Pons ran out.
By the end of August, Pons V2’s daily fees had already reached about $4.89 million, while Pools.trade was only about $38.6k.
Then Uniswap did something very smart:
Since you won, I’ll buy you.
This makes me think of Pump.fun and Raydium back then.
After early Pump.fun Tokens graduate, a large amount of liquidity will flow into Raydium.
The hotter Pump.fun is, the more Raydium makes.
But later, Pump.fun made PumpSwap itself.
After graduation, Tokens no longer need to migrate to Raydium; they can go directly into PumpSwap.
It’s like taking back the liquidity and trading volume that originally would have gone to Raydium into its own hands.
So from Uniswap’s perspective, it’s actually very easy to understand why it wants long-term alignment of interests with Pons.
Today, Pons V2:
Bonding Curve → graduation → Uniswap V4
Of course Uniswap hopes this route will exist forever.
If one day Pons becomes big enough to say:
Why should I send all my graduation Tokens to Uniswap? Can’t I build my own DEX?
Then the story between Pump.fun and Raydium might happen again.
So I think this move by Uniswap to buy PONS can’t be simply understood as:
“Uniswap likes PONS, so it buys the coin.”
It’s more like:
After Pons turned into Robinhood Chain’s very important asset issuance entrance, Uniswap wants to bind that entrance to its own liquidity layer long-term.
Of course, “to prevent Pons from copying Pump.fun/PumpSwap” is only my speculation for now; neither side has said that.
From a business logic perspective, this possibility is worth watching.
04 | After Robinhood, the next is Arc
If it were only Robinhood Chain, I probably wouldn’t think this was so important.
But on September 16, another heavyweight mainnet is coming:
Circle’s Arc.
Arc and Robinhood Chain actually share one thing in common.
They aren’t chains built in the traditional sense specifically for Crypto Native users.
Robinhood Chain wants to move stocks, ETFs, and RWA onto the chain.
Arc wants to move: stablecoins, payments, institutional capital, RWA, foreign exchange, and Tokenized Assets onto the chain.
Circle has confirmed that Arc’s public mainnet will go live on September 16. There are already more than 100 institutions and ecosystem projects participating in the build, including traditional finance firms like BlackRock, DTCC, and Standard Chartered.
And within Arc’s liquidity infrastructure, the same name appears again:
Uniswap.
Arc’s official team even wrote an article specifically explaining why Uniswap is needed.
There’s one line in it that I think is extremely important:
Lending protocols, derivatives, and LP strategies all require a deep, trustworthy swap venue before they can operate at any meaningful scale.
In plain human terms:
To make lending, derivatives, LPs, and RWA really run, first there must be a sufficiently deep trading market.
And one of the core liquidity protocols that Arc chooses is Uniswap.
That’s also why I started re-understanding Uniswap.
Previously, we looked at Uniswap:
A decentralized exchange.
Now maybe it’s time to look from a different angle:
Default liquidity infrastructure once new assets go on-chain.
Robinhood issues stock Tokens—it needs liquidity.
Pons issues Memes—it needs liquidity.
Circle builds Arc and needs liquidity.
BlackRock’s BUIDL going on-chain needs liquidity.
Exchanging between stablecoins requires liquidity.
In the future, with more and more stocks, funds, bonds, and commodities going on-chain, liquidity will still be needed.
Who issues the asset isn’t actually important.
As long as an asset needs to be traded, Uniswap has a chance to get involved.
05 | How big does Uniswap itself already have?
Now look at Uniswap’s own data.
Earlier, Uniswap officially disclosed that the protocol’s cumulative transaction volume has reached about $4 trillion.
And as of the most recent DeFiLlama data:
Uniswap:
About $3.35 billion in 24-hour trading volume
About $19.6 billion in 7 days
About $67.4 billion in 30 days
In the DEX market overall, the total trading volume over the same 30-day period is about $240 billion.
A quick calculation:
674 ÷ 2400 ≈ 28%
That means, currently, a single Uniswap protocol accounts for about 28% of total DEX trading volume over 30 days.
Based on the most recent 24-hour data, the share is even around 33%.
This is no longer the size of a “niche DeFi application.”
More importantly, the biggest difference between Uniswap now and before is:
UNI starts truly capturing protocol value.
After UNIfication at the end of 2025, Uniswap began gradually opening up Protocol Fees and using the protocol fees for programmatic UNI burns. After that, the scope expanded from Ethereum to networks like Arbitrum, Base, BNB Chain, and Robinhood Chain.
Recently, Robinhood Chain has even become a very important source of UNI burn liquidity.
In a set of data from September 3 to September 9:
Robinhood Chain contributed about 71.9% of Uniswap’s Protocol Revenue.
On September 4, Uniswap Holder Revenue reached about $1.15 million, of which about $0.925 million came from Robinhood Chain.
That is to say, on that day, about 80% of the value flowed back comes from this brand-new chain that’s only been live for a little over two months.
This is the change I think is truly worth paying attention to.
Previously, when Uniswap’s trading volume was huge, many people would ask:
What does that have to do with UNI?
Now this question is slowly getting an answer:
Trade → Protocol Fee → UNI Burn.
And this burn isn’t something that happens once in a while anymore—it’s been ongoing.
I even made my own UNI burn data dashboard called DeFiBurn. From the data of the past ten or so days, UNI’s daily burn volume stays mostly around 150k–200k UNI. As of now, cumulative burns have reached about 113.8 million UNI, which is about 11.38% of the total supply.
What’s even more worth关注 is where these burns come from.
As for cumulative token burn so far: Ethereum has burned about 107.4 million, Base about 2.73 million, and Robinhood Chain has already contributed around 2.09 million. And judging from the most recent real-time burn records, Robinhood Chain is still continuously contributing UNI burns.
DeFiBurn — Uniswap UNI burn data
So when I look at Uniswap now, I can’t just look at how much trading volume it has every day.
People used to often complain:
Even if Uniswap’s trading volume is bigger, what does it have to do with UNI?
But now this path is becoming clearer and clearer:
More chains → more assets → more trading → more protocol revenue → more UNI burns.
If Robinhood Chain is just the first case and in the future Arc and more chains can contribute similar trading volumes, then what’s truly worth watching about Uniswap isn’t only how much share it has in the DEX market today—it’s whether it can keep translating the growth of the entire on-chain trading market into value flowing back to UNI.
06 | Why I think Uniswap might be one of the biggest beneficiaries this round
I’ve been liking an investment logic more and more:
Don’t guess who will mine gold—go study who sells shovels.
Can Robinhood Chain become the biggest RWA Chain?
Don’t know.
Can Arc become the main settlement network for institutional finance?
Don’t know.
Can Pons beat Pump.fun?
Don’t know.
Which Meme will rise 100x in the next cycle? Nobody knows.
But all these things share a common requirement:
Liquidity.
Once assets are on-chain, they need to be traded.
Whenever there’s trading, there needs to be a market.
Uniswap is working to become that default market.
Robinhood Chain provides a very good example:
Robinhood builds the chain; Pons issues the tokens.
Users are trading like crazy.
Finally, behind the scenes, Uniswap has silently taken on more than 80% of the DEX trading volume across the whole chain.
Even Pons’s own success further feeds Uniswap V4 with assets and trading volume.
This is what’s most comfortable about infrastructure.
It doesn’t need to guess which Token will win.
The more winners there are, the more money it makes.
07 | Take another look at CAKE, which I also hold
At this point, I’d like to mention another project I hold: PancakeSwap.
I also hold CAKE and have held it for a long time, so this isn’t about bashing one project to hype another. The more I study Uniswap, the more I think the biggest problem with PancakeSwap might not be that the product isn’t good—it’s that it never truly shed the label that BSC gave it.
Strictly speaking, PancakeSwap of course left BSC long ago. It has deployed on Ethereum, Base, Arbitrum, Solana, and even Robinhood Chain, and it has also built a lot. This year, PancakeSwap even went through building things like stocks, ETFs, RWA, cross-chain trading, and perpetual contracts.
But the problem is:
Taking the product out of BSC doesn’t mean the moat leaves BSC.
PancakeSwap’s strongest point today is still BSC.
In the past 30 days, the total DEX trading volume across the whole BSC network is about $34.7 billion. Of that, PancakeSwap itself did about $24.5 billion—roughly 70%.
This achievement is actually very impressive.
But looking at it from another angle, this might also be CAKE’s biggest problem.
PancakeSwap is absolutely the king on BSC, but once it leaves BSC, it’s hard to replicate that kind of dominance.
Base has Aerodrome and Uniswap; Ethereum is Uniswap’s home base; Solana has its own liquidity ecosystem. Even on Robinhood Chain—just newly entered by PancakeSwap this year—the majority of trading volume is still Uniswap in reality.
So my biggest worry about CAKE right now isn’t whether PancakeSwap will die.
I think it probably won’t.
Its base on BSC is still extremely strong. It even achieved net CAKE deflation continuously for 35 months. As of this year’s July, PancakeSwap officially disclosed that its cumulative trading volume on BNB Chain has already exceeded $4 trillion.
The real problem is:
Where does its next growth come from?
This is something that gets more and more confusing for me after I’ve held CAKE.
If BSC explodes, PancakeSwap of course will benefit.
But if the next round’s biggest incremental growth comes from Robinhood Chain, Arc, Base, and Ethereum—coming from new assets like stocks, RWA, and stablecoins on-chain—can PancakeSwap become the default liquidity layer like it did on BSC?
As of now, I think it’s hard.
On the other hand, when I look at Uniswap, I see another path.
It doesn’t have to bet on any single chain.
Ethereum has it too.
Base has it too.
Arbitrum has it too.
BNB Chain has it too.
On the first day Robinhood Chain went live, it made Uniswap its primary public AMM.
After Pons explodes, the graduated assets go straight into Uniswap V4.
Next, when the Arc mainnet launches, it appears again in the core liquidity infrastructure.
Even now, Uniswap is already grabbing market share from PancakeSwap’s strongest hometown, BSC. In CoinGecko’s recent BSC DEX data, Uniswap V4 + V3’s trading share has already exceeded one quarter.
That’s what I think is the most terrifying part of Uniswap.
PancakeSwap is more like Uniswap on BSC.
What Uniswap wants to do is:
Uniswap on every chain.
I personally hold CAKE too, so of course I hope it goes up.
But if you ask me to compare these two projects’ upside in the coming years right now, I truly find myself leaning more and more toward Uniswap.
It’s not because PancakeSwap isn’t profitable, and it’s not because CAKE’s tokenomics model is bad.
It’s because:
CAKE’s core base is very strong, but the growth boundaries are becoming easier to see.
Uniswap’s base is already very strong, but its boundaries are still expanding outward.
08 | Finally
Uniswap has already changed from a simple decentralized exchange into
The liquidity layer for on-chain assets.
Back then, crypto mainly traded BTC, ETH, and Memes.
If in the future something like this really appears:
Stocks on-chain, funds on-chain, government bonds on-chain, stablecoin explosions, RWA on-chain, AI agents trading automatically…
Then all those assets ultimately need a place to complete price discovery and liquidity exchange.
Robinhood Chain has already started proving this logic.
After Arc’s mainnet goes live on September 16, we’ll quickly see a second case.
If more and more things start going on-chain, who provides the trading infrastructure for them?
From what we can see now, Uniswap is already in a very comfortable position.
Others are responsible for creating assets.
Others are responsible for creating the hot spot.
Others are responsible for attracting users.
Uniswap is responsible for collecting toll fees.
This might be the most worth researching business in this bull cycle.
Writing this still explains: I personally hold both UNI and CAKE, and I’ve held them for over 4 years.
So this article isn’t meant to bash CAKE to hype UNI, and it isn’t because of my positions either.
It’s precisely because I bought both that, after researching Robinhood Chain and Pons recently—and then seeing that Arc is about to launch—I’ve become even more convinced: PancakeSwap’s base is still very strong, but Uniswap’s imagination space might be bigger.
In my view, the biggest issue with CAKE isn’t that PancakeSwap doesn’t make money, and it isn’t that it will disappear. It’s that its strongest moat is still concentrated on BSC.
Meanwhile, Uniswap is doing another thing: no matter whether the next breakout comes from Robinhood Chain, Arc, or other chains in the future, it wants to become the default liquidity infrastructure once those assets are on-chain.
Of course, just because the protocol develops well doesn’t necessarily mean the token price will rise. Whether market share and protocol revenue can continuously translate into UNI value is something that still needs to be observed.
I personally hold two of these coins, so the viewpoints in the article are definitely influenced by my own understanding and my holdings.
This article only records my research and judgments about Uniswap and PancakeSwap at my current stage, and it does not constitute any investment advice.
If you find any data or understanding that’s inaccurate, feel free to comment and correct me directly.
After all, you can buy the wrong coin, but the logic can’t stay wrong forever. 😂
Thanks for reading this far, and feel free to exchange ideas with me as well.
Jiu Ge | lgk
X : @Lgk007