

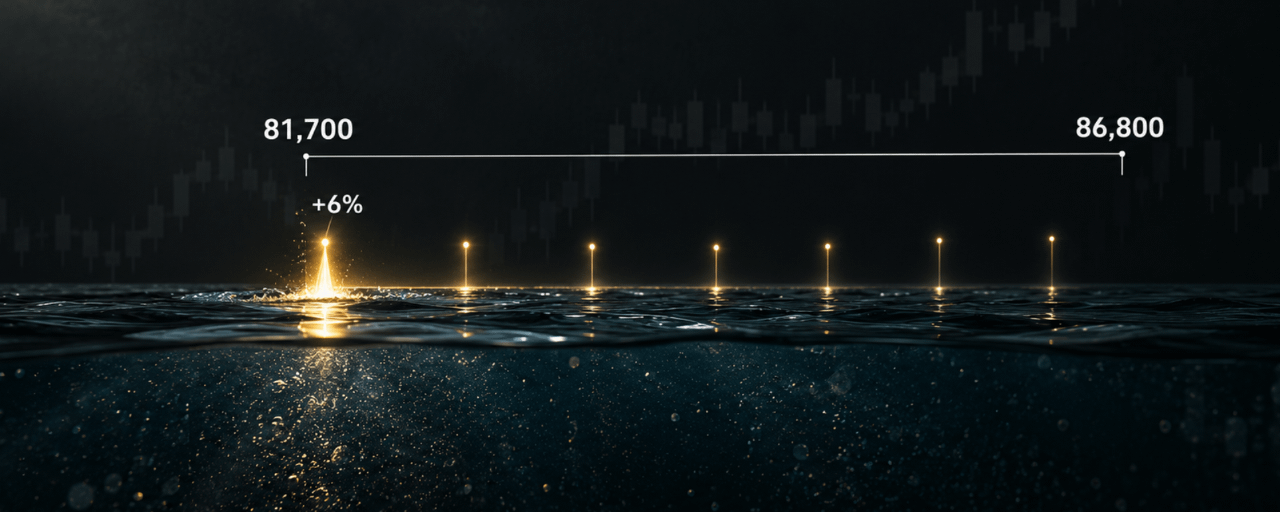
ETF Holders Back Above Water. The Cost Basis Is $81,700.
Summary: BTC’s breakout to 86,000+ has brought holders with an average ETF cost of 81,700 back to breakeven—first time since January.
On September 22, Bloomberg ETF analyst James Seyffart posted a brief update on X: the rise in the New York market early Monday pushed the average investor cost basis for U.S. spot Bitcoin ETFs (about $81,700) back into profit territory. This is the first time since January this year.
Bitcoin’s intraday high touched $86,800, with the latest at about $86,800. Still more than 30% below last year’s all-time high of $126,000.
How did the number 81,700 come about?
An ETF’s average holding cost is calculated by weighting all net inflow funds by the day’s price. It’s not a single person’s buy price; it’s a composite average.
This number returning to a profitable range means two things.
First, the ETF capital that has been posting sustained net inflows since the start of the year has just barely emerged from underwater. Along the way, it went through October’s historic peak, the end-of-month liquidation at a scale of $19 billion, and then a subsequent pullback. During this period, ETF holders have been losing on paper.
Second, the average cost is $81,700, while the current price is $86,800. That means the unrealized gain is only about 6%. If the price falls back to around $82,000, ETF holders would again return to hovering near the break-even line.
Coming back to break even on average doesn’t mean everyone has broken even. $81,700 is a weighted average, meaning a substantial portion of ETF investors bought at prices higher than this number. They haven’t broken even yet.
Two days versus one week of fund flows
Last week, U.S. spot Bitcoin ETFs recorded more than $6 million in net inflows. This figure may look small, but when you break down the structure, it’s completely different: on two trading days, Thursday and Friday, investors put in nearly $593 million.
$6 million for the week, $593 million for two days. This implies that from Monday to Wednesday, there were net outflows totaling roughly $587 million.
This pace matches the price action. On September 15, the CLARITY Act vote failed; on September 16, the Fed raised rates; and over the previous couple of days, ETF flows saw large-scale outflows. After the SEC issued its innovative exemption on September 17, flows reversed. The inflows on Thursday and Friday were the result of sentiment repair—not a sustained trend.
At present, the total assets under management of these ETFs are about $98.8 billion.
Two clues in the background
The first clue comes from the U.S. Treasury. Bitcoin started rising in August, and one of the triggers was the Treasury’s announcement that it would at least double the size of its long-term bond buybacks. Buying back long-term bonds means injecting liquidity into the market and pushing down yields on the long end. This is one of the fuels for a “currency depreciation trade.”
The second clue comes from late October. After Bitcoin hit an all-time high of $126,000 in October, it then suffered the largest liquidation in crypto history by month-end, with more than $19 billion in positions closed out. The price fell sharply from the peak, trapping ETF holders’ average cost line.
Although the Fed turned more hawkish afterward, investors have continued to pour into the so-called “currency depreciation trade,” pushing Bitcoin prices higher. The ETF’s average cost returning to the profit range is the result of this round of rebound, not the cause.
What comes next?
Can $82,000 become new cost support? An average cost of $81,700 means there is a psychological “unwilling-to-sell” zone around this area. If the price retraces but doesn’t fall below this level, ETF holders’ position stability will be stronger.
Is the fund flow continuous? Last week’s $593 million was concentrated over two days, while the total for one week was only $6 million. If there are net outflows again in the first three trading days this week, it would suggest there is selling pressure among holders who have already come back to break even.
The distance between $86,800 and the yearly moving average line. After BTC broke above the yearly moving average line around $85,000, it moved higher to $86,800. This level is close to the peak area from March 2024, making it the next technical reference.
A bigger chessboard
The fact that ETF holders come back to break even by itself does not constitute a directional signal. What it indicates is that after the October peak, the end-of-month liquidation, and the subsequent pullback over the following months, capital through the ETF channel has not pulled out on a large scale.
The average cost is $81,700, and the current price is $86,800. A 6% unrealized gain is thin, but it turns a batch of holders from “stuck” to “watching.” People who are watching won’t sell just because they’ve come back to even, but they will get tense again if the price falls back below the cost line.
The $81,700 line—now it has become a psychological line of defense.
#BitcoinETF #JamesSeyffart #CostBasis #CurrencyDepreciationTrade